
Good set of results
3 Likes
Company: VRL Logistics
CMP: 469
Market Cap: 4100 cr
Revenue (Q3FY25 TTM): 3120cr
EBITDA margin: 16%
5 year average ROE: 19%
Net debt of 460cr
P/E: 31x
- Company is a B2B part-truck load business; Industry is roughly around $9bn but is very fragmented and is mostly into unorganised segment; very few large players with PAN India presence
- Two key drivers for revenue is Volume & Pricing
- Company has fleet of 6100 own trucks & is aggressively adding more trucks; it’s the only company in Industry which has such a large fleet of own trucks; rest all operate on lease model + company has branch network of 1248 branches PAN India, on an average company is looking to add 70-80 branches annually. Both these initiatives will lead to volume growth of 8-10%, slightly above the GDP growth rate as they are gaining market share through systemic shift from unorganised to organised segment
- On pricing front, due to high competitive intensity, Industry was not able to do price hikes, however in Jun’24 company has announced price hikes; this will help hem in operating leverage
- Other than above, Company is doing lot of operational efficiency steps like buying fuel in bulk, route optimization, focussing on hub to spoke vehicle utilization, control on hired vehicles, etc – which would lead to further efficiency
- Company has guided for 12-13% revenue growth with 18% EBITDA margins – together this will lead to 28-30% growth on EBITDA & even larger growth in PAT. Additional as company’s major focus is on MSME, if economy revive on account of government initiatives (like Income tax cuts, GST cuts, etc), company could even perform better
- Company currently has nert debt of 460 cr. Company annual cash flow from operations was around 425cr in FY24, post which company has announced price hikes, so hereon company annual cashflow would be around 600cr, hence company is in very comfortable position to repay debt + spend 160cr on acquisition of new trucks in FY26
- Company working capital cycle is 9 days which is the lowest in the industry, average ROCE is in range of 15-20%
- Company’s last 10year / 5 year / 3 year average P/E is 34x / 36x / 37x against its current P/E of 31x
If company is able to do 8-10% volume growth (on account of economy revival or its branch / truck expansion initiatives), due to operating leverage, it would have high PAT growth and market would take it positively.
Thread link: VRL Logistics - value unlocking due to promoter actions
Q3FY25 call transcript: https://www.bseindia.com/xml-data/corpfiling/AttachHis/5e0c2153-99e0-499d-9911-f27d7212f937.pdf
Q3FY25 presentation: https://www.bseindia.com/xml-data/corpfiling/AttachHis/a5fcd97b-aa26-4337-8fec-ed1d80b9ad62.pdf
11 Likes
This thread seems dead. I have a company that is giving 20% growth guidance…shanti gold
2 Likes
Jwellery sector is facing tailwinds now. I am tracking Aurionpro which is clocking close to 30% growth
5 Likes
LGD seem like a good bet rn. Prices have been stable since July 2024. Huge TAM
1 Like
Sorry, I did not understand. LGD?
Edit - lab grown diamonds
1 Like
Lgd will fall down noticably since de beers got the judgement about lgd not to be called diamonds
1 Like
They just have to be specifically called lab-grown diamond. Not that big of a deal especially when people think about prices. In india, LGD is just 1%.
2 Likes
Stallion has re-affirmed it’s guidance of 30% - 35% CAGR growth for next 3 years and latest concall.
3 Likes
It seems a great company and from management’s words it could be inferred that they know what they are doing but there was one question targeted in the concall regarding the pricing power of the products as compared to the other competitors and the answer seemed to be non relevant with the context citing the size of the industry was enough for everyone to reap the benefits.
Does that really matter?
People buying (or may have bought for that matter) LGD’s certainly know what it is. Big players have lobby and as it’s evident that more often than not the judgements or regulations are for their benefits.
A parallel analogy…babies born out of unconventional processes, are still babies of humans. LGD’s are here to stay (though commoditized). Titan’s management spoke inferior of LGD but to the surprise, within a quarter threy announced to enter LGD business under a different brand (as far as I can remember) though keeping Natural and lab grown in seperate baskets. It’s evident that trend toh hain aur FOMO sab ko hota hain…
6 Likes
Any particular company you’re looking at?
1 Like
Invested in IGIL and Goldiam. Also, Titan is quite interesting but not strictly a pure play
1 Like
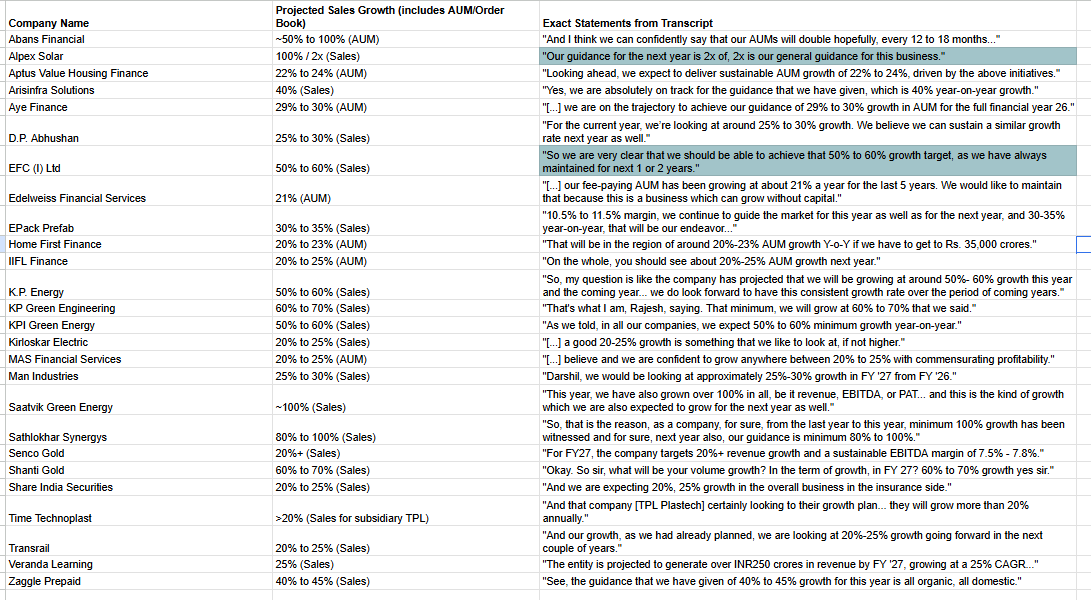
Here is a list of stocks with beaten down stocks with recent qtrly profit sales>20% and where mgmt has guided for more than 20% growth -
13 Likes
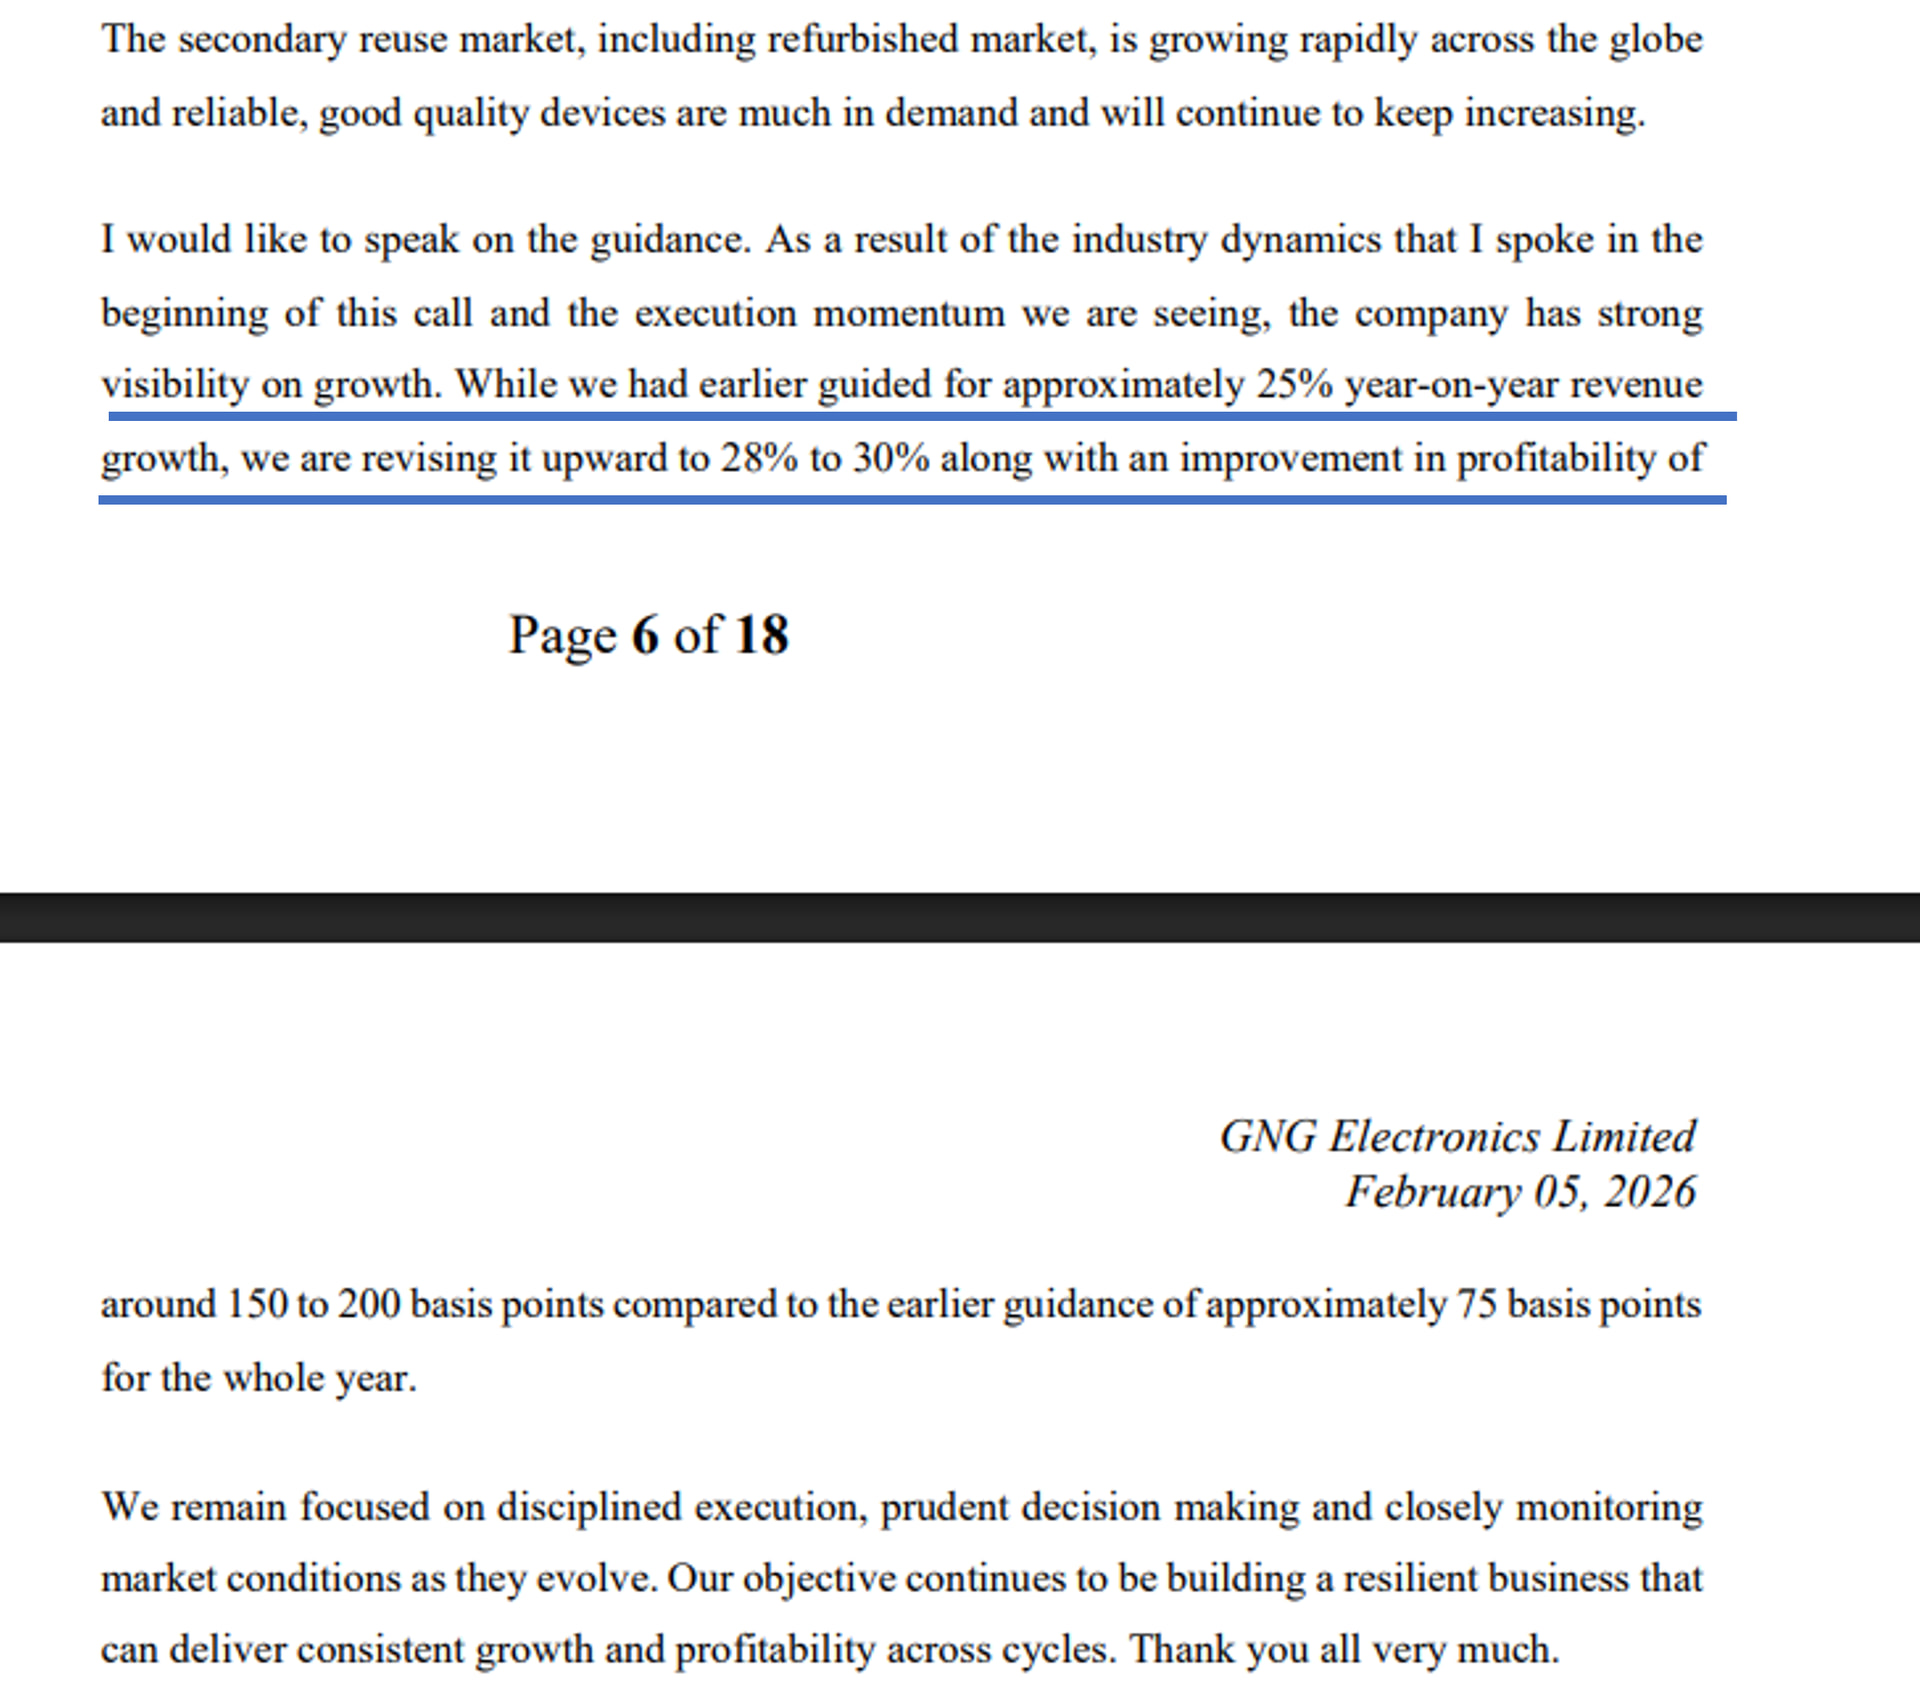
GNG electronics (which got listed in July last year) has guided for 28- 30% growth. Grew by 40% in Q3 and 25% in Q2
3 Likes
Well, tracking most of the companies specially KP Group, the only thing to get some rerating is not end of war , but conversion of cashflow from operating profit, there are still some grey areas in some companies , if the clouds are clear , questions gets cleared.
Debt is high compared to other peers.
The thread and the list were a nice contribution to the family of investors. However, the ‘TIME’ asserts its own power. Doing a cursory recap, it emerges Gensol is subjected to a Dissolve, not being absolved of their deceits, desires, and defiance of corporate governance principles.