Chandan Healthcare, incorporated in 2003, is one of the fastest-growing regional diagnostics chains in North India. It is an integrated healthcare platform with pathology, radiology, pharmacy, and government PPP operations.
· The Indian diagnostics industry is fragmented with about 50% of market with standalone labs offering consolidation opportunities for companies like Chandan.
· The company is now pursuing aggressive expansion across India and is evolving from a Lucknow-based regional player to a national chain. While most of its centres are still in Uttar Pradesh and Uttrakhand, it has presence in 15 states.
· It has 85 company owned centres and 685 franchisees as of September 2026. In H2 of FY 2027, it plans to add 10 more company owned centres and about 400 franchisees taking the total number of owned centres to 85 and franchisees to more than 1,000.
· Tie-up with Jeena Sikho is helping them to go to other states. Jeena Sikho has also invested in the company.
· Hub-and-spoke model optimises use of capital and increases ROCE. Hubs are company owned and spokes are franchisee owned. Co’s strategy has evolved from own-center led business to leveraging franchise network – this lever was missing in company’s strategy which all major players have. It is going to boost utilisation of capex heavy centres to achieve profitability quickly. PAT margins are expected to increase. Franchisees to increase to 1,000+ this year and 3,000+ over next 2-3 yrs. EBITDA from franchisee business is >50% (as company does not bear any costs - collection, transport, rent, etc).
· It listed on NSE Emerge in February 2025 and raised INR 107 crores at a price of INR 160. It has further done a QIP of INR 104 cr at a price of INR 234, of which about INR 40 crs has been received by the company.
· Migration from SME to Main Board - With the paid up capital of the company expected to increase to more than INR 25 cr, the company is expected to migrate to the main board shortly (in line with extant rules of exchanges).
Guidance by company for high growth:
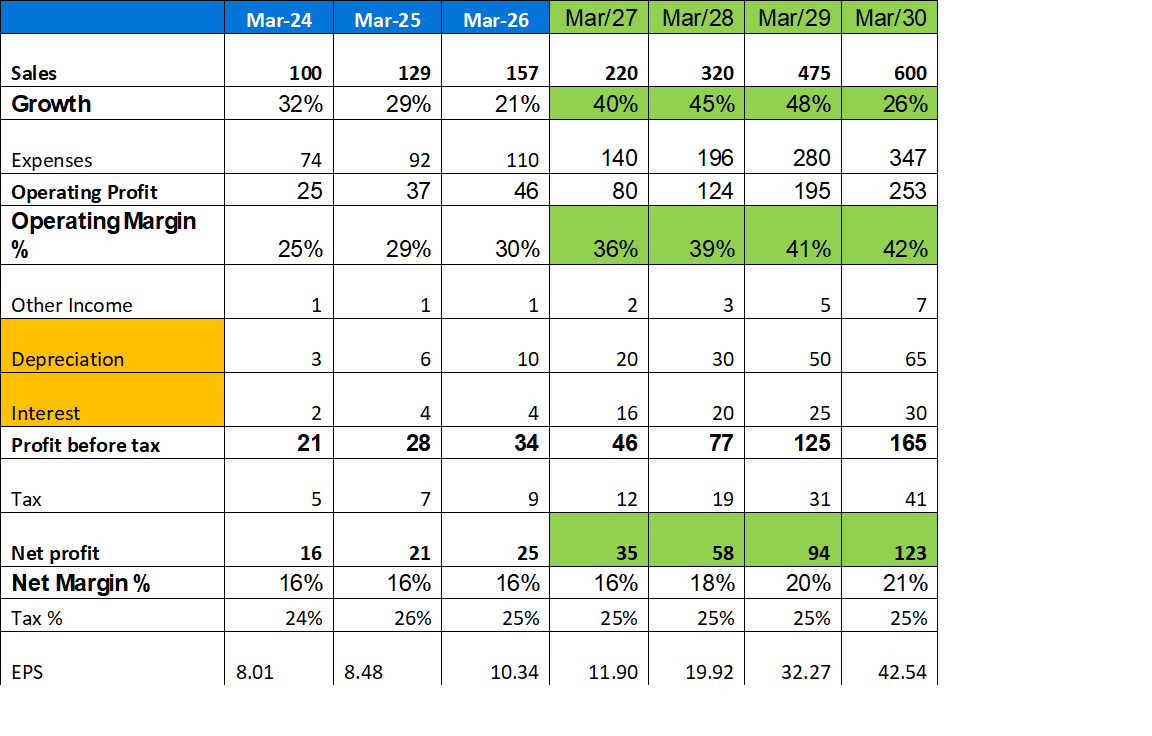
- Sales to increase 50% p.a. for 3 years - 240cr in FY27, 350Cr in FY28, 800cr by FY30 (standalone- without pharmacy which has been sold). Company grew 35% in Q1 and 46% in Q2. At expected levels of sales of 550cr by FY29 and net margin of 20%, PAT will be 100Cr.
- EBIDTA and PAT margins are expected to increase to 40% and 18% in a few months with increase in overall sales and sales per centre due to business from franchisees. When addition of new centres stablises EBIDTA and PAT margins will be much higher.
- No plans to raise additional equity so further dilution is not expected. Pref issue & internal accruals enough for growth.
- Receivables from Govt. is a concern but there are no bad debts.
How will the numbers be achieved:
1. 14 new centers will become operational in FY27
2. Franchisees are going to transform the company -they were the missing channel in Chandan’s strategy. EBIDTA from franchisees is higher at 60% of sales and will be directly add to PBT increasing net margins substantially. It is similar to increasing capacity utilisation in manufacturing companies.
3. 1,000 franchisees generating at least INR 50,000 revenue per month translates into sales of >60 cr p.a. If we assume average 500 franchisees in FY 27 (as franchisees will increase over the year) sales will increase by 30Cr. Remaining increase will come from B2C revenue from own centers, B2B and B2G verticals. Franchisees it will add about 13.5 Cr to PAT ( 500*50,000*60%*12months*0.75 post tax) - this is about half of FY26 PAT.
4. Franchisees will increase to 3,000 in 2/3 years fueling further growth in coming years - translates into addition of 50cr to PAT in FY 28 (over and above what company labs will generate).
5.Company targets to have a lac franchisees across India over time. Franchisee business is similar to a hub and spoke model of other players like Dr. Lal, Vijaya, Suraksha, etc.
Based on guidance given by management and recent performance by company, i have prepared some numbers. Please note these are projections based on management guidance.
Request feedback on this. Thanks.