Once all companies are done reporting Q1 numbers, Bhagyanagar will emerge as the leader in per-tonne profitability across recyclers, processors, and converters, irrespective of the underlying commodity.
As volume growth picks up in Q2, earnings will scale exponentially.
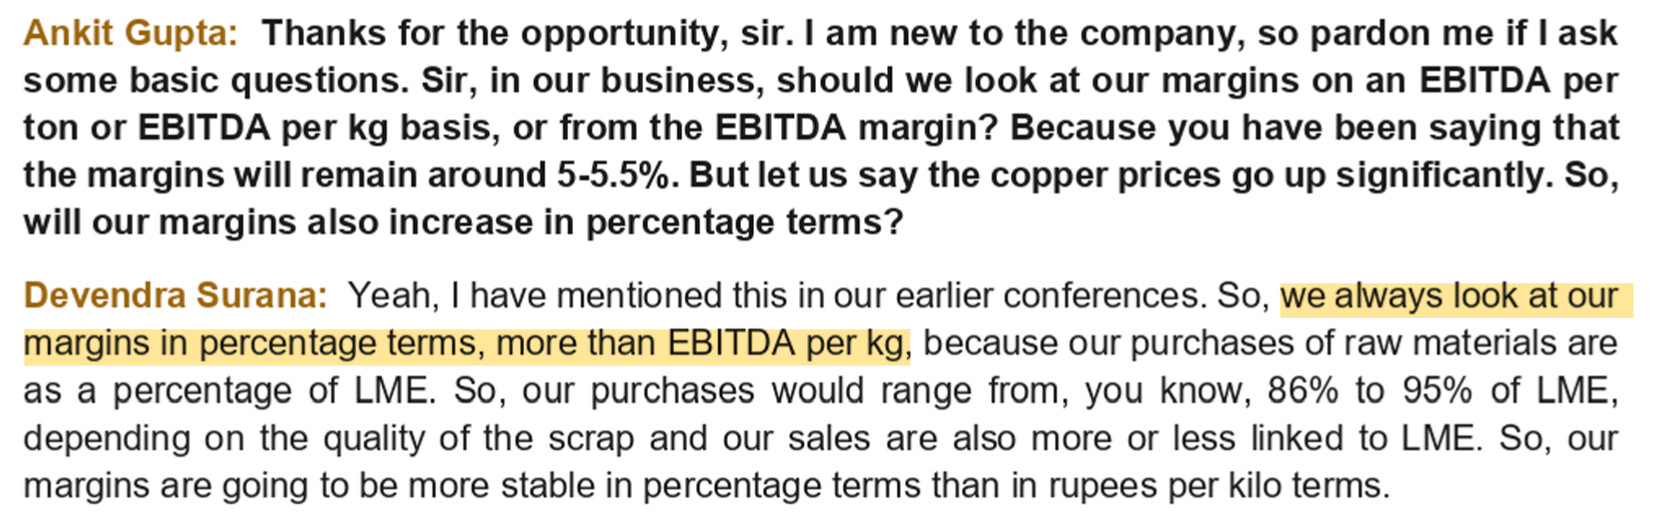
Bhagyanagar calculates EBITDA/kg on primary sales volume, while EBITDA also captures by-product economics. Combination of copper, aluminium or plastic from the same scrap along with copper.
By-product sales rose to ₹28.4 cr from ₹6.3 cr. That can materially lift the reported unit metric.
(Excerpt taken from a tweet by @technofunda05 account on X)
stock has quadrupled in less than a year. A one way climb is dangerous we should see consolidation along the way which is happening right now. It may take some time before the next phase of growth. Good time to average up in my opinion.
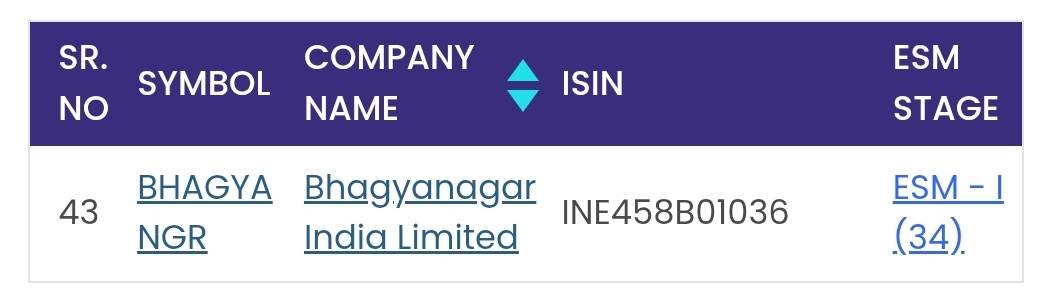
Does anyone have knowledge how esm circuits work? When are they applied and removed?
I have been watching Bhagyanagar in 5% circuit since many months. Quite a few stocks have gone and come out of such circuits but BIL stays as is. What is the method to this madness?
After locki-in ends, exchange reviews the volaitilty in the stock on weekly basis for few weeks
also the trailing volatitlity. since entry criteria are based on trailing 3/6 or 12 month price variations, to finally get an EXIT, the stock must no longer meet the entry criteria (which is a difficult proposition given bhagyanagar’s historical 3to 12 month’s price variation).
So I guess, once its trailing volatility metrics cool down and drop below the exchange’s standard deviation benchmark, BIL will be released during one of the weekly reviews.
Its easier to get an entry but difficult to have an exit…
Demerger with Tiermet announced (atleast on Zerodha). 1 Tiermet share for 1 Bhagyanagar. BIL value (or price) retained at ~10% of last traded price. Anyone tracking this and how to look at the demerger
Looking at only yesterday’s closing price and the wind and real estate left in demerged bhagyanagar, my understanding is that partial value unlocking has materialized. The remaining land, was roughly 26crores in books, is now being valued by the market at current mcap of ~140 crores a 5x appreciation.
Any idea when will Tieramet list and at what price? Will it list at the same price as Bhagyanagar was previously trading which is around 400 and we will get the same quantity?
The land bank is worth 600 cr at market prices as on date. The stock can still go up by a decent amount even if we give a 50% discount to the land bank value
Co. MD estimates the Land Bank along with Wind Assets to be worth ₹300 crores. This was not an official market figure, but a ballpark estimate. ₹600 crore seems to be overly stated. (as of 9 October)