Exited completely after listing to con call. As there is low allocation they will try to increase production of ENA, which is lower price as compared to ethanol.
Even though maize prices dropped in market, they are not able to get the maize at cheaper price and 40% mandate to produce ethanol from FCI rice would pull the margins down further.
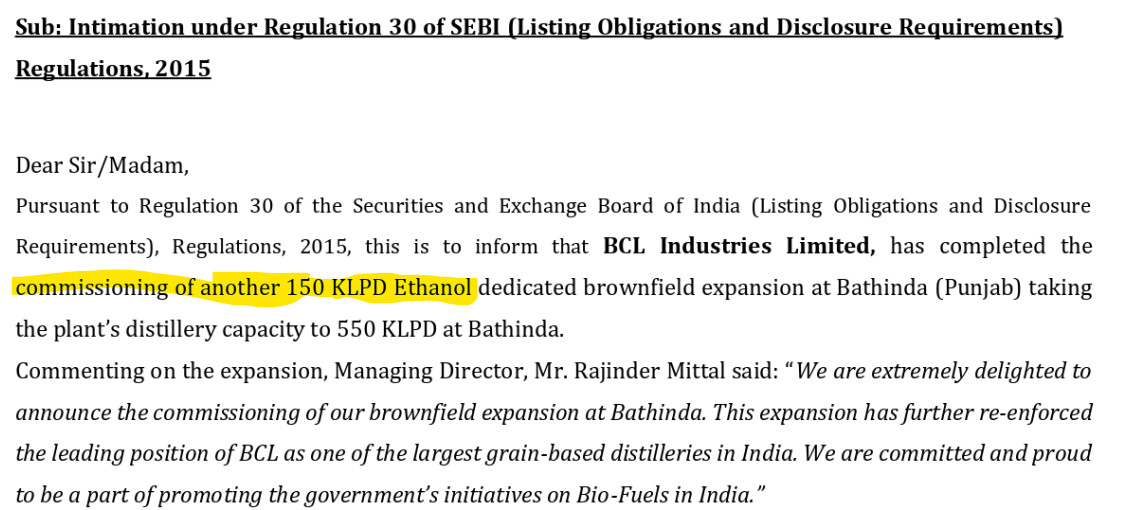
It’s very unlikely to utilize the upcoming 150 KLPD facility effectively
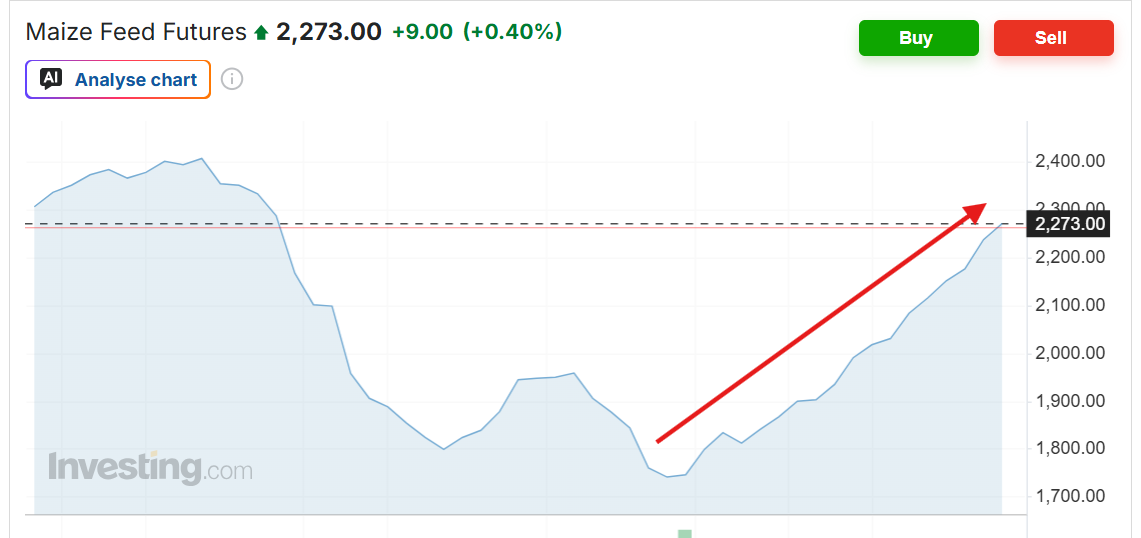
Things happened as expected, price corrected 20% from Nov.
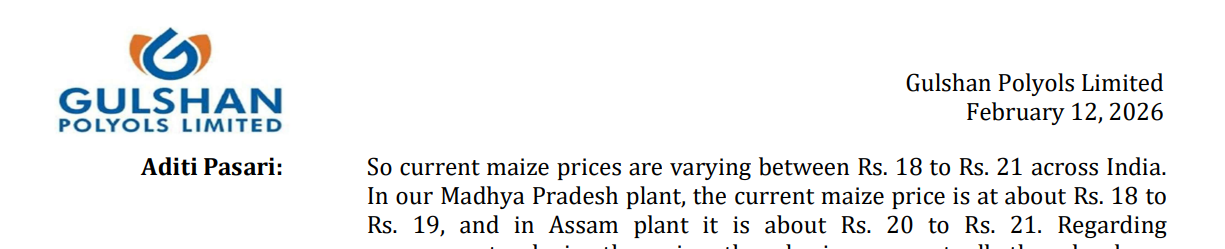
ENA production pulling down margins and Sales aswell. Even though Maize is available at 18-19/- BCL is not getting the mazie at this rate, during earning call management told that 20-21/- is the avg procurement price.
Same is applicable to gulshan poly aswell, but they are getting maize at very low price for MP plant.
Now live prices are below 17/-, if these levels sustain for few months then ethanol makers can make good margins. There will some uptick in the bottom line due to lower maize prices, 150KLPD commissioning and 25% stake purchase in Svaksha distilleries.
Now valuations also very attractive in single digits PE multiples, one should consider policy framework risk always.
Any update?
Things looking very promising from a distance atleast
Q4 avg price of maize less than 20
Capacity of 900KLPD on track
Goyal acquisition on the cards
Low PE of 9
Govt filing draft towards E85 & E100
What are we missing?
E85 & E100 are not going to happen quickly, ethanol demnad would be sluggish in short to medium term and distillaries should divert capacity to ENA manfacturing, where realizations are on lower side as compared to ethanol.
Rather than E85 and E100, which would take time to get implemented and scale, the possible short-term catalyst to watch out for are:
Govt increasing the price at which they procure Biodiesel. BCL has ready plants, so there is operating leverage
Ramp-up of the new Liquor brands they have introduced, so that some of the ENA can be used in-house for a higher margin product
Further Management buying from open market
I have been a BCL shareholder since many years, I have stuck around because I liked how the Management thinks one step ahead of its competitors and is the most efficient player in the Ethanol sector. I also think Mr. Kushal Mittal is smart and can make BCL a far bigger company than it currently is. But some of the actions of the Management has left a sour taste which forced me to reduce my holding (from very large position to still substantial size for my PF).
Offloading the family’s 15% stake of Pioneer Industries to BCL Industries. There is absolutely no business rationale for BCL to hold ~20% stake in Pioneer unless there are plans for its listing, which Mgmt has not mentioned. They said it’s for operational synergy, which makes zero sense
Using the proceeds from the land sale for buy remaining 25% stake in Svaksha from the MD’s daughter’s company. Why now? You didn’t feel the need when the plant’s had enough Ethanol allocation. Now when there is risk of sub optimal utilization, you go ahead and use cash proceeds from land sale to buy the remaining stake.
Howsoever the Management may justify the above 2 transactions, the truth is they used the listed entity for cashing out their illiquid investments. Neither of the two is illegal, but in my opinion not minority shareholder friendly.
I have been long a fanboy of BCL, and written several posts in support of the company/Management, but have been disappointed by some of their actions offlate.
I hope the headwinds facing BCL - Biodiesel pricing, Ethanol under allocation gets resolved soon.
Don’t know how maize price increase and no additional allocation from OMC’s will turn for BCL after comissioning this additional 150 KLPD.
They may get some additional allocations on account of 150 KLPD but still they would be short of ethanol orders and need to produce ENA (Low price) to utilize the capacity.
Additional 25% stake purchase in Svaksha & 150 KLPD commisioning would boost the numbers of Q2, but need to watchout margins.
“Adding to investor concerns, the company and its Managing Director settled adjudication proceedings with SEBI for alleged violations related to disclosure requirements and insider trading. Foreign Institutional Investor (FII) ownership materially decreased, signaling reduced institutional confidence in the company. Corporate governance issues have surfaced involving the company’s leadership.” This is from an analyst report about BCL Industries. Any idea about the SEBI violation?
BCL included in the Nifty Sugar & Ethanol Index with 6% weightage. This index bundles 15 listed sugar and ethanol companies into a single, tradable product.
True.
Grain Based Ethanol Capacity is 997 crores litres
Sugar based Ethanol capacity is 993 crores litres
Based on Niti Aayog roadmap , we need roughly 1300 crores Litres ( 1000 crores for E20, 300 crores for Industrial).
So excess capacity, FCI rice / Maize availability and OMs price intake of ethanol are uncrollable risk for any pure play ethanol company.