Arihant Foundations and Housing - tailwinds, deep pockets, integrity

Arihant Foundations (Screener), locally known as “Arihant Spaces” is a small-cap real-estate developer based in Chennai, expanding into Bangalore and Coimbatore. They are in a special situation right now which makes them stand out from the rest of the smaller R/E companies.

The current market cap is close to 1100cr, and the CMP is 1100 at the time of writing. The company has been in operation since 1986, and was incorporated in 1995.

I’ll cite:

  1. This livemint article: please Google “From Anna Salai to Dalal Street: How Arihant won Sacheti and Kela” (VP is not letting me post that link)
  2. This investor presentation: https://www.bseindia.com/xml-data/corpfiling/AttachHis/6d92c195-7736-4218-9eee-f982e80b5313.pdf

History of Integrity

Arihant stock went nowhere between 2007 and 2022. And there is a reason for it.

In 2008, Arihant partnered with Unitech to develop a residential township. Unitech was the 2nd largest developer in India at the time. As everyone knows, Unitech crashed and burned.

The Chennai market knew only us. Buyers had put in money because our name was associated with the development," said Arun Rajan, CEO of Arihant. “We took on the onus of completing the development on our own.”

So Arihant had to put in the entire investment of 800cr instead of just 50%. All surpluses from other projects were channelled towards the North Town development almost until its completion in 2020. Considering the scale of that project, Arihant could not pick up many other projects during that period, and their revenues suffered.

Arihant has a long history of delivering, even if it cost them money.

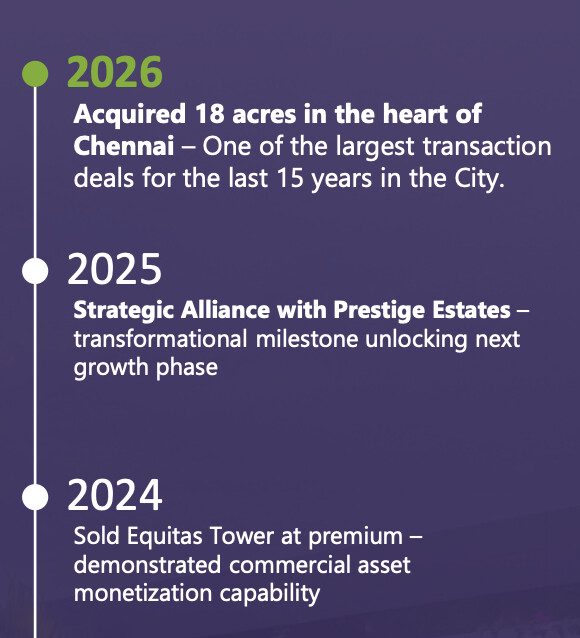
They have also partnered with JP Morgan, and Ashiana Housing in the past. And they have an ongoing partnership with Prestige Estates where they have already acquired two land parcels in prime Chennai areas.

Growth Runway

Since 2020, they picked up pace yet again, and have delivered more than 20mn sqft, with 50mn under active development. The GDV of the developments is around 6300cr, with Arihant’s share 3500cr. For context, their FY25 revenue was 206cr.

The GDV numbers don’t include a ~16 acre land parcel acquired via a JV with Prestige Estates for approx 550cr, in Jan 2026.

Their presentations keep mentioning “5x in 5 years” if that matters.

Tailwinds

Arihant is expanding into Bangalore, and other areas of Tamilnadu. Tamilnadu is at the center of India’s manufacturing boom, and the whole region (Andhra Pradesh, Telangana, Karanataka) is developing into an Industrial powerhouse. The recent HSR announcements are another signal that the boom will continue and may even gather pace.

In CY2025, while the RE market of the rest of country either de-grew or grew by 1-2%, Chennai’s RE growth surpassed all major cities.

Chennai has long underdelivered on its promise as a metro city, and that seems to be changing with a lot of recent reforms, and infrastructure building.

Deep Pockets

This is the key part.

The biggest problem RE players have is land acquisition. That was solved for Arihant, when Mithun Sacheti, the CaratLane founder who got a 4300cr exit with Tata, decided to join hands with Arihant.

“Every city has a giant real estate player. DLF in Delhi, Lodha in Mumbai, Prestige and Brigade in Bangalore. There is a vacuum in the premium space in Chennai, with no other listed player," said Sacheti. “The peculiarity of the market is such that local knowledge is very important, so I was keen on partnering with a Chennai company," he added.

Sacheti further said that he realised the brand was bigger than Arihant’s actual size. The raw material—capital in this case, plus land—was the missing ingredient.

The Sacheti brothers, with Madhusudan Kela’s Lotus Family Trust, acquired a stake in Arihant. They now collectively own more than 21% of the company. Madhu Kela’s Singularity Equity Fund also owns a stake.

The Sacheti brothers also formed a commercial platform with the Freshworks co-founder and former CEO Girish Mathrubootham. Arihant identifies prime land parcels and investors put in money to acquire them, allowing for a more proactive co-development model. They have already deployed ₹230 crore under this model.

The pockets are so deep that Arihant was able to bid for a 1100cr land parcel, that they missed by a whisker.

And then they acquired two different land parcels in prime Chennai areas in partnership with Prestige Estates (announced on exchanges by both companies)

Competition and other risks

There are much larger local Chennai players like Baasyam and Casagrand, and they can eat into Arihant’s pie. Bigger players like Godrej and Brigade are also now active in Chennai. However, what they lack is the deep pockets that Arihant now has. And a large company like Prestige (among the best R/E players in India) is choosing to partner with Arihant, instead of competing with them in Chennai/TN.

As with any real estate company, there is always going to be a real-estate-cycle risk, and execution risk. The recent tariff issues, and the AI led job-cuts may affect people’s ability to purchase expensive homes. And a long drawn down-cycle in real-estate may affect all players. However, considering a the tailwinds, ease of acquiring land, and the execution capabilities of the promoters, these risks seem very low over the long-term.

The biggest risk is that the commercial partnership (Sachetis, Madhu Kela, Mathrubootham) backing Arihant may break down. That said, the parnets have all shown deep skin-in-the-game so far, with their significant stakes (in a low-liquidity stock), and commercial platform purchasing lands worth hundreds of crores.

Investment Thesis

An old, well-known Chennai R/E player with very deep pockets to acquire land, a history of execution with integrity, 5+ years revenue visibility, partnerships with large players like Prestige and JP Morgan, and structural tailwinds, available at a reasonable valuation.

Disclosure: holding and biased, with a view to hold for 5-10 years unless something changes in the thesis (no recommendation, not SEBI registered).
3 Likes

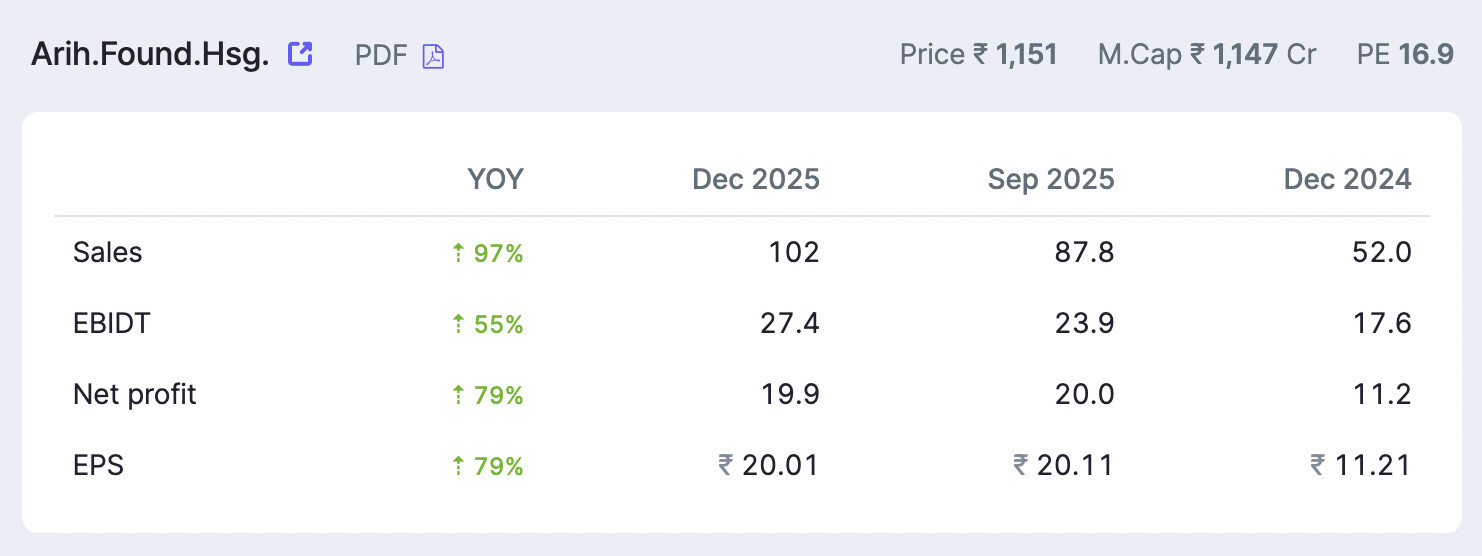
Q3-FY2026 results

GDV increased by another 500cr during the quarter:

We successfully announced and launched two marquee developments in Chennai’s Central Business District at Boat Club and Kilpauk, together carrying an estimated Gross Development Value of approximately INR 500 crore. These projects a premium office development and a luxury residential offering

Exchange filing of the results: https://www.bseindia.com/xml-data/corpfiling/AttachLive/3e9c1d03-3079-4fa4-ac9c-9b3d5271671d.pdf

5000cr GDV announced with Prestige Estates JV - March 26, 2026 announcement

Prestige Group, one of India’s leading real estate developers, and Arihant Group, a reputed Chennai-based real estate company, have jointly acquired a prime 16.331 acre land parcel in Padi, Chennai. The acquisition has been undertaken through Canopy Living LLP, a joint venture between Prestige Estates Projects Limited and Arihant Foundations and Housing Ltd

The land parcel is proposed to be developed into a premium residential project with a total saleable area of about 3.6 million square feet and an estimated revenue potential of approximately ₹5,000 crore.

Assuming 50% share in the JV, Arihant’s GDV should now stand around 6000cr

Operational Update for Q4-FY2026, and FY26

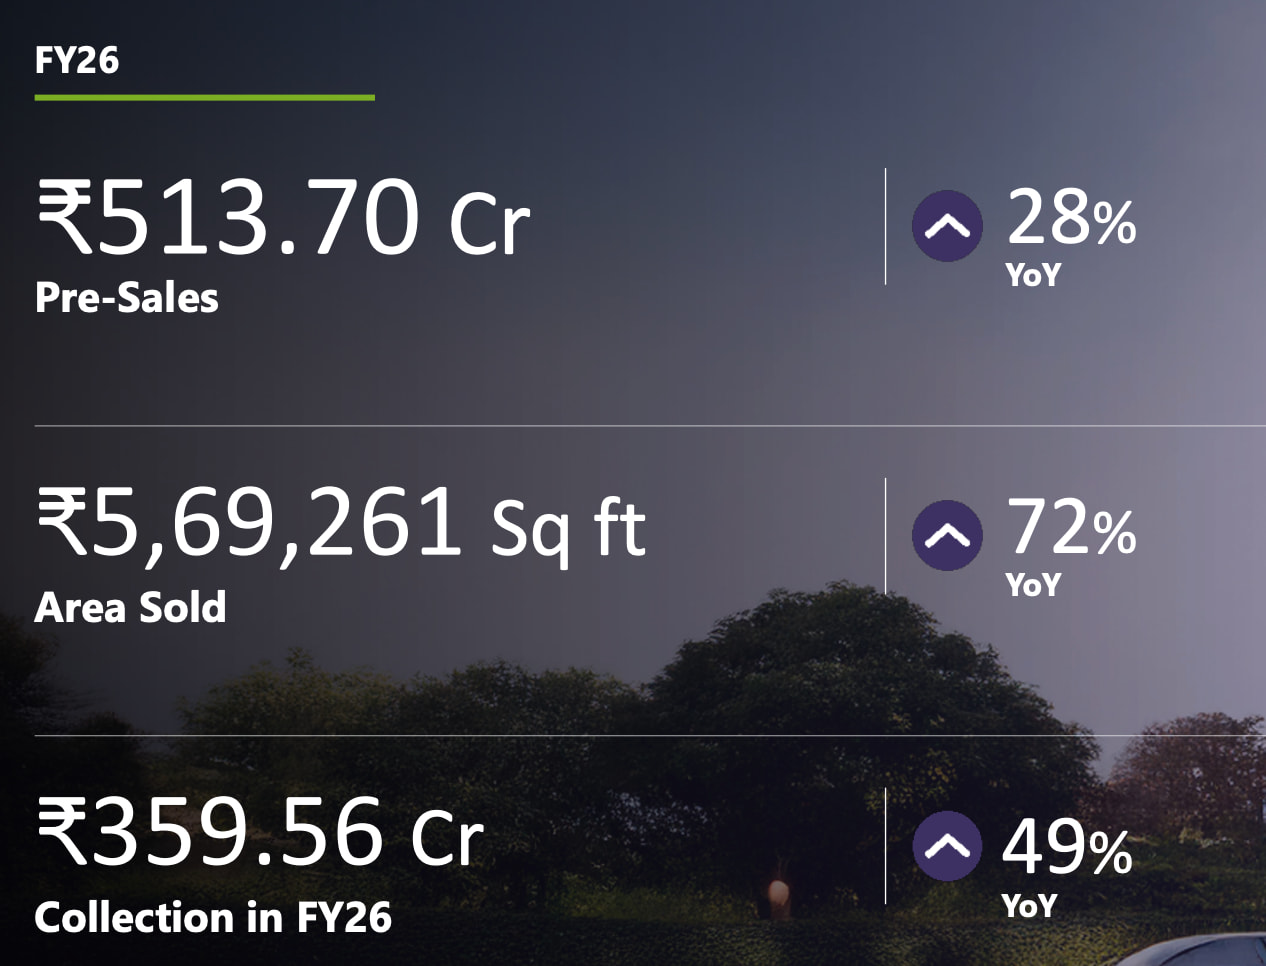
  • Highest Ever Pre-Sales of ₹513.70 Cr in FY26 – up 28% YoY
  • Total Area Sold of 5,69,261 sq. ft in FY26 (115% YoY)
  • Collections of ₹359.56 Cr recorded for FY26
  • Q4FY26 Pre-Sales at ₹183.30 Cr – up 46% QoQ and 15% YoY
  • Ongoing project portfolio commands a GDV exceeding ₹11,250 Cr across 8 Million sq. ft

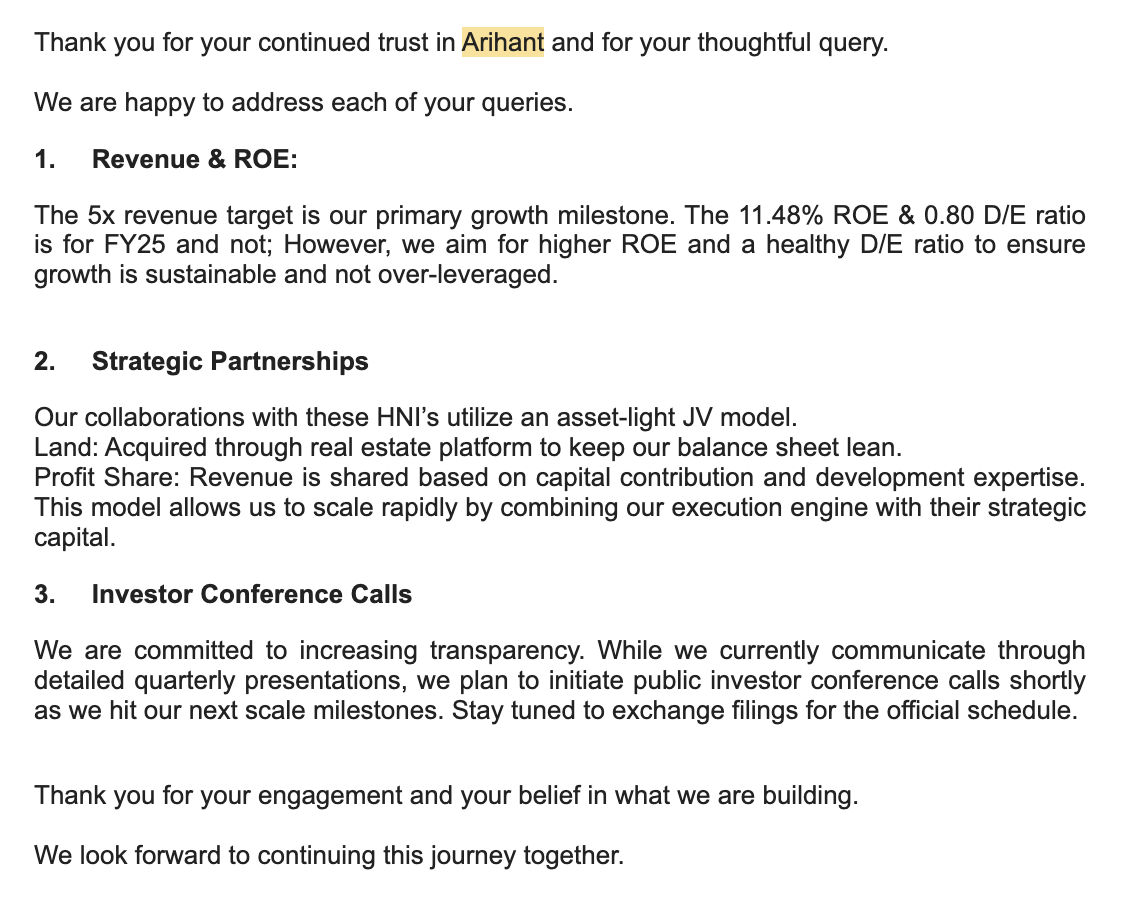
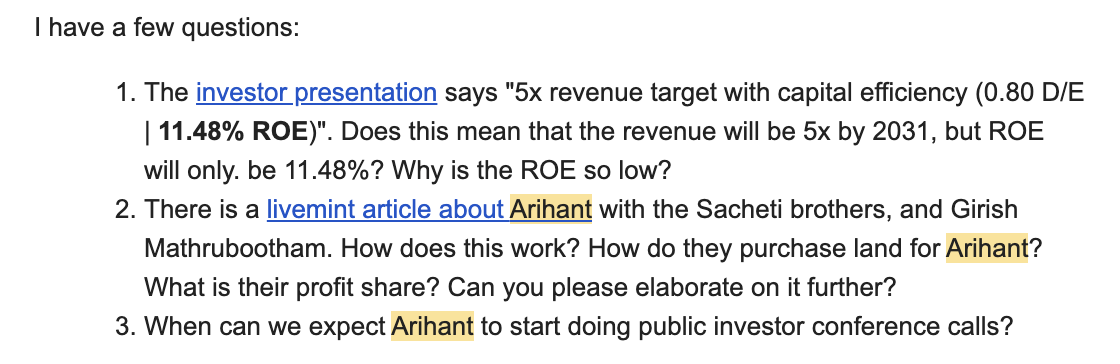
My email to them

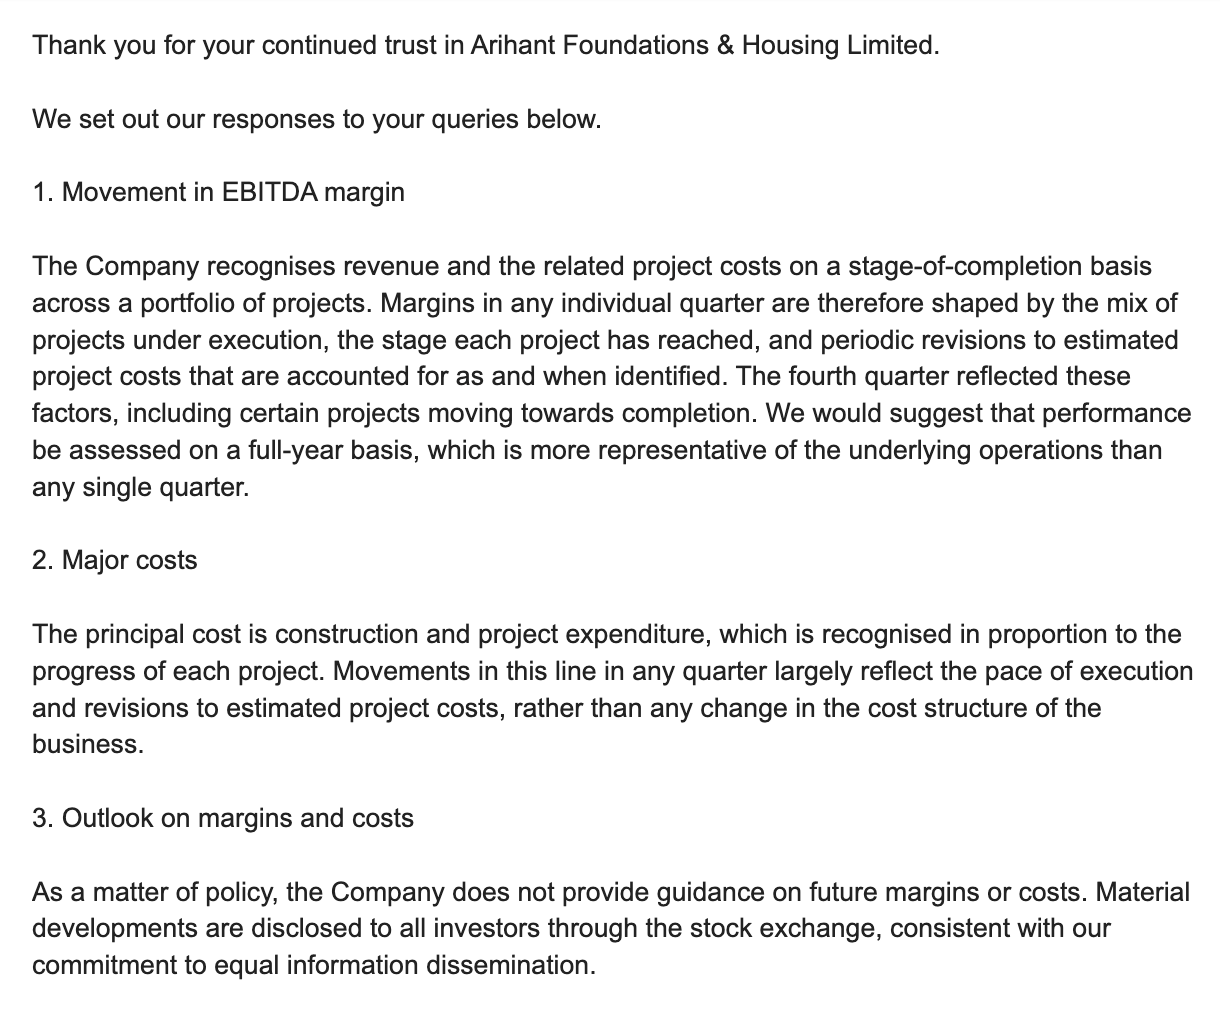
And the reply

1 Like

Q4-FY2026 investor presentation. Some highlights below

Does anybody know why degrowth happened you in q4. Is it one time or structurally is there any problem?

The company hasn’t disclosed anything officially, but I have been following several companies from the real-estate sector, and all I can offer from having looked at their results for a while is: revenue and cost recognition in real-estate sector is quite lumpy and a little unpredictable.

Additionally, for high-growth companies, a lot of costs related to ongoing projects get recognized without the corresponding revenues getting recognized. Quarterly margins can be misleading.

If you want some reassurance, check out the quarterly results for all the bigger listed players like Godrej Properties, Signature Global, DLF etc. The question about margins is also pretty common for them (especially Godrej and Signature have addressed the questions multiple times).

So, to answer your question, my judgement is that this is not structural.

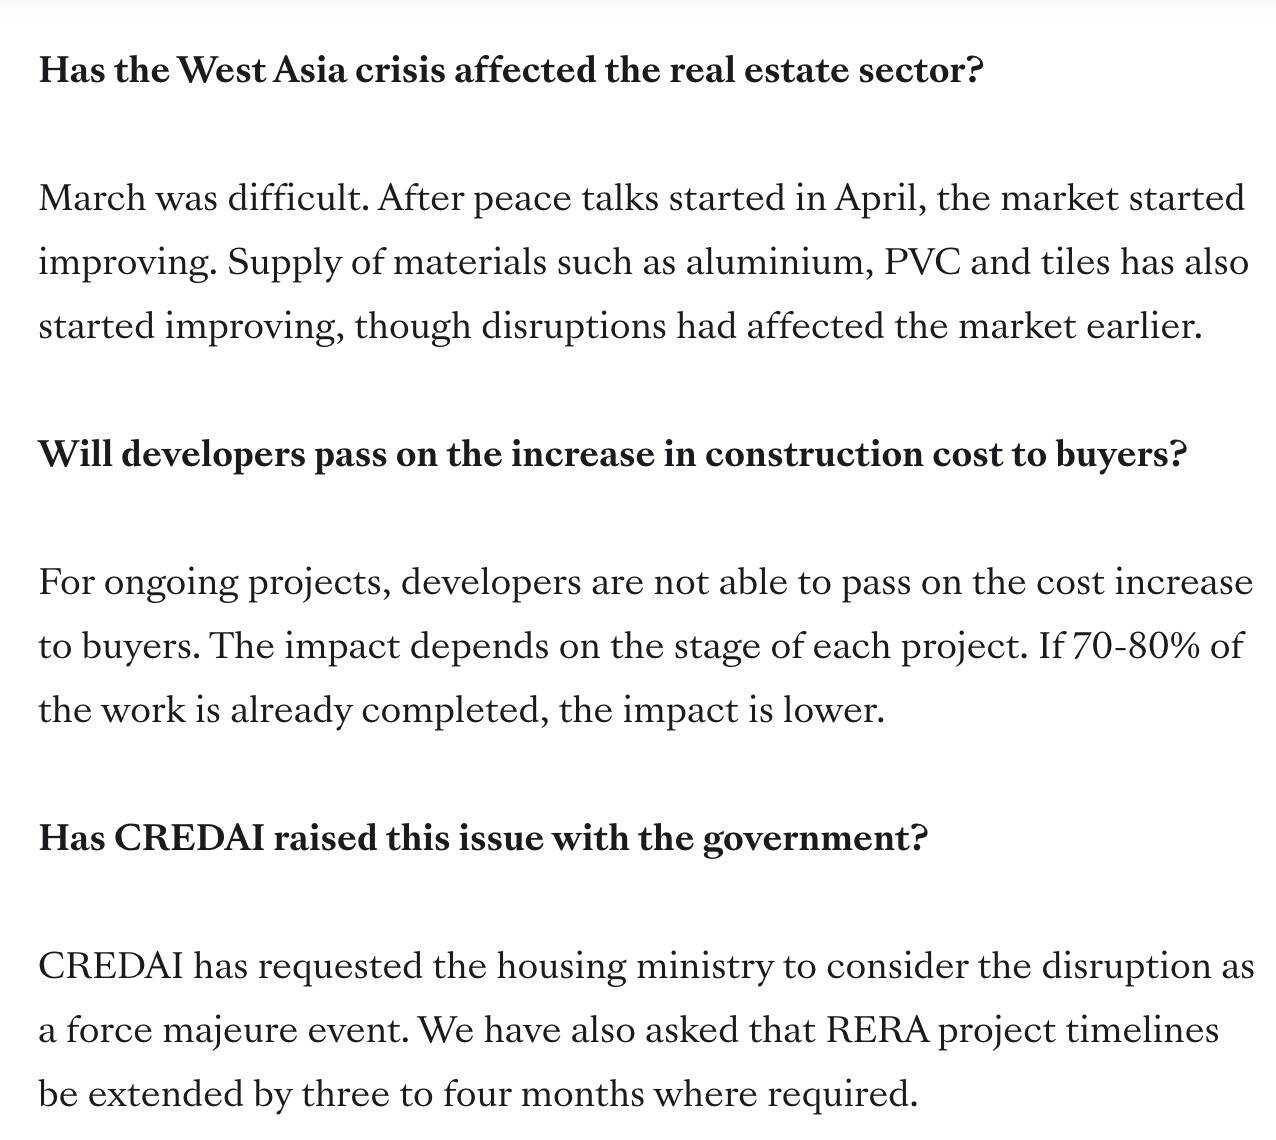
Additionally, several companies disclosed increased raw-material costs due to the Iran war, and because of RERA rules, they cannot pass on these costs to consumers, at least for the projects that have been ongoing for a while. I expect at least part of the margin impact is coming from this (see the following from an interview by CREDAI national president. I’ve seen similar notes from multiple real-estate players con-calls (e.g. Signature, Oberoi))

[Not investment advice, No recommendation]

1 Like

Update on June 8, 2026 (official email reply)

I had sent them an email after the results, inquiring about margins (just to make sure my hunch was correct). They replied, and basically said the same thing I said in my previous reply

91springboard has signed 165,000 sq ft across Arihant Vayu/Vaayu - Perungudi and Arihant Ventura - Ekkatuthangal, adding more than 3,000 seats in Chennai.

There were recent public transactions in these areas by other flex-space operators like Indiqube, WeWork, and others. Based on known peer numbers, the annual rent could be anywhere between 13 to 20 crores for this deal. The commercial rental income can have 80-90% EBITDA margins. So, this can add approx 8 to 18 crores of PAT for Arihant. Which is 14% to 25% of their FY2026 full-year PAT approximately.

  1. https://www.91springboard.com/co-working-office-space-chennai/arihant-vaayu-omr/
  2. https://www.91springboard.com/co-working-office-space-chennai/a-v-staging/

[not a recommendation]

Land acquired. Total GDV now 11550 crores, with Arihant’s share at 6300 crores.

announced the outright acquisition of a prime land parcel measuring over half an acre on Mount Road (Anna Salai), in the heart of the city’s central business district and adjacent to the Hyatt Regency Chennai.

The Company plans to develop a boutique Grade A commercial office project on the site, with an estimated Gross Development Value of ₹300 crore.

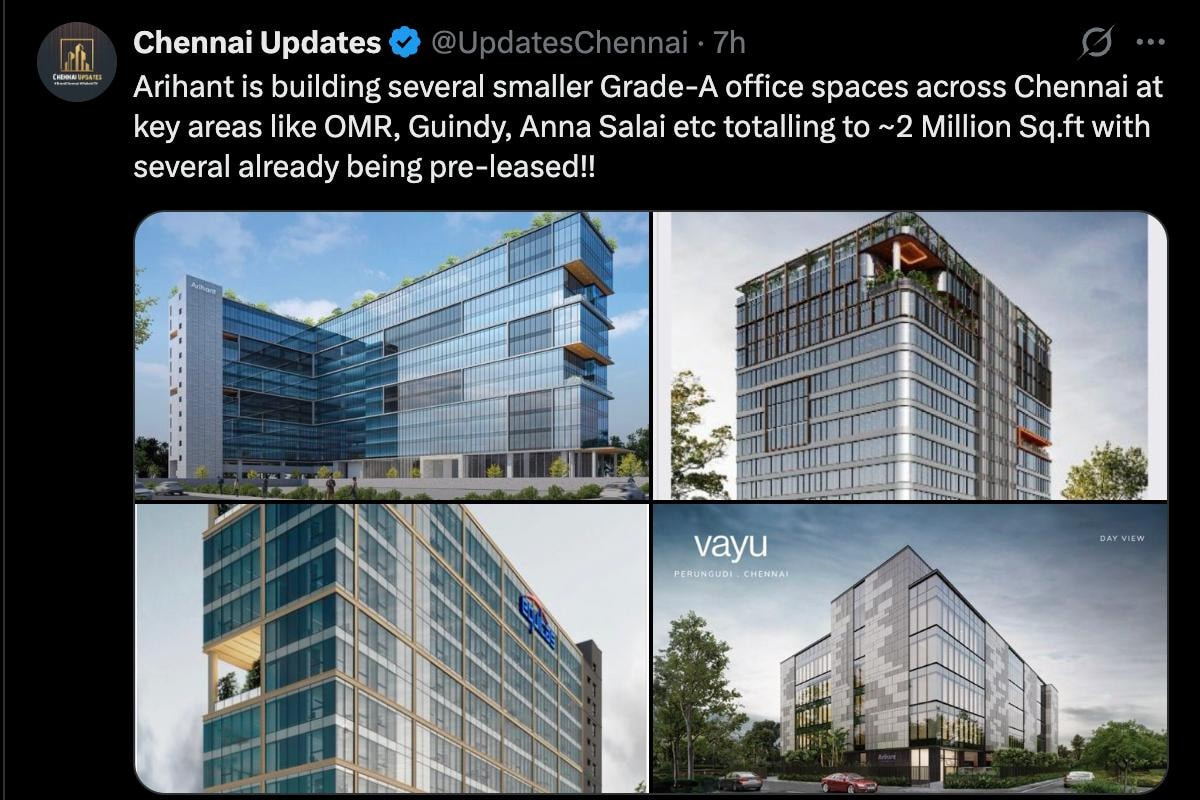
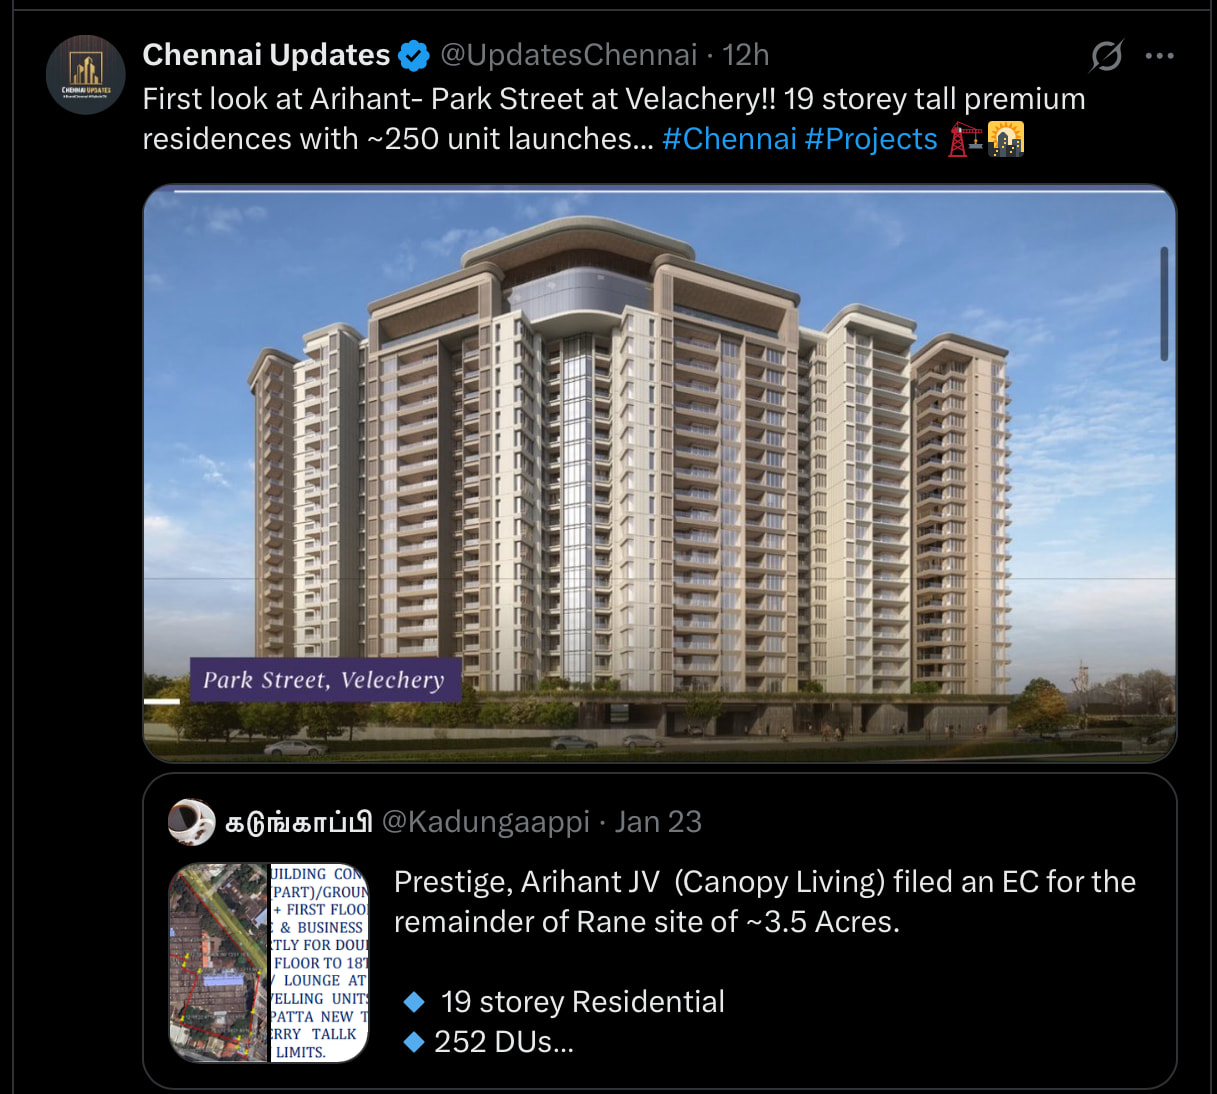
Some updates with pictures

Things progressing well, along with the Prestige JV.

Thanks @Bhashit_Parikh for starting this thread and diligently updating it.

Just a few questions on the rental numbers you mentioned above:

  • Is the estimated annual rent numbers of 13-20 crores gross or Arihant’s share of the rent?
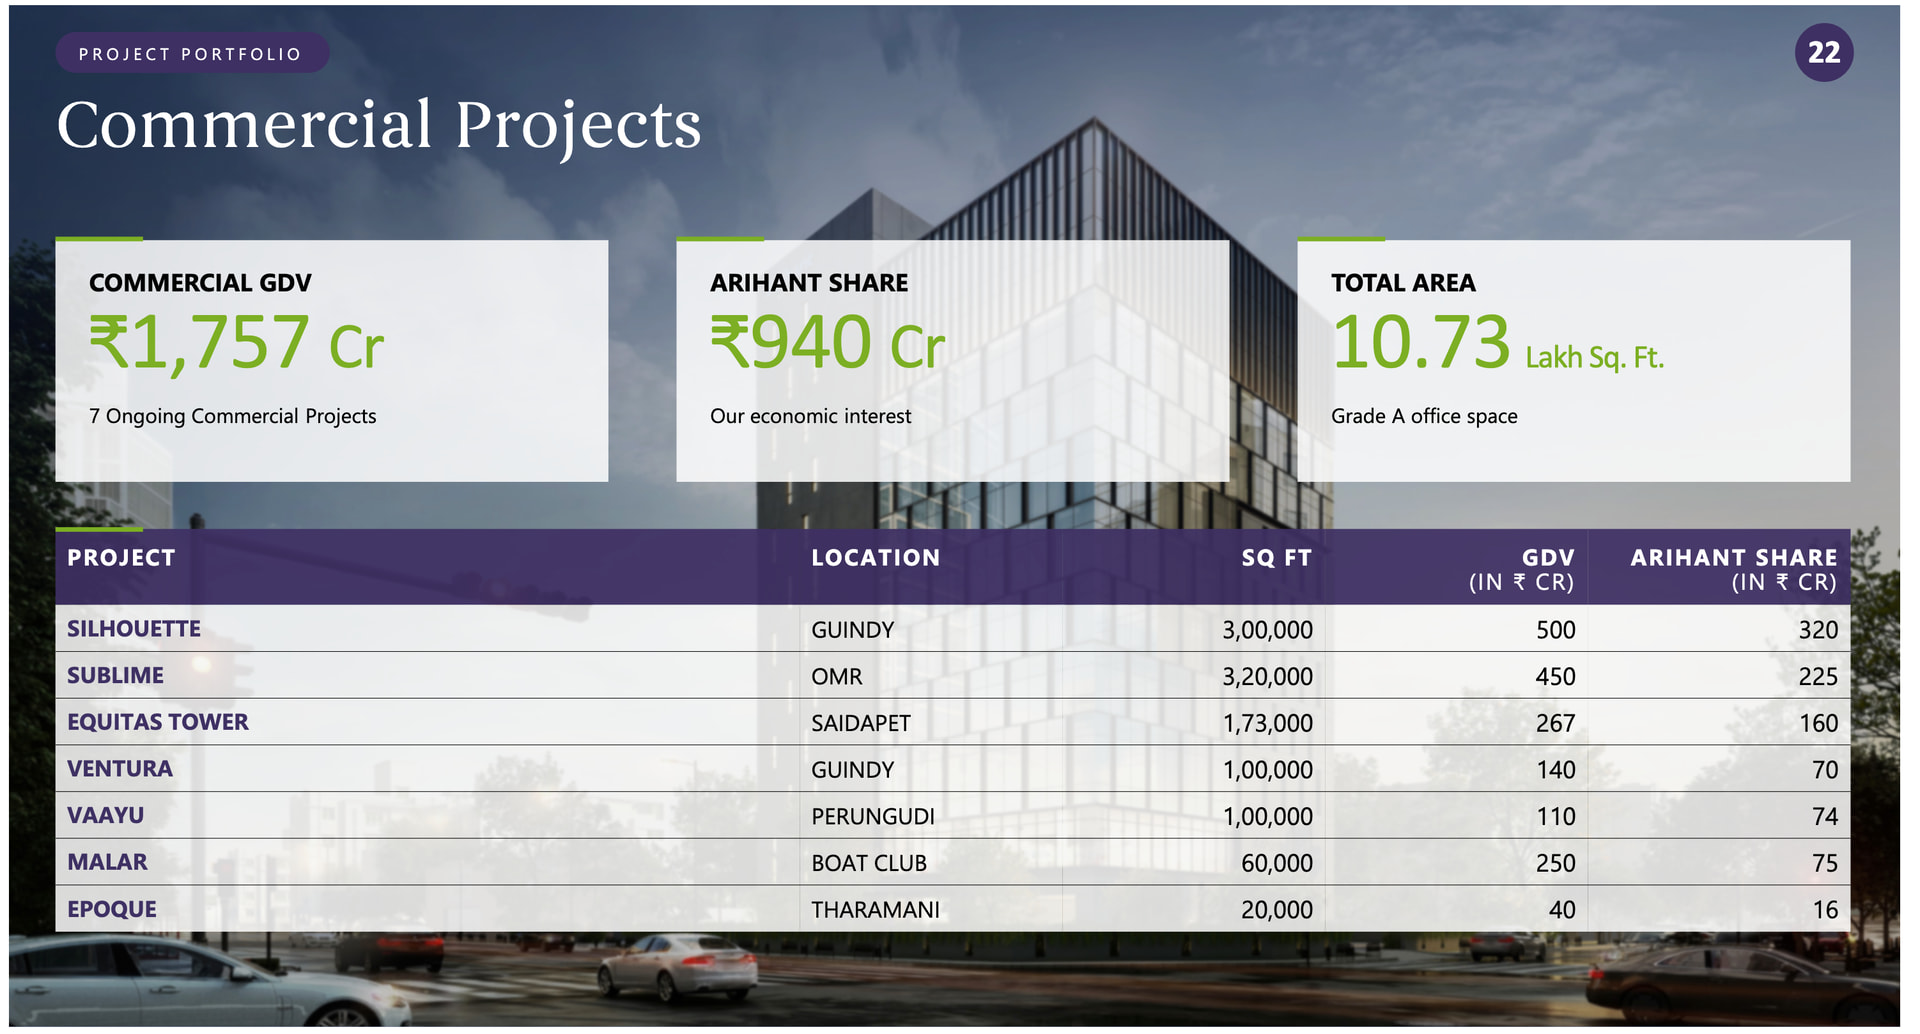
  • The June ‘26 investor deck has the following slide on their commercial projects:

  • Do you know what would GDV mean for a commercial rental asset in the above list of assets?Out of the above, “Equitas Tower” is probably one time sale to Equitas and will not yield recurring rentals (Source). However, it’s not clear to me what GDV would mean for Ventura and Vaayu that have been leased for rentals.

Is the estimated annual rent numbers of 13-20 crores gross or Arihant’s share of the rent?

Arihant’s share of the rental income: thank you for pointing this out. In my excitement, I only did a surface level estimate. Assuming Arihant’s interest at about 60% for (Vaayu + Ventura), the rental revenue comes down to somewhere between ~8 to ~12 crores annualized. PAT between ~5 and ~7 crores.

Do you know what would GDV mean for a commercial rental asset in the above list of assets?Out of the above, “Equitas Tower” is probably one time sale to Equitas and will not yield recurring rentals (See here). However, it’s not clear to me what GDV would mean for Ventura and Vaayu that have been leased for rentals.

I’m not sure how rental income translates to GDV.

Let me send them an email and see if they can clarify anything here. I’ll share the answer if they reply.

1 Like

Assuming Arihant’s interest at about 60% for (Vaayu + Ventura), the rental revenue comes down to somewhere between ~8 to ~12 crores annualized. PAT between ~5 and ~7 crores.

Cool, thanks for clarifying. It also appears that this is a pre-lease and that at least Ventura will get completed in 2027 (Source). Therefore, these numbers may show up in FY28.

Let me send them an email and see if they can clarify anything here. I’ll share the answer if they reply.

That would be great, thanks!

1 Like

PPFAS recently uploaded an educational video on listed real-estate developers. The snippet starting here is especially interesting for Arihant, since it matches my investment thesis on Chennai: transcript below with a minor correction.

So, why is Bangalore real-estate really big? Because Bangalore is the fastest growing commercial market, where YoY we do net leasing of between 11 and 13 million sqft of net leasing. And people who work in Bangalore, eventually buy homes in Bangalore

After the Telangana state government was formed, Hyderabad became big. Hyderabad real-estate is now bigger than Bangalore, because, in the last 5 years, they have also done more than 10 million sqft [of commercial space net-leasing]

The third city to now hit 10 million sqft of yearly leasing is Chennai. Which means, anybody who is developing projects in Chennai will do good because a lot of people who are getting employed there will want to [buy a home] , and which is why Residential in Chennai now will grow.

What happened in Bangalore, Pune, Hyderabad - I think Chennai is next

This argument is explained in detail in the earlier part of the video. It may be summarized as “commercial growth is a leading indicator for residential growth”

In general, the video is a great way to learn to evaluate real-estate companies in India.

And Arihant is in the bottom right corner here:


Maybe worth noting: the presenter leads the real-assets investment team at MK Ventures, which is Madhu Kela’s company. And Kela is invested in Arihant as a stock-holder (via Barclays Wealth Trustees), and also via the commercial partnership that buys land on behalf of Arihant

[Disc: invested, biased. Not investment advice. No buy/sell recommendation]

A couple of notes from following the Chennai RE market.

https://newstodaynet.com/2026/10/06/chennai-housing-sales-rise-2-in-2026-frank-india-rs-2-5-cr-segment-records-54-growth/

Chennai recorded 13,871 residential property sales during January-September 2026, registering a 2% year-on-year increase from 13,552 units during the corresponding period last year, according to Knight Frank India. The sales figure is the highest for the first nine months of any year since 2018. Developers launched 14,639 units during the period, 7% lower than the 15,793 units launched in 9M CY2025, indicating a measured approach to new supply.

Chennai witnessed a notable shift towards higher-value homes. Sales in the Rs 2-5 crore segment surged 54% year-on-year to 1,709 units, while the Rs 1-2 crore segment grew 17% to 3,808 units. Sales in the Rs 5-10 crore and Rs 10-20 crore segments rose 17% and 22%, respectively. Overall, sales of homes priced above Rs 1 crore increased 26% and accounted for 42% of total sales, up from 34% in the corresponding period last year.

https://cxotoday.com/media-coverage/coworking-largest-occupier-indias-office-market-records-43-mn-sft-leasing-in-9m-2026

Chennai saw absorption decline by 21% to 3.56 million sq. ft., even as new completions increased 9% to 3.8 million sq. ft. Average rentals rose 6% to INR 83 per sq. ft. per month, while vacancy remained relatively stable at 8.75%, compared with 8.9% in 9M 2025.

Chennai reported the lowest vacancy at 8.75%, followed by Bengaluru at 11% and Pune at 11.6%.

Average office rentals increased across all seven cities. Hyderabad led with 12% growth, followed by NCR at 10%, Bengaluru at 9% and MMR at 8%. Chennai, Pune and Kolkata each recorded rental increases of 6%