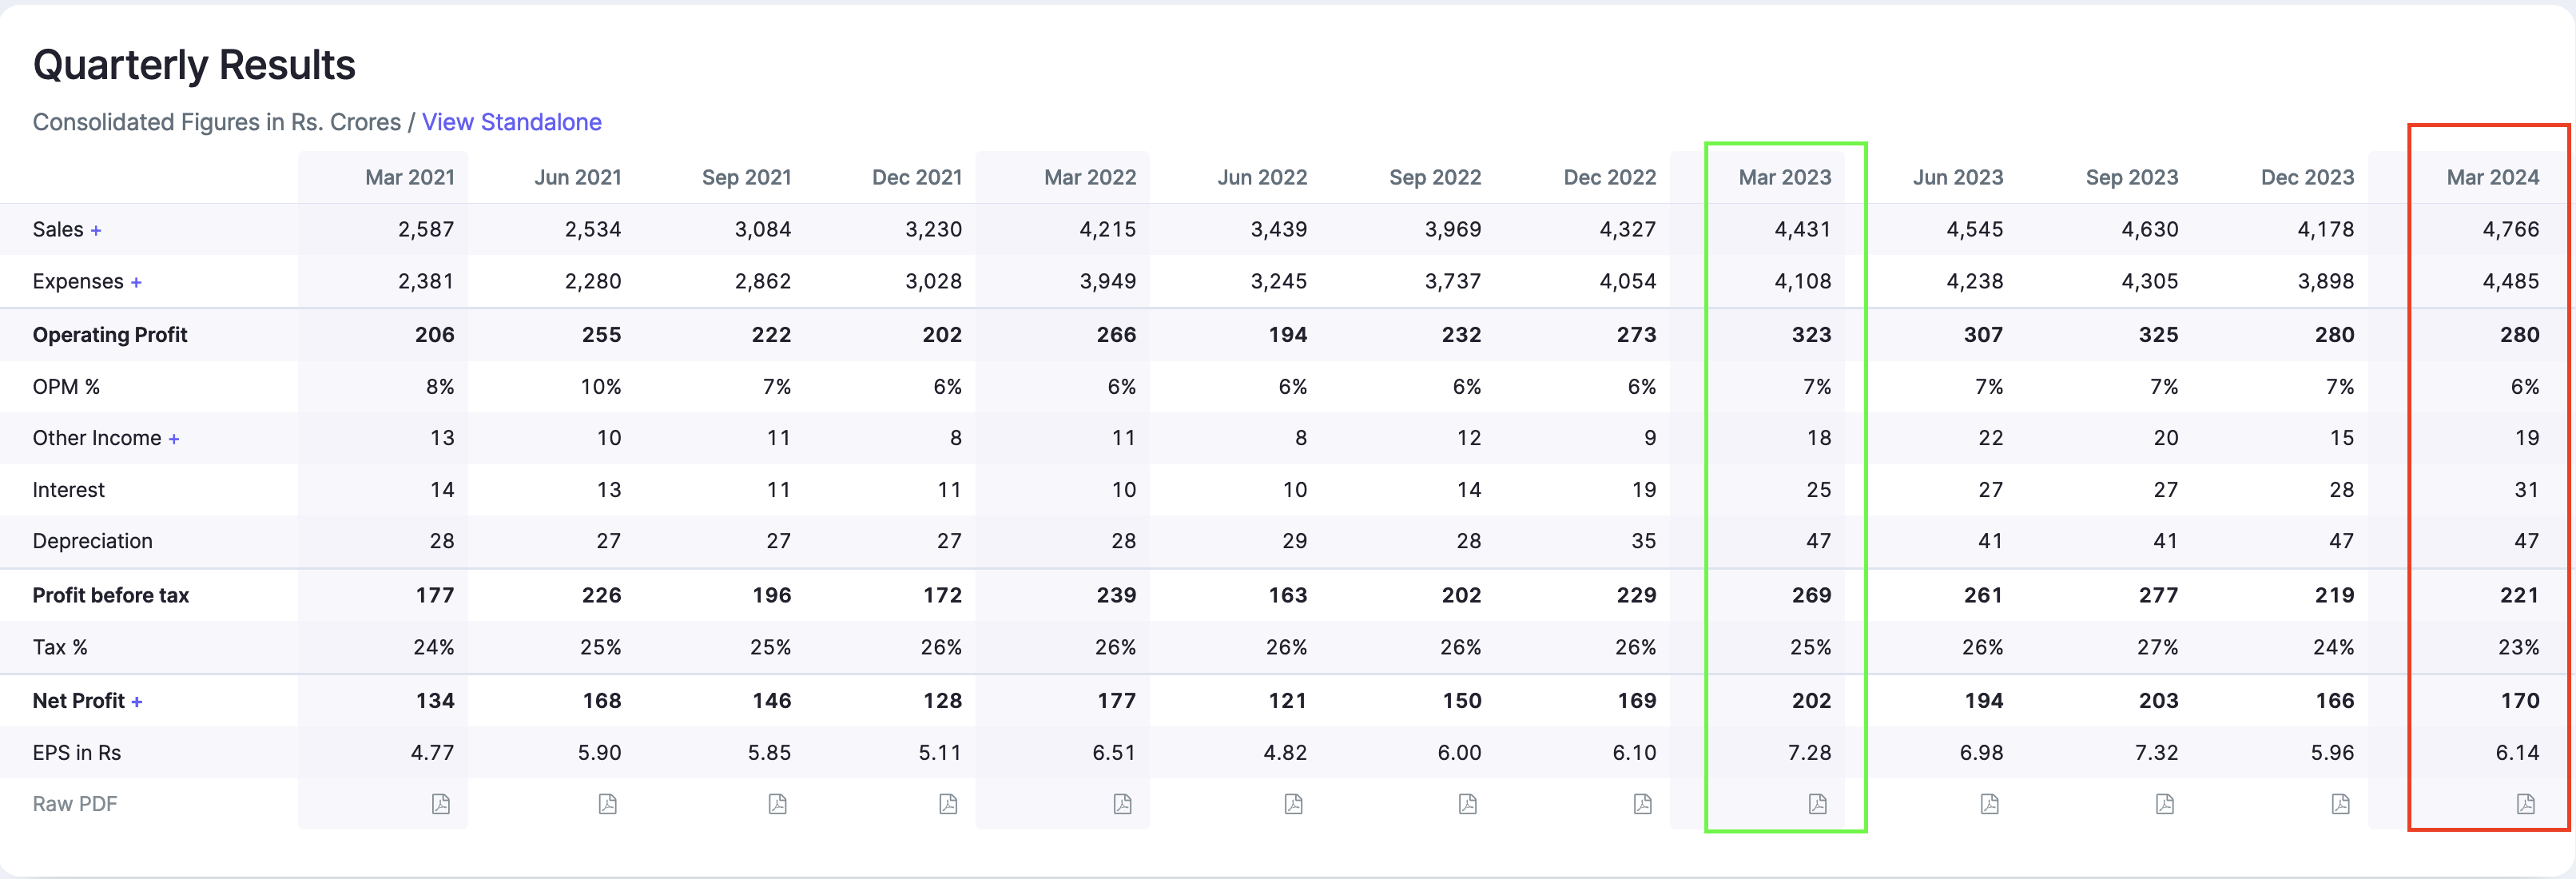
You need to look at seasonality - this is a business where you need to compare YoY and not QoQ.
- Raipur and Dubai impact will be visible in FY25. Volumes are very low in the larger picture, primarily due to capacity constraint.

I would compare YoY always and the actual revenue and EBITDA growth. If Steel prices are higher vs last year, they will also make more revenue/EBITDA.
1 Like
I may be wrong but if steel (their raw material) prices have decreased then their profit margin should be more.
Normally their 3rd quarter is always subdued and 4th quarter is always good. If this persists then this is the right time to accumulate more shares.
5 Likes
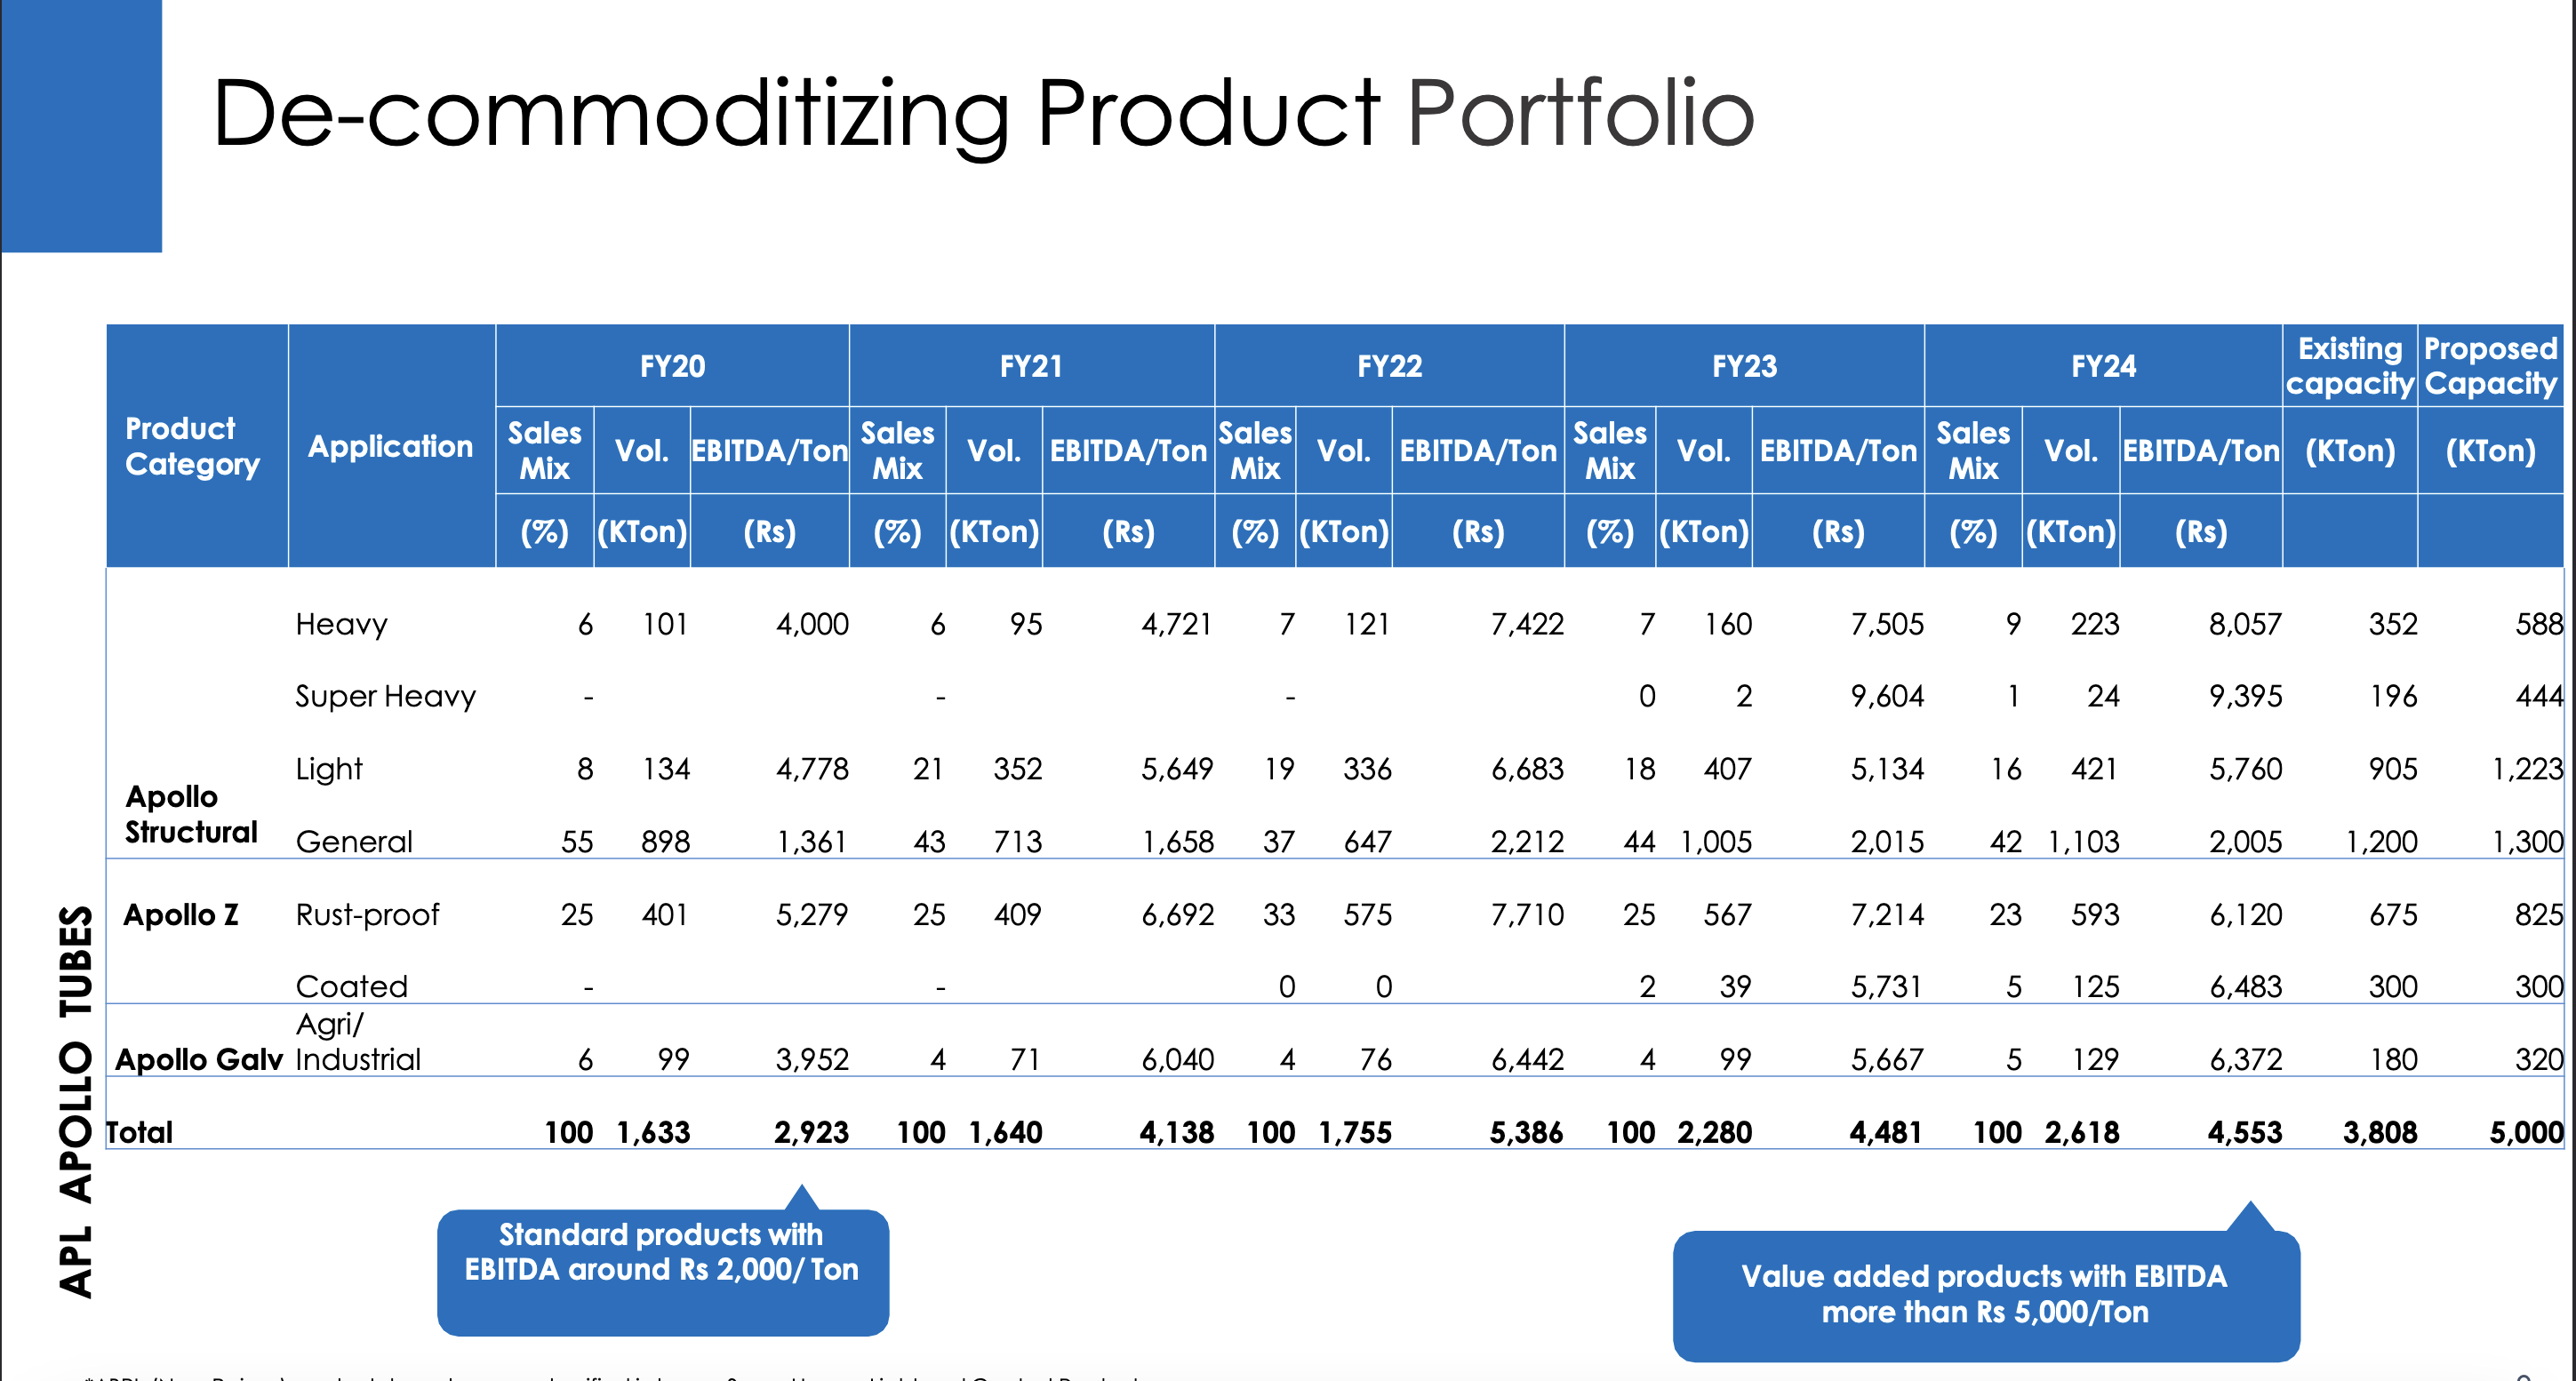
Assuming q3 ebitda/ton nos, should do a Q4 ebitda of 300-320 crs. 12% jump qoq. Value add at 60%

5 Likes
Results look flat. At 6% margin,only high double digit sales growth can push EPS. Although there are some discussions about “De-commoditizing Product Portfolio” but are have not started reflecting in OPM.
2 Likes
Thanks to all the contributors for updates for such a long time. I am just looking for some answers to some of the questions that I have in my mind about APL Apollo promoters. If you track the company one would find that there has been promoter selling and reducing their stake almost every quarter. If the business prospects are still very good as they project in quarterly calls, why would they reduce their holding to such low levels instead of holding or trying to acquire more. They are taking the capital from here and infusing into the NBFC that lends to APL Apollo tube customers. Is it a scheme to pump up the sales by financiing the buyers and push the stock price up and sell it at the same time while make the money safe by pushing it to NBFC which is a private entity? How long can this sustain? What happens when this credit facility is no longer available to distributors or dealers? Would they continue to buy? I understand that sometimes Promoters sell (like they did in Page industries while it was growing) but here it is of big proportions. Also, there seems to be a gap between what the promoters are telling about business and what they actually do to their stake in business. While everything else looks good, this aspect remains a red flag of mine and that is a reason I am looking for unbiased answers for the same.
9 Likes
APL has created significant wealth, i have personally benefited from it, imo, and whenever there are cyclical downturn or some issue with growth in business these thoughts do come in, but i feel the mgmt is competent and has created a strong business in an otherwise lacklustre sector. We should give it few qtrs to start delivering on what it has promised.
1 Like
Please note that public holding is also all time low while FIIs and DIIs increasing almost every quarter which also tells the different angle.
talking about promotor - understandable when such bull market phase attracts investment even good management gets tempted to cut stake for better return. Its on a cyclical downturn and would surely come out of it. if it faces some crash in prices then would be an opportunity to load.
2 Likes
What are the kind of products company manufactures? and applied where?
The company recorded highest ever sales volume of 828,200 Ton in Q3FY25 compared to 758,267 Ton in Q2FY25 (+9% QoQ) and 603,659 Ton in Q3FY24 (+37% YoY).Firing growth across all product categories.
1 Like
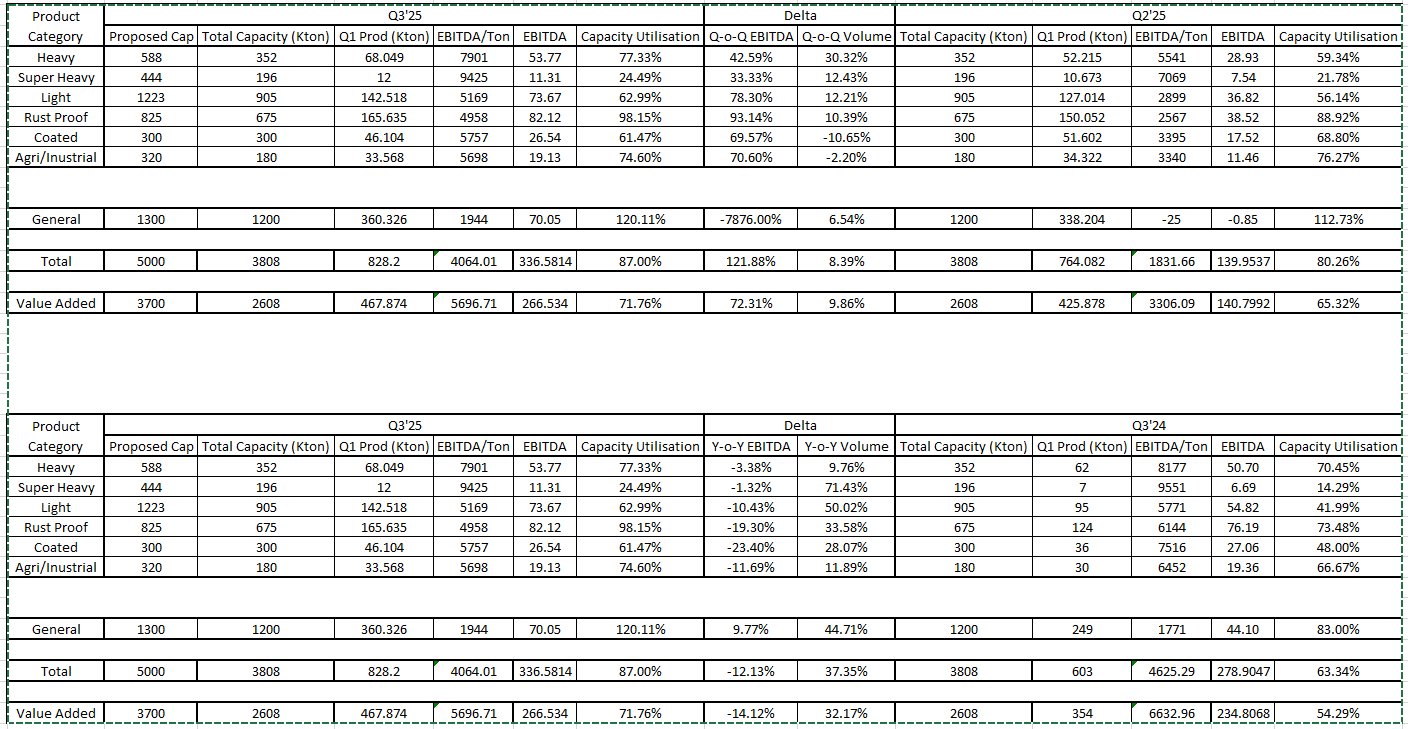
they have merged the heavy and super heavy segment to account for that ive just made some assumptions.
ive assumed Q1 ebitda/ton for Q3. That can be the baseline and we can draw conclusion based on our understanding of the mkt.
Management had guided for 4200-4300/ton of EBITDA in Q3 & 4800/ton in Q4.
1 Like
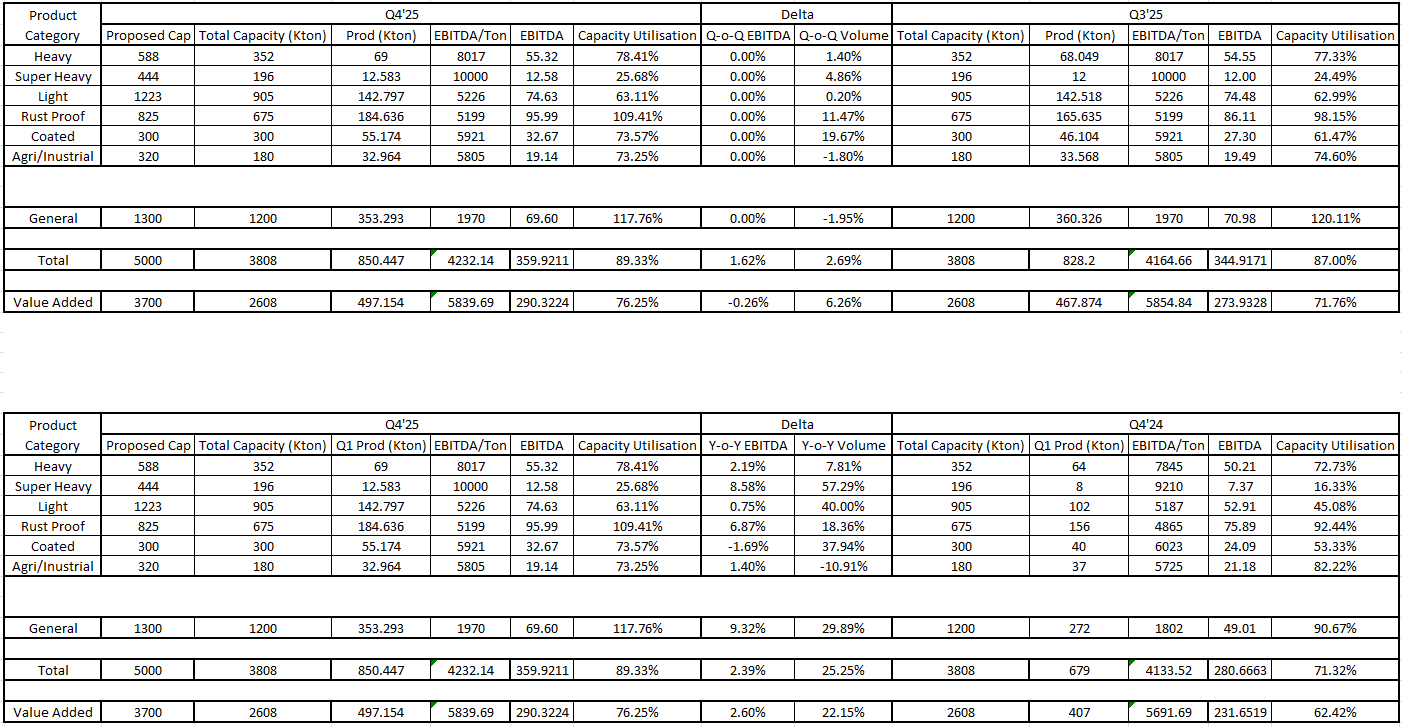
Value added portfolio has gone up slightly from 56.5% to 58.5% vs q3.
If the last qtr realisation is maintained then we can expect a EBITDA/T of 4232 vs 4165
However, my estimate is that we will see some inventory gains. EBITDA/T should be closer to 4350-4400.
6 Likes


Very Informative..Price to book is missing
1 Like
Management is confident of future growth, maintaining strong ROCE with additional demand drivers
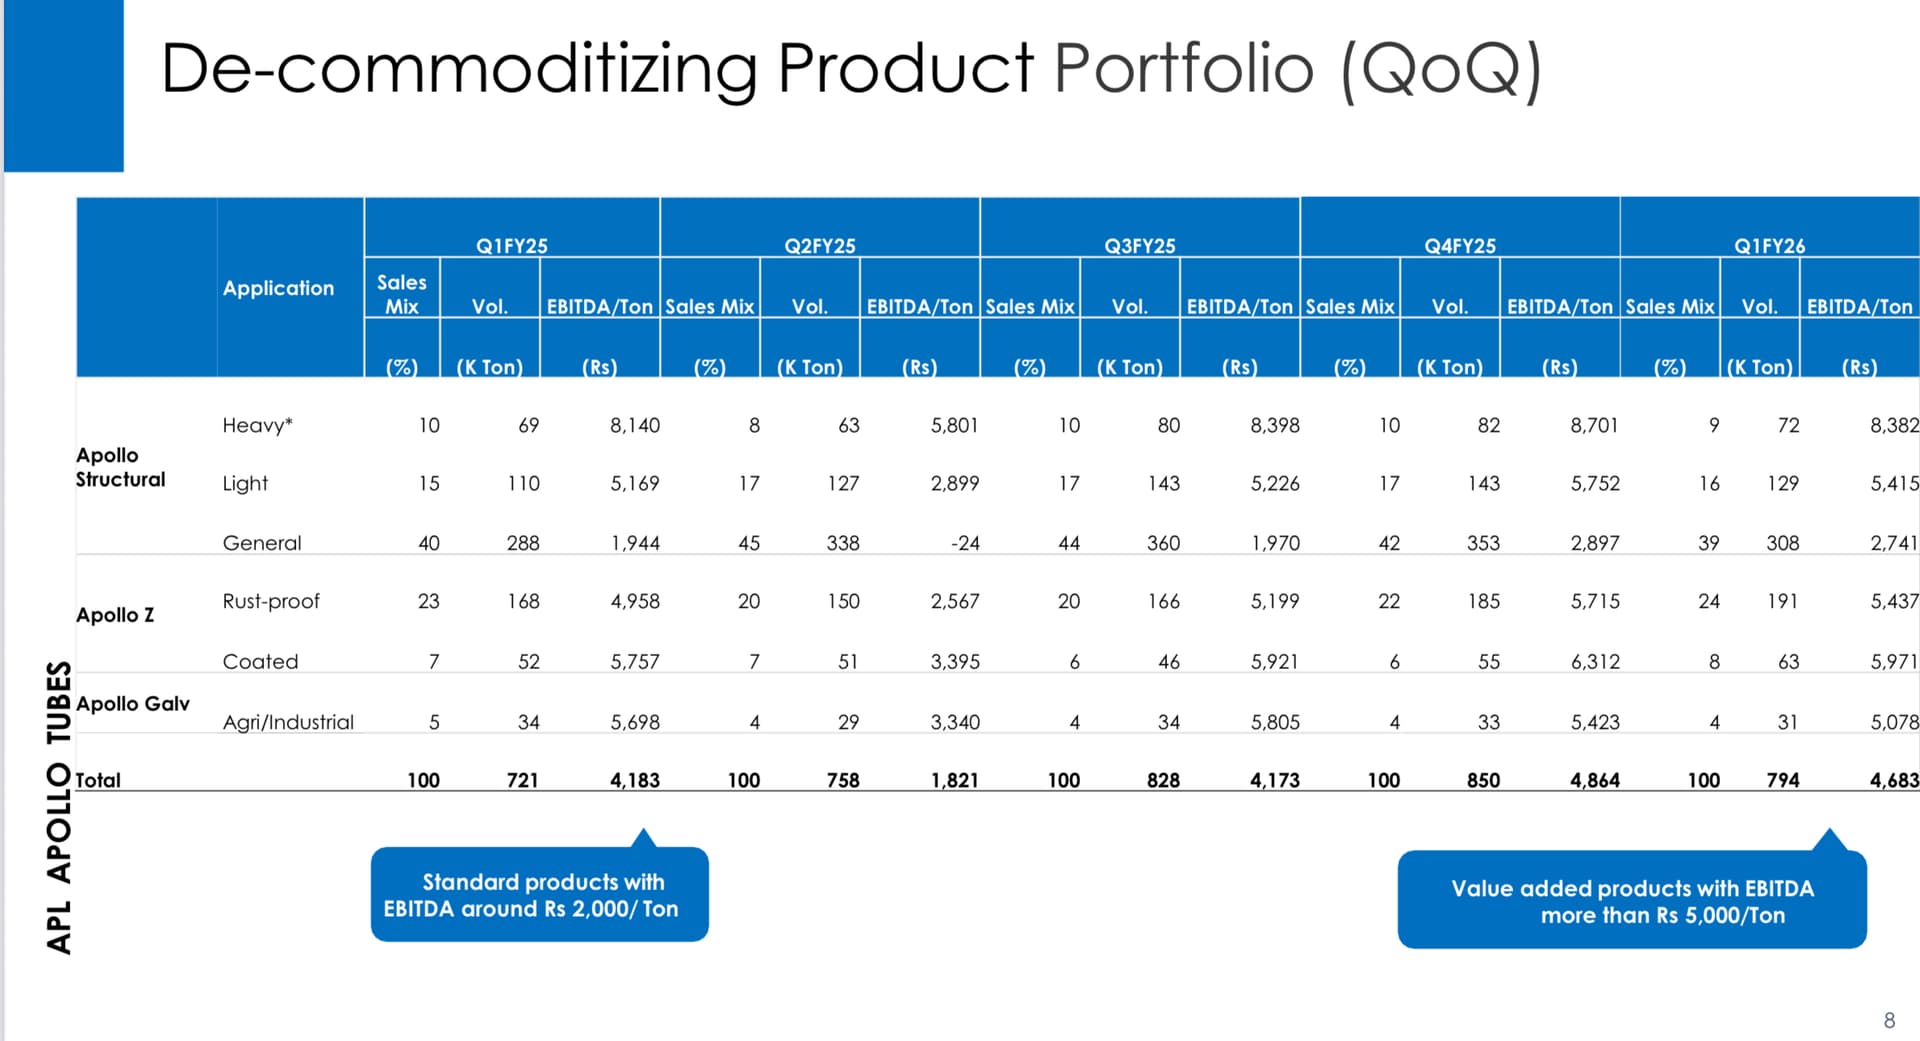
Consciously moving to a higher blended EBITDA/tonne, I think their commodity pack will continue to be vacated as higher margin opportunities expand
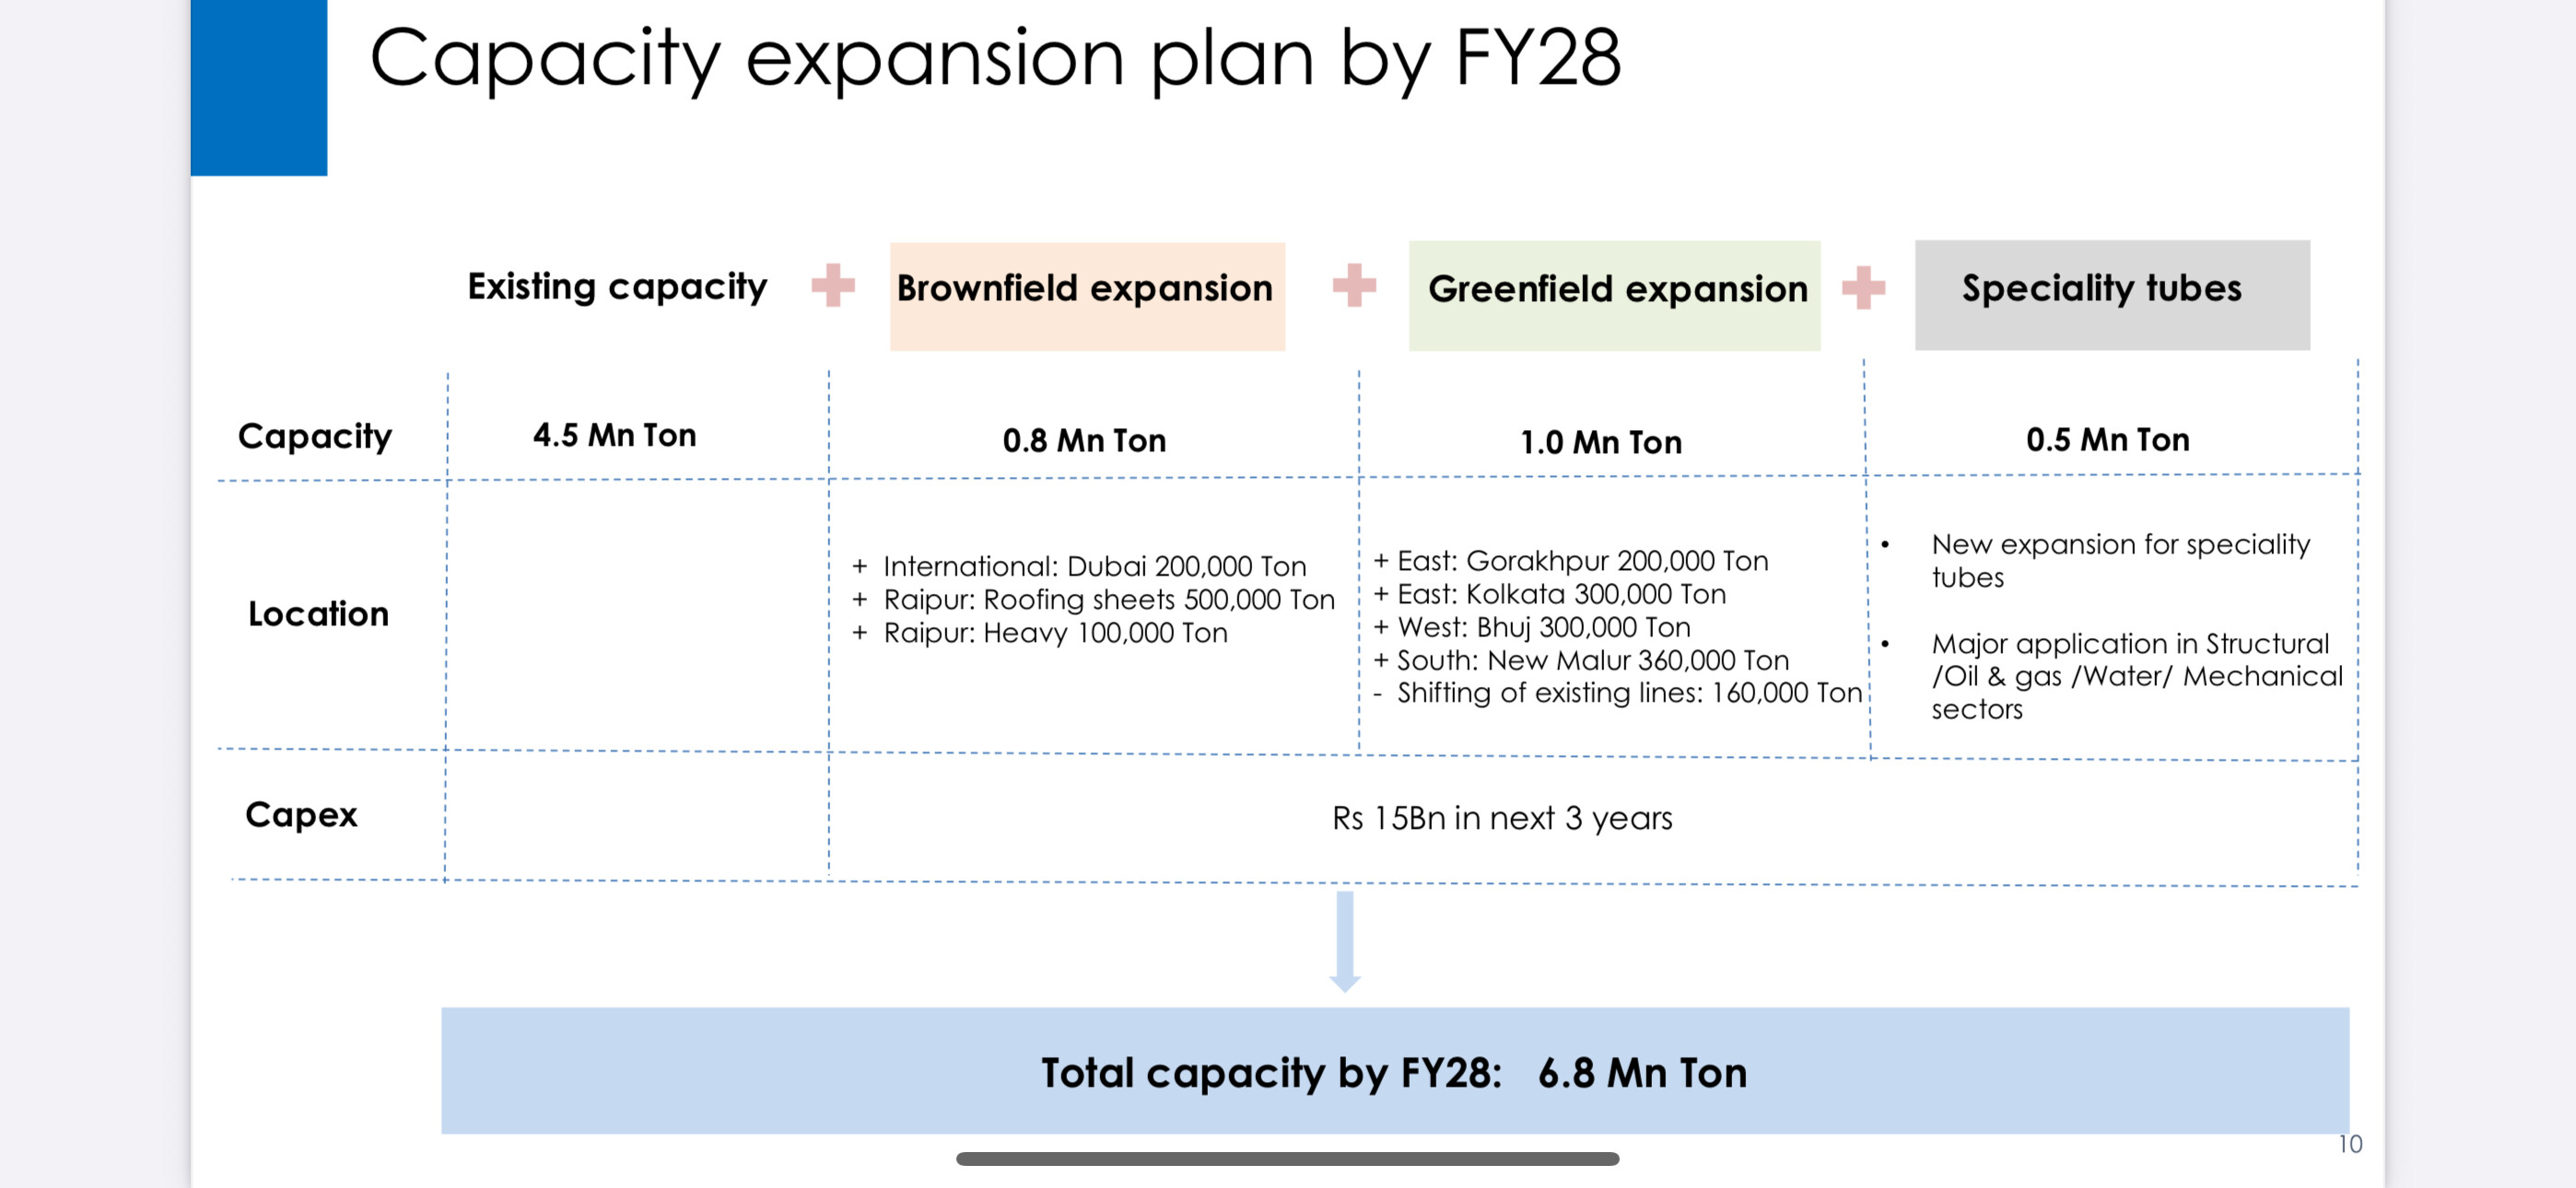
Strong strategic expansion across India and internationally, all funded by operating cash flows with low reliance on external debt
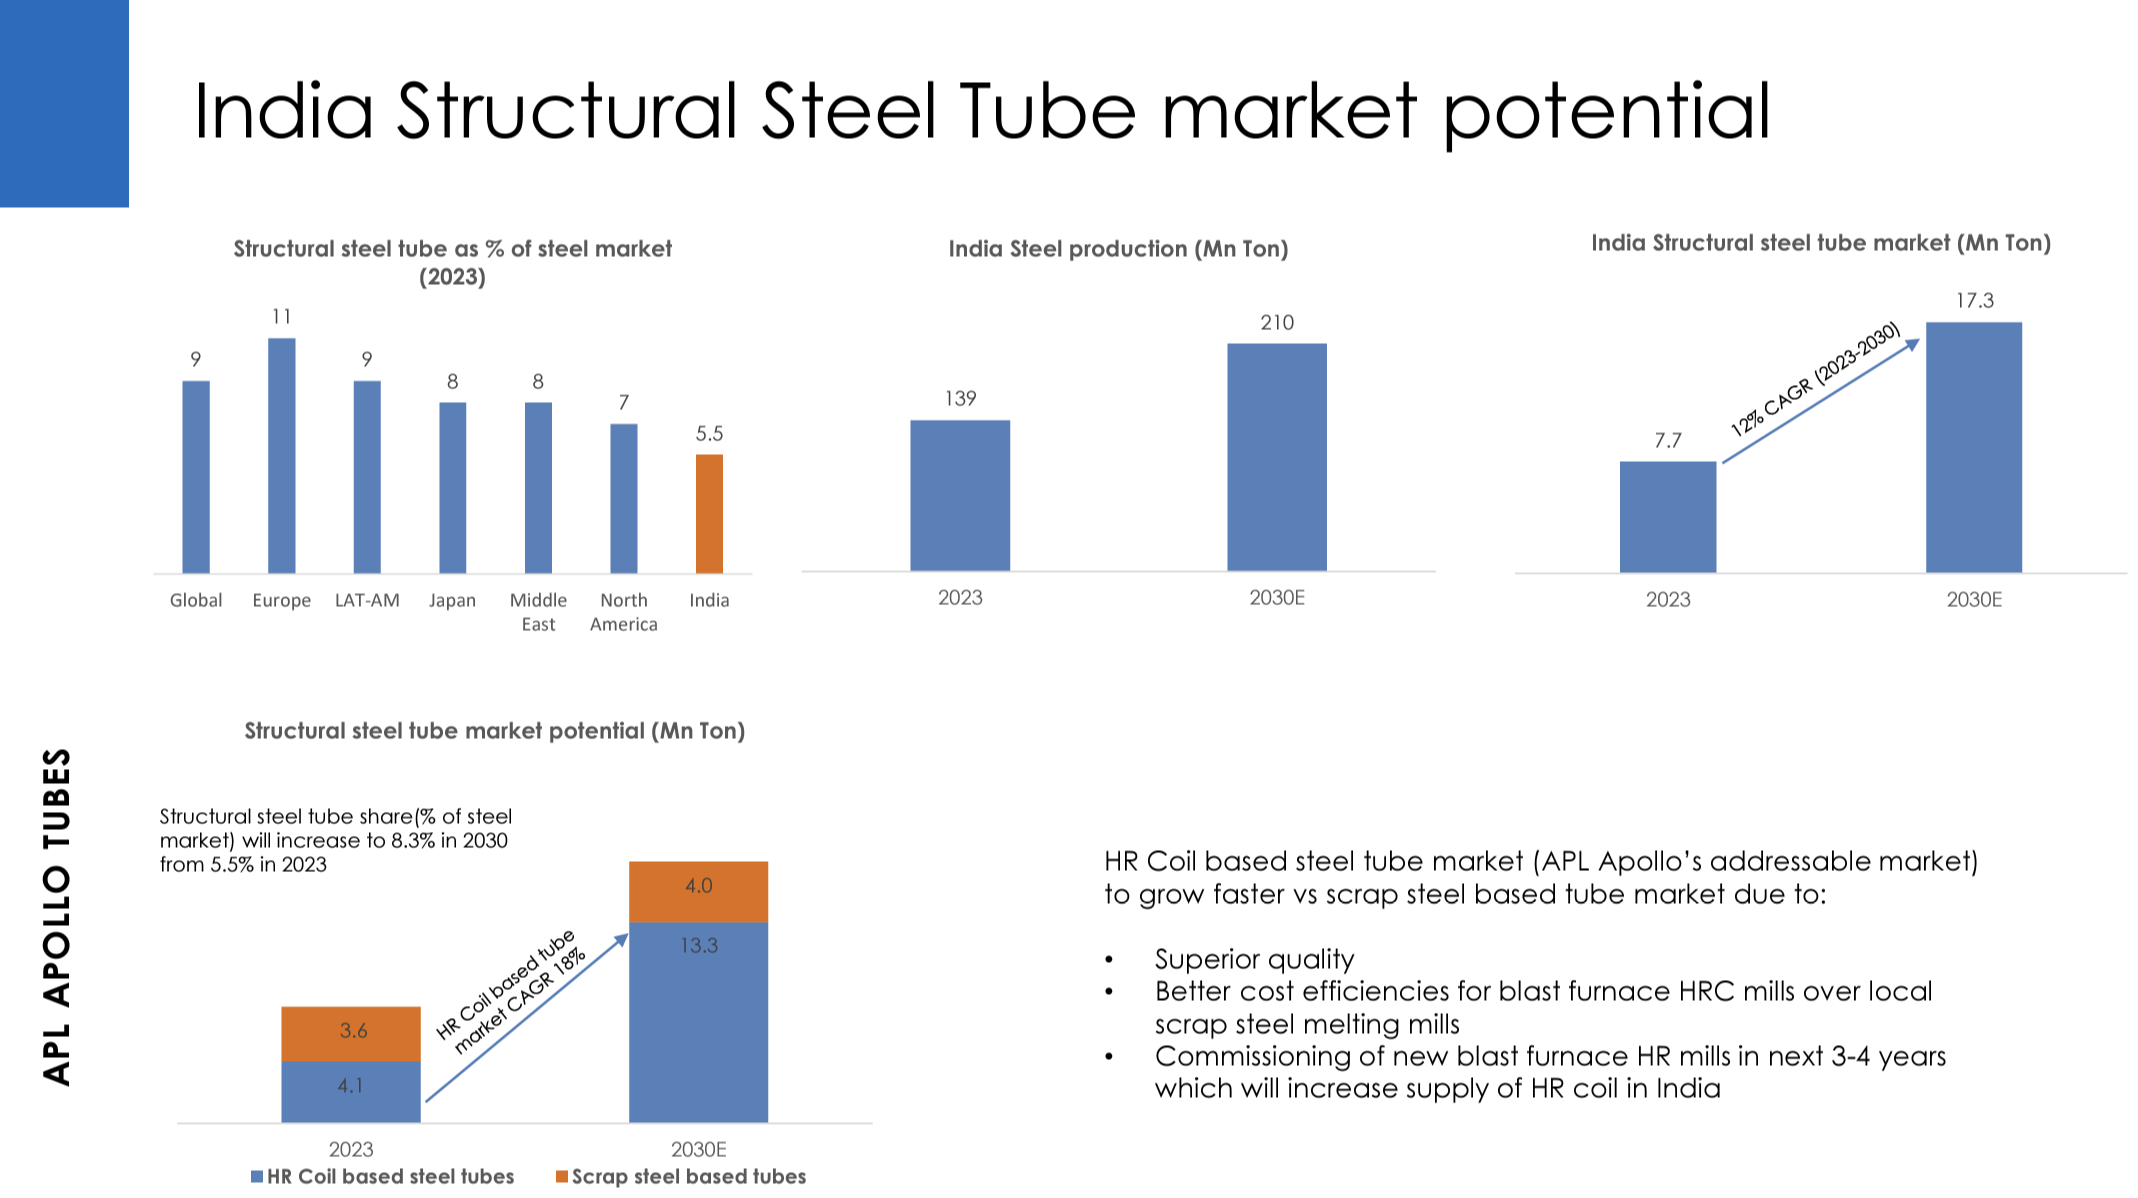
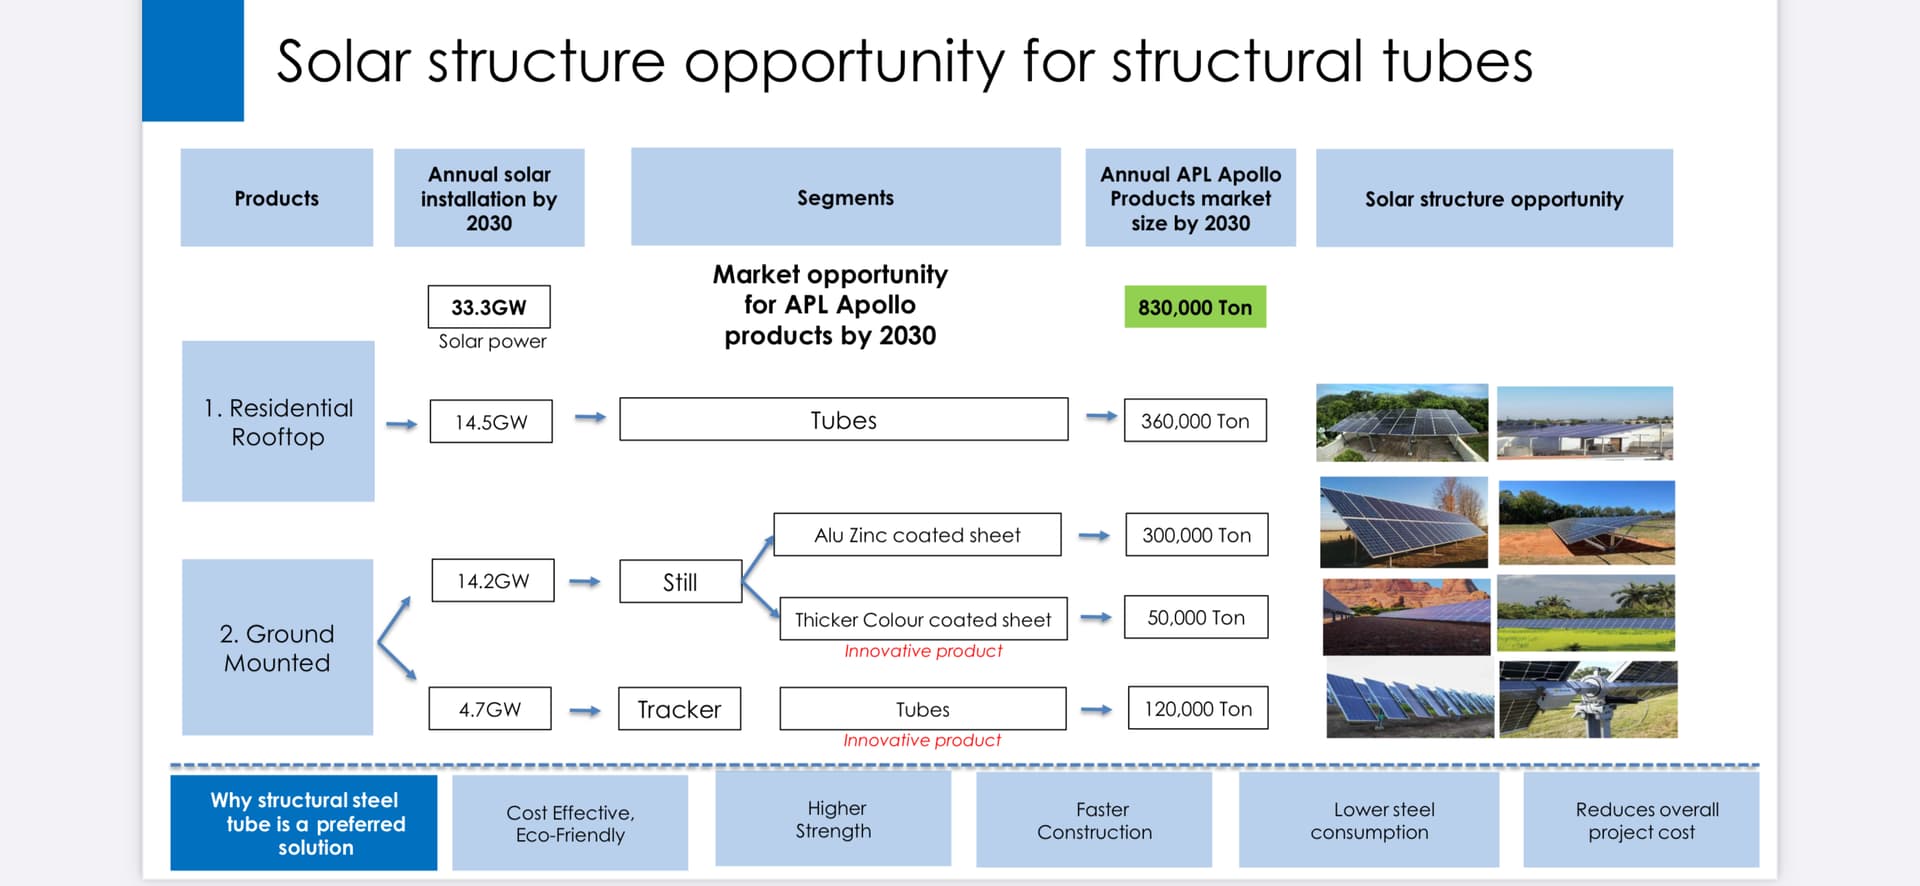
Positioning to capture key demand from the Solar Sector by 2030
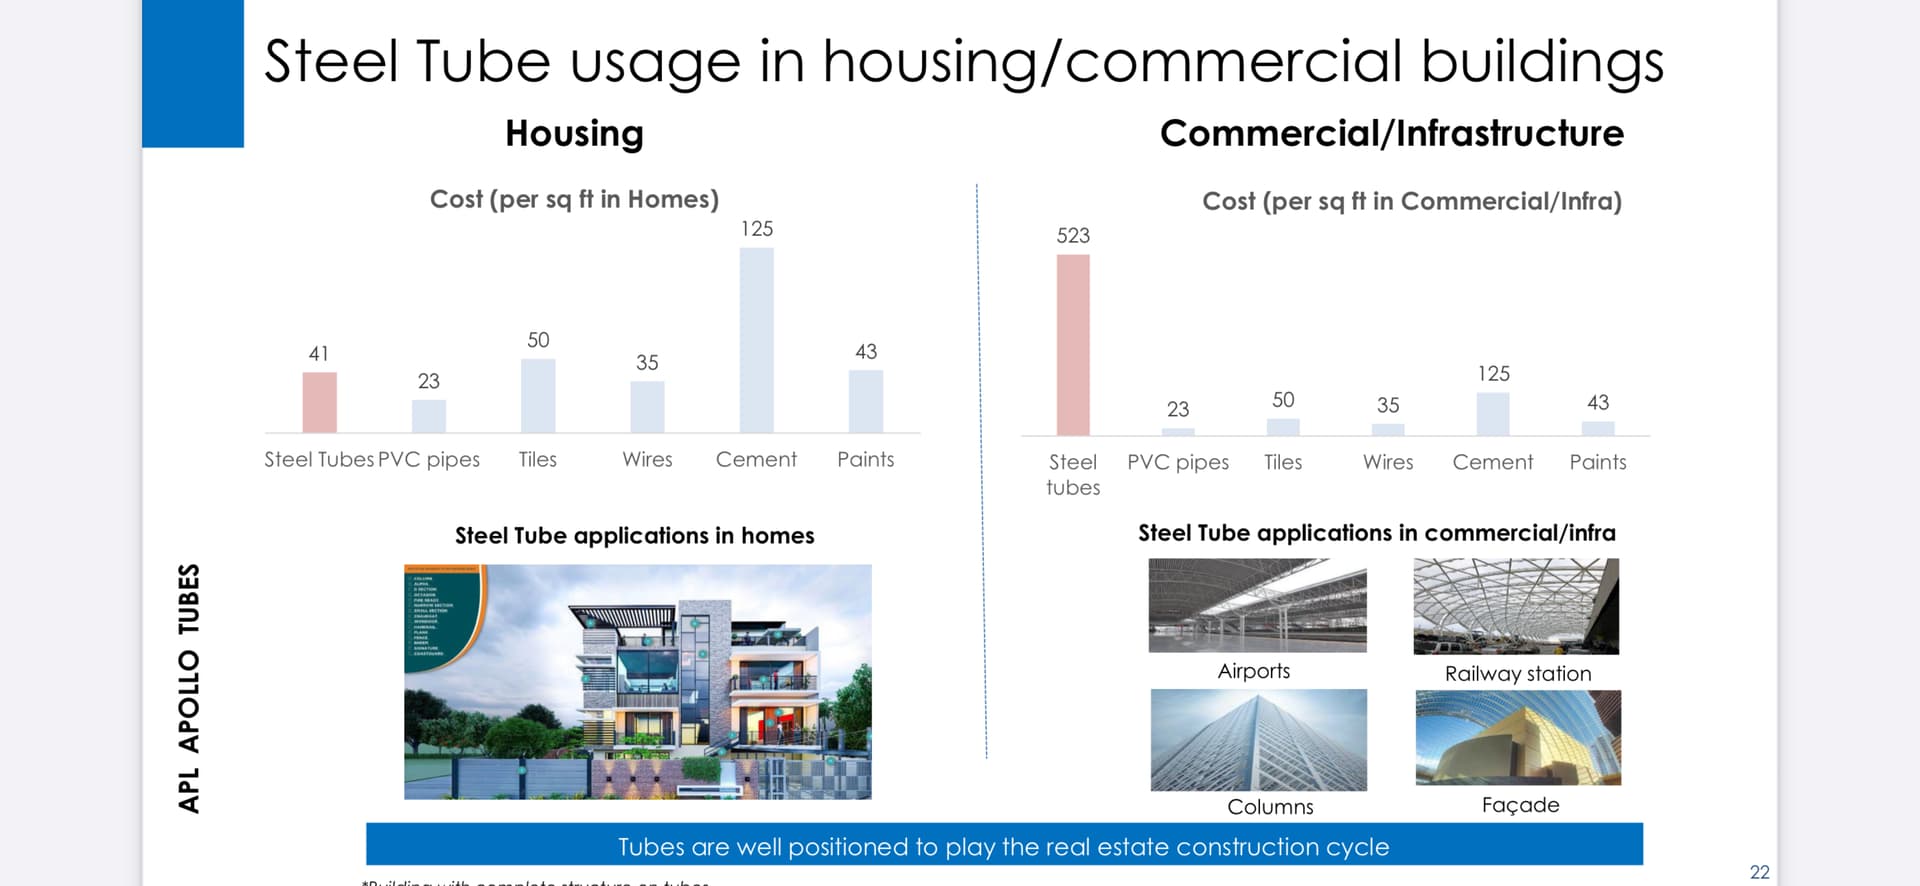
Steel tubes are becoming a compelling option both in Residential and Commercial real estate
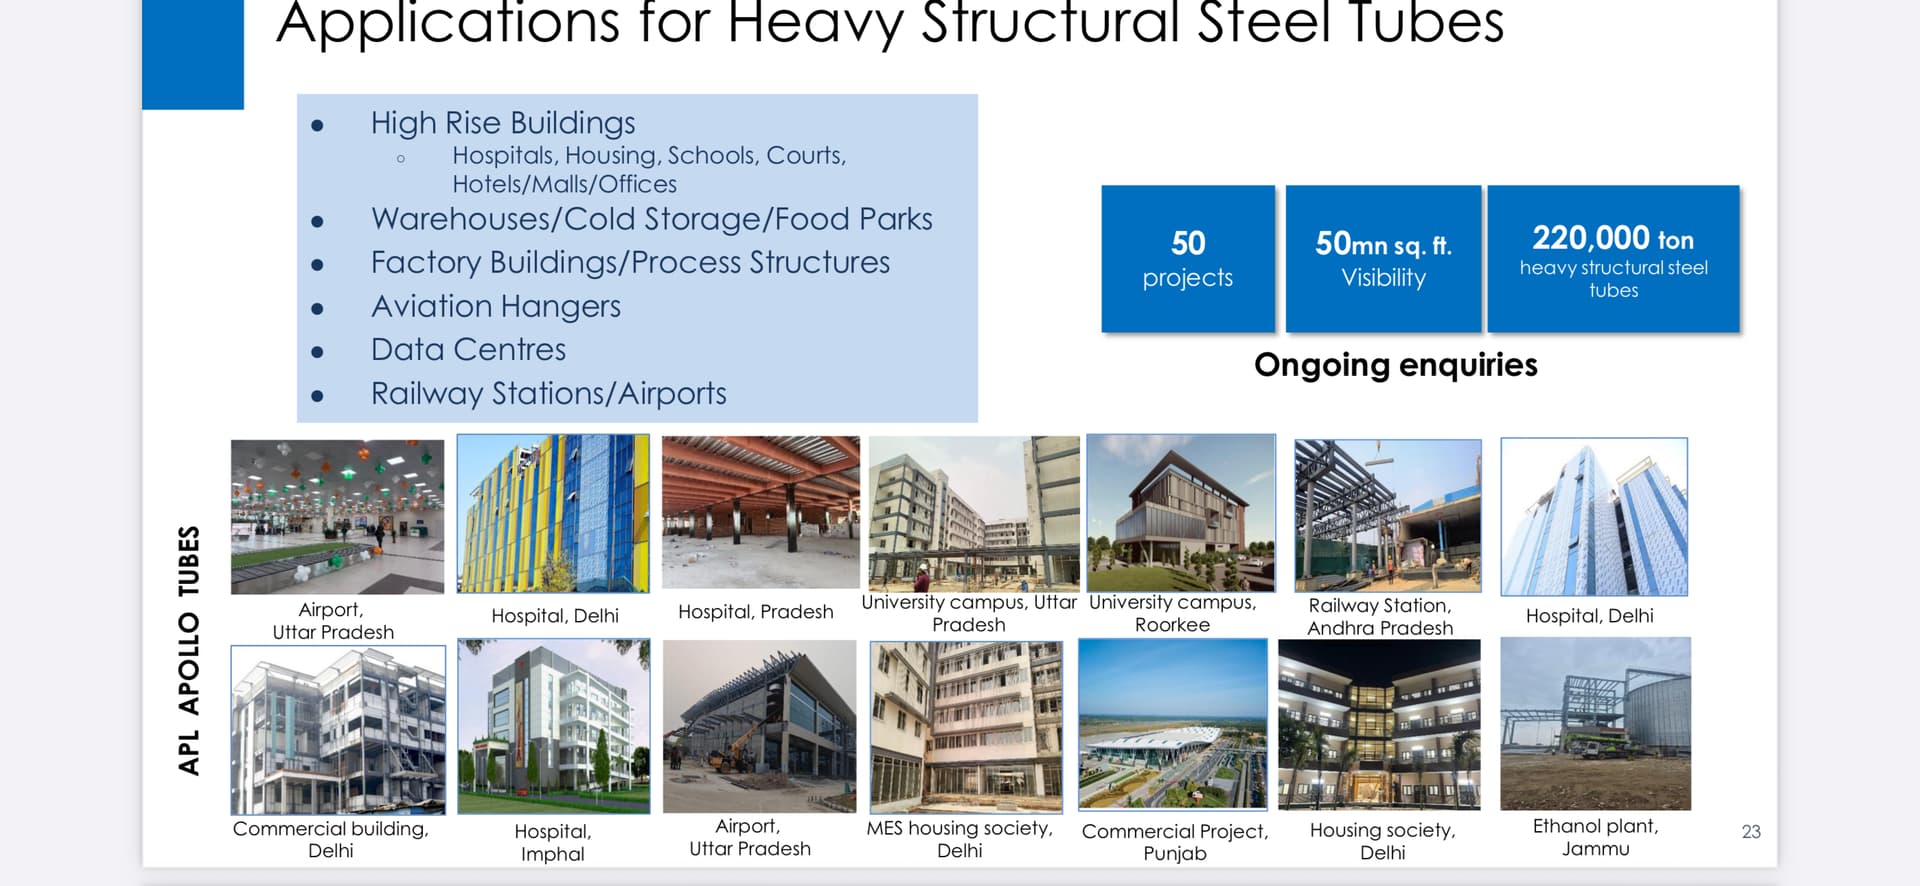
Strong commercial portfolio creates a strong competitive advantage to win future orders
5 Likes
Good volumes clocked by APL. Value add seems to have gone down QoQ from 61% to 57%, but expect ebitda/ton of 4800, if last qtr realisations hold. Expect co to clock EBITDA of ~400crs, 3X compared to the washout quarter last year. Volumes are 8.55L tons growing both Qoq and Yoy.