
If from the order book, 35-40 cr is going to be recognised in H2, I think this is without considering the AMC/service income which was 22% of H1 revenue. So H2 revenue could be higher than 40 cr. Is my understanding correct?
1 Like
Yes, that should be the case. The estimates are excluding AMC & spare parts for H2FY26, adding that up will increase revenue even further.
3 Likes
The company has come out with an investor presentation. They are participating in Smallcap Spotlight Conference at BSE.
The company has delared 115 crores Order Book, excluding AMC and Spares business. These two segments consists of almost 40-45% of topline, as stated in the presentation. Reading the presentation and investor conference talk by management, a few good points come to light-
- Many OEM are approachng the company for remanufactured machines. It can be a good revenue stream.
- Resenbaur has approached them to create International Service Department. They have started servicing in Nepal and Bhutan and it is extending.
- They are getting good traction in Petroleum sector and Municipalities.
- They are trying to enter into solid waste management (though not qualified yet) through making use of three products made by their associate Bucher Switzerland: sweeping, refuse collection and sewage cleaning.
- Airport sector is growing as expected.
They are expecting 35-40 crores of the order book to be reliased in this financial year. Spares and AMC can be another 20-25 crores. Thus, we can expect them to close the year with a topline of more than 100 crores. Based on past data, we can expect a net profit of 12 crores in the current FY. Current valuation of 250 crores looks okay, around 20 times current year earning.
Happy reading.
ANLON_compressed.pdf (1.9 MB)
3 Likes
While the company does not frequently disclose a single consolidated “Total Order Book” number in real-time, the order inflow has accelerated significantly in the last 6 months of 2025.
Key Recent Contract Wins:
- Noida International Airport (Jewar): A major ₹22.22 Crore contract awarded in October 2025 for the Operation & Maintenance (O&M) of airport equipment. This is a 5-year recurring revenue contract, providing high income visibility.
- Guwahati International Airport: Secured a ₹4.90 Crore order in November 2025 for the supply of equipment.
- Lucknow Airport: Won a contract to supply 3 Crash Fire Tenders (CFTs) from Rosenbauer International AG (Anlon is their exclusive partner in India).
- Other Orders: Multiple smaller wins for “runway rubber removal” and firefighting support services across various airports.
The shift towards long-term O&M contracts (like the Noida win) is a positive structural change, as it reduces the “lumpiness” of revenue that is typical in engineering projects.
Historically, Anlon imported equipment (like Rosenbauer fire trucks) and sold them.
Now they have commenced manufacturing and assembly at their facility in Karnataka (started March 2024). Assembling equipment locally improves margins and makes them more competitive for government tenders that favor “Make in India” products.
With the government planning to increase the number of airports to 200+, there is a direct, mandatory demand for Anlon’s core products: Crash Fire Tenders (CFTs), Runway Sweepers, and Rubber Removal Machines. Every new operational runway must have these under regulations.
Looks like they can do well if they can manage their cash flow.
2 Likes
9MFY26 topline at 75 cr of which M&A segment is 39.5 cr.
Has 94 cr of orderbook pending apart from AMC/spare parts (which contributes 30-35% of topline).
1 Like
The company has come out with great news, in the current financial year PAT may touch 12-14 crores, an eps more than Rs. 20.
Major capital expenditures, vehicle testing, and regulatory approvals are now complete. The company expects to unlock “significant efficiencies” as they move into large-scale production. They expect a rise in recurring revenue from Annual Maintenance Contracts (AMC) and spare parts as the fleet of deployed vehicles grows.
Cash flow was the problem with their balance sheet. As of late 2025, the company struggled with negative free cash flow, largely due to heavy investments in manufacturing capabilities and increased working capital requirements. Debtor days increased from 97 to 138 days, and working capital days stretched to 248 days.
In today’s release, management explicitly stated they expect “improved working capital efficiency” in 2026 due to the transition to scalable volume production and shorter lead times. If they successfully improve their collection cycles and leverage the new manufacturing plant for higher margins, cash flow should begin to stabilize and increase. I am hopeful.
Disc: Invested and biased
6 Likes
a { text-decoration: none; color: #464feb; } tr th, tr td { border: 1px solid #e6e6e6; } tr th { background-color: #f5f5f5; }
I’ve checked multiple sources online but haven’t been able to find any credible information regarding the order pipeline of Anlon Technology, neither in any interview nor any published info, If anyone has verified details on order pipeline and can share supporting evidence, ll be helpful
tracking this company for last 5 months.
Disc: not invested
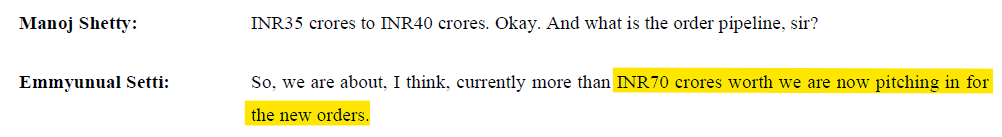
Pipeline as on H1FY26 (Source: H1FY26 concall). Order book as on H1FY26 was 115 cr, revenue excl. AMC & spare parts in Q3FY26 was 24 cr and order book was 94 cr. Therefore there was a net addition of 3 cr in orderbook this quarter. Not sure about the status of rest 67 cr pipeline (or any new).
2 Likes
Sharing notes from an expert call with someone close to AAI procurement. Everything below is from that conversation, not public disclosures. Two things that look a bit different from how Anlon has been framed in this thread.
1. Anlon is not Rosenbauer’s exclusive India partner. AAI’s Rosenbauer-side fire truck tenders are handled by a different India partner, not Anlon. Anlon’s AAI fire truck exposure comes indirectly through the Make-in-India clause (contracts under ₹200 cr require local manufacture, so the direct AAI bidder may still have to source body and assembly from Anlon). Real channel, but not the clean exclusive the thread has been assuming.
2. The competitive landscape across Anlon’s product lines is wider than the thread suggests.
- Fire trucks (AAI): Rosenbauer is not the dominant brand. Naffco and Marcee (via New Age) also compete actively, and the vendor split is closer to 50-50 than Rosenbauer-heavy. Tata Motors is also reportedly entering the fire truck segment.
- Grass-cutting machines: Anlon bids alongside Three D, Sai Aviotechnics (Pune), and Almighty (Dalmia Group).
- Surface evaluators: Three D has historically been the AAI supplier.
- Sweeping machines: Anlon does not come up in the active bidder list. Roots, Man Machines, and another India player lead this segment.
Most of these names haven’t come up in the thread, which is worth flagging when evaluating how clean Anlon’s positioning in airport equipment actually is.
Disc: Tracking, not invested.
3 Likes
Yes, fair observation. I’ve been tracking the same.
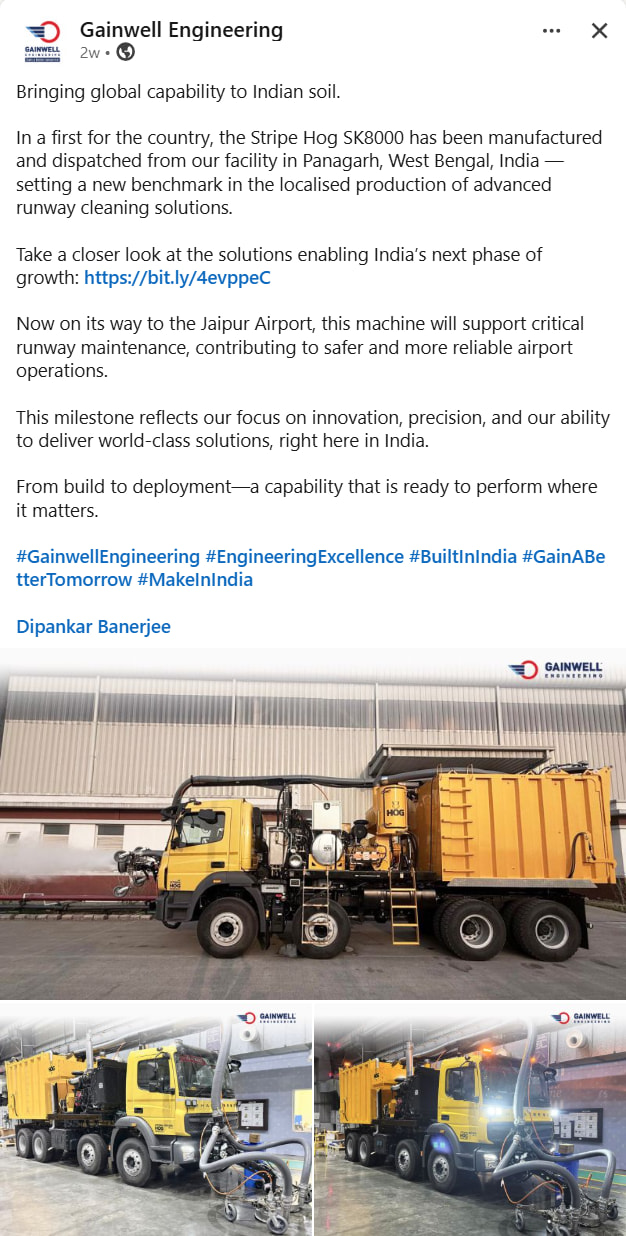
Recently noticed that Gainwell Engineering has also entered this space and launched its first runway rubber removal machine.
So much for the “moat” investors believed Anlon had, looks pretty replaceable.
2 Likes
No private company can be a monopoly like the government or even public sector companies. Every private company has to create a competitive advantage for itself and keep on protecting that advantage.
Anlon didnt start as manufacturer. They were service provider, procuring machines from outside India and providing maintenance and spare services here in India. Their entry into the manufacturing segment is a “backward integration”. Anlon doesn’t just sell a machine and walk away. Their business model creates a “flywheel” of recurring revenue- Sales, Spares, AMC: They provide Annual Maintenance Contracts (AMC) and Comprehensive Maintenance Contracts (CMC). This is the stickiness they have in their business.
Large OEMs like Tata Motors and BEML are indeed eyeing the aviation and specialized vehicle space. However, Anlon’s moat isn’t based on building “trucks,” but on mastering the specialized technology that sits on top of them. Anlon focuses on the fire-fighting and rescue equipment—the pumps, monitors, and chemical systems. In fact, Anlon often uses third-party chassis (like those from Volvo or Scania) and integrates their technology. If Tata enters, they may still need specialized partners to supply the “upper” equipment that meets ICAO (International Civil Aviation Organization) standards. Airports cannot simply buy a “fire truck”; they must buy a vehicle that is ICAO-compliant to maintain their operating license.
For a specialized fleet of 5–10 trucks at an airport, the maintenance (AMC) is where the real profit lies. Large OEMs often struggle to provide the granular, specialized service required for mission-critical airport equipment. Anlon acts as a boutique shop that can provide a “Command Post” vehicle, a grass-fire engine, and a crash tender in one package. For a giant like Tata, customizing 2 or 3 vehicles to a specific airport’s unique layout is often not “worth the effort” compared to large-scale commercial orders. Anlon topline in the last financial year [2025-26] is expected to be around 110 crores- not something where bigger player will be much interested.
BEML is already active in Crash Fire Tenders (CFT) for the Indian Air Force and Navy, and they are the probably the only suppliers to defence establishments. However, Anlon moat is not in manufacturing- it is in after manufacturing.
2 Likes
Another example - Road Sweeping Machines
https://x.com/Sahilinfra2/status/2043520156685775243?s=20
With so many players entering every vertical, the question is no longer whether Anlon will win orders. The real concern is whether it can sustain its margins in a tender-driven business.
I find that increasingly difficult to believe.
2 Likes
Everybody Suddenly appears to be bearish here in Anlon
Any other reason apart from increasing compitition
In my limited knowledge, I think company should plan to expand in export business and services segment very seriously to maintain their growth phase
Recent concall have suggested that they are planning to enter into export market this year
But execution is key factor here
I’m Very hopeful 
Business is doing well and will likely continue to grow over time. The key is getting the perspective right. The company doesn’t have a meaningful moat, contrary to what I initially believed. With increasing competition, it is just another player in the market, not the only one or the dominant one.
6 Likes
The year 2026 is another significant year for us, as our long-term associates, M/S ROSENBAUER International A.G Austria, has made a strategic decision to join hands with Anlon for getting a series of fire engines manufactured from Anlon’s Bangalore facility. This key step extends Anlon’s reach beyond the borders of India.
https://nsearchives.nseindia.com/corporate/ANLON_23042026180308_Anlon-Business_Update_Final.pdf
2 Likes
Debtor days have increased let see
Would that mean Rosenbauer has been agreed to get Anlon products for export Market ??
Encouraging updated……the tech collaborations are indeed worth noting…….but
The order book is equivalent to just last year’s revenue…….. And it includes spares, AMC etc
Will we see an acceleration in orders in coming days……. Seen against a backdrop of current predicament faced by the govt on capex, considering likely upgrades in subsidy quotas to cover price hikes in general population centric commodities fuel, fertilizers etc……. How do we see the future growth panning out……request elders to help understand.
1 Like
ANLON_01052026192016_OUTCOME_01052026.pdf (378.2 KB)
Two new update, CEO of rosenbauer first time visit plant & company doing fund rise of 50 cr.
Does this preferential amount would be use for funding as a working capital of big domestic or export orders or they are plannig foreign service centre opening ?
3 Likes