
All solar module manufacturing companies are going to have a huge headache post the december regulation - restricting solar modules to only have Indian made solar cells kicks in. The companies that make solar cells are going to make merry.. take for example websol - promoter is buying, balance sheet is good, now fundraising but expansion is going on. policy tailwind. Just look like a good stock to research on.
Hi Vamsi,
My understanding is that you are expecting a better market for Cell manufacturers post December (This is not the first time such a situation is being created by Govt but then in the past the same Govt diluted the restrictions many a times by extending the deadlines. I too hope they put and end to extensions and implement ALMM List II strictly.
However, better market should be utilized by Alpex. here the questions is, With the data available in public domain, how can we believe Alpex management’s timeline commitment?. Being an SME with just 87 Lakh free float shares, the price fluctuation is beyond my imagination. If they miss Cell production this quarter then share price can head towards south.
Secondly, your example of Websol energy. Yes. I agree that It is a great company having Cell manufacturing experience for over 30 years. However, look at the valuation for a company with 30 years of Cell expertise versus a company which is delaying the plant commissioning itself for 01 full year. To become a Cell expert, to achieve 25+ efficiency which may take another 06 months and then to become price competitive is far far away.
Just having a cell line post December may bring share price speculation but not cashflows. As of now, Alpex is valued better than Websol due to less free float but If Alpex failed to execute then market will show its right place. Less free float is a double edged sword.



I have issue with Alpex management’s overconfidence. However, I wish they execute this time and prove me wrong. Just my opinion.
will agree… 100% of the solar stocks and solar EPC stocks are in the drain… I just liked websol more because too many good things happening around that company… will have to study alpex more I guess… good work…
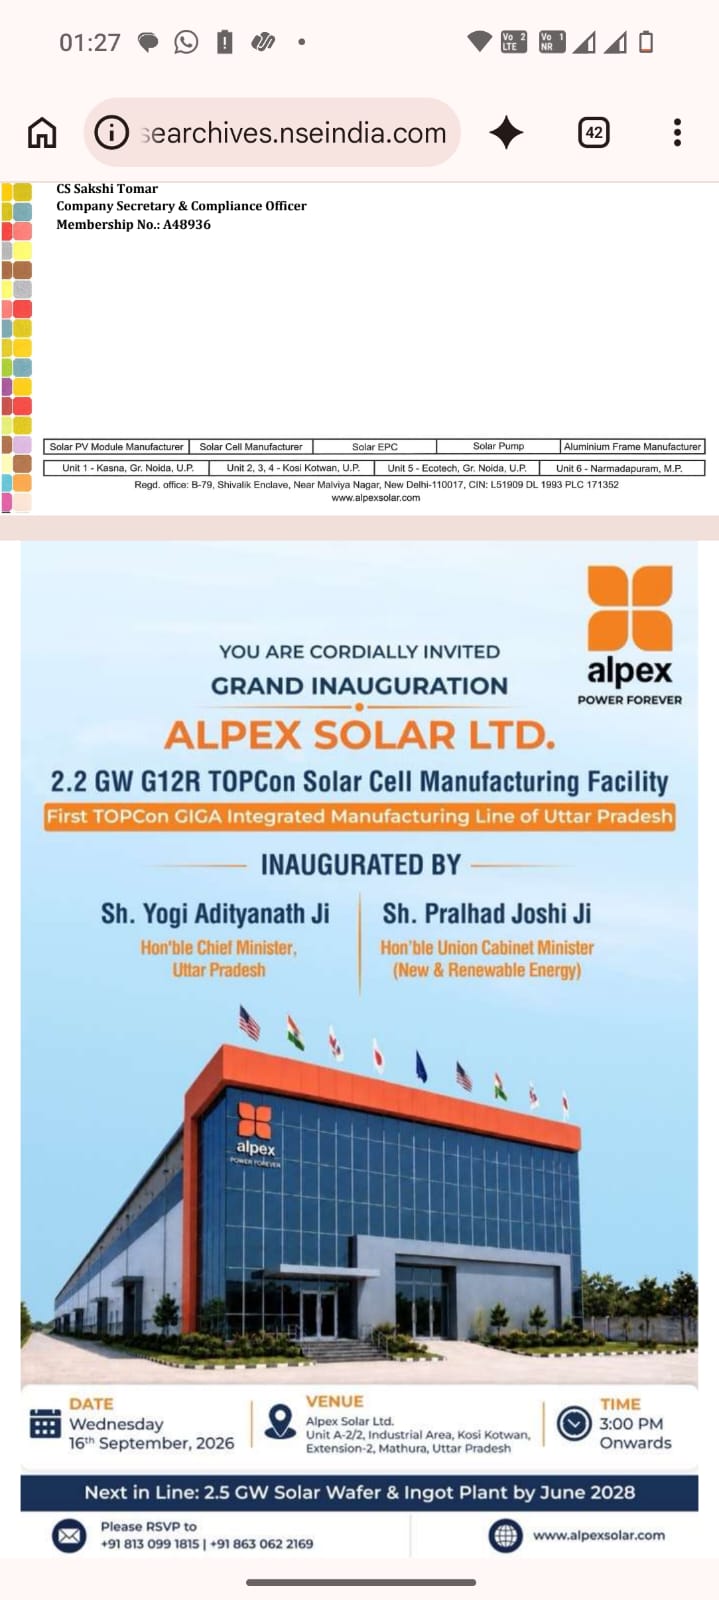
Not received EC till now. It may take another week or two. However, Alpex would have got oral/email confirmation for EC based on the review meeting held on 10-09-2026. Let’s wait and see.
2 Likes
Does anybody have any information from the AGM held on 29th September? Any details on the cell plant’s EC approval and production timelines would help?
1 Like
Continuing the discussion from Alpex Solar Ltd - Stunning sun powered performance?:
CMP- 780
Mcap - 1193 Crore
PE - 9.93
Business Overview
Incorporated in 2008, The company offers integrated renewable energy solutions across the solar value chain, including solar cells, solar modules, solar water pumps, aluminium frames, EPC services, and IPP operations. As of FY26, it has installed 26,000+ solar pumps.
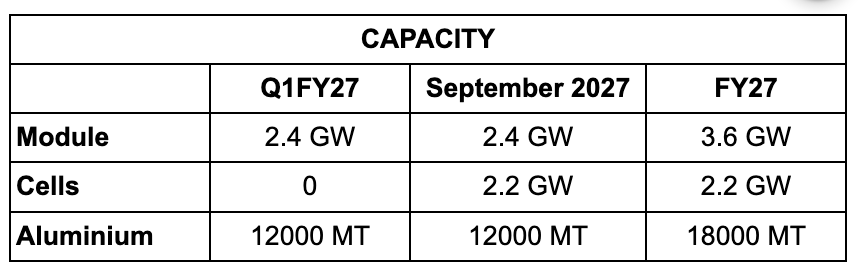
Cell factory will ramp up in Q3 and will run full-fledge from Q4
Solar pump contribution in revenue
FY26 - 223 CRORE
FY27 - 500 CRORE (EXPECTED DUE TO KUSUM 2.0, MGMT GUIDANCE)
Pilot project for wafer
Manufacturing Facilities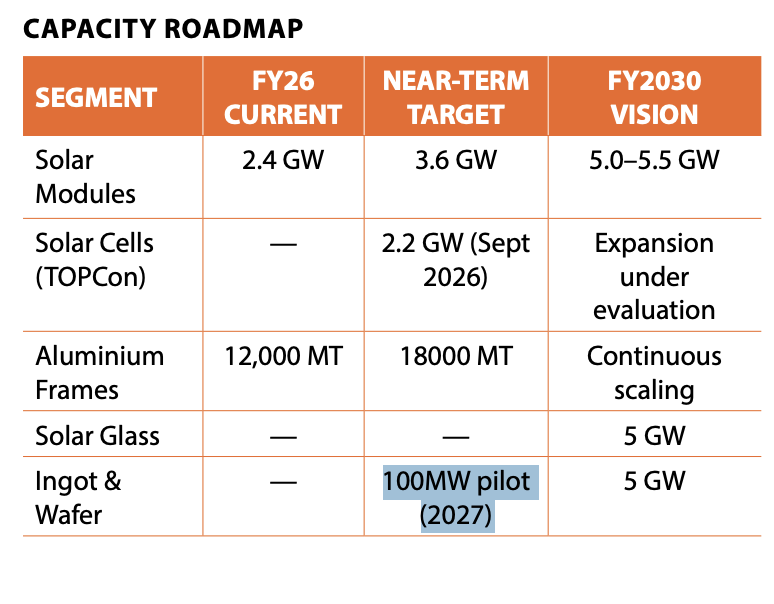
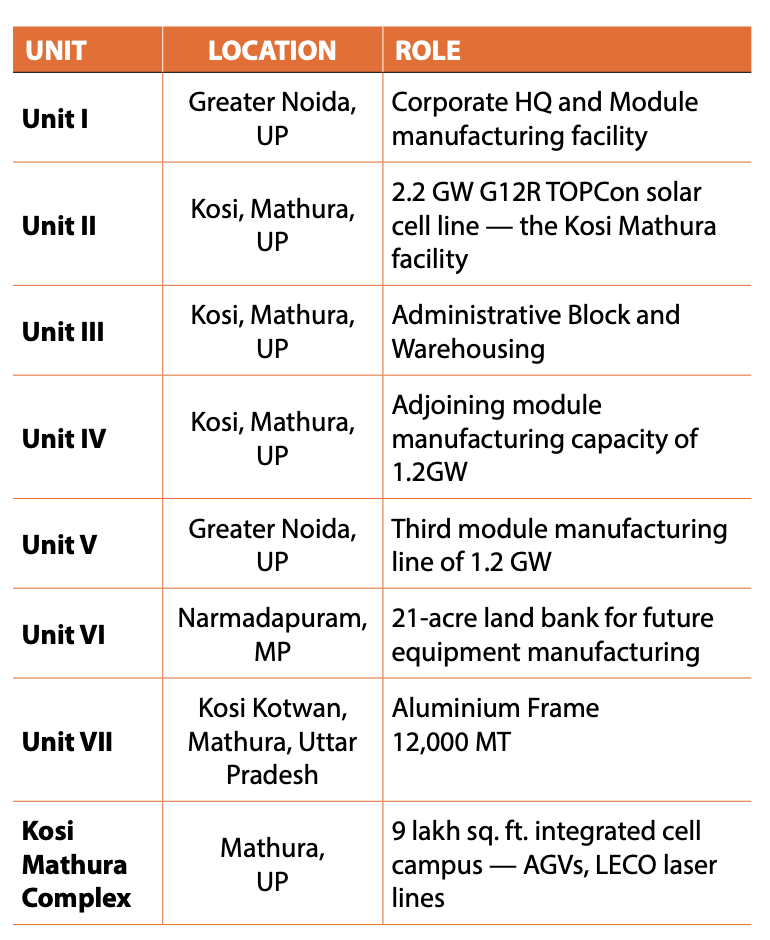
Fund infusion in September 2025
A total of 260 cr was infused via warrants and preference at 1202 rs per share, out of which 200 cr were infused by promoters.
Why cell matters?
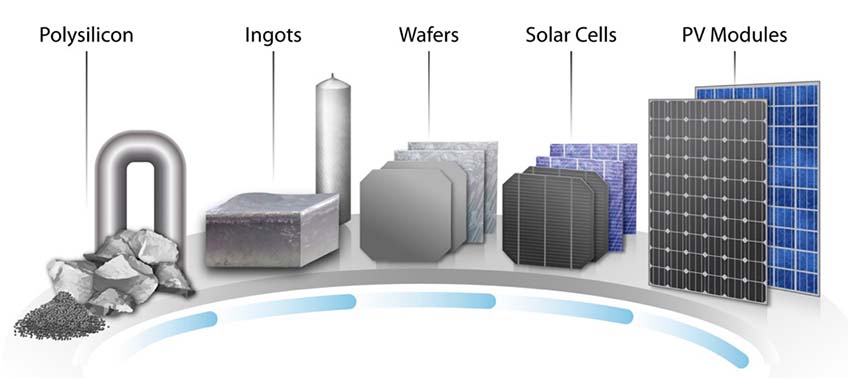
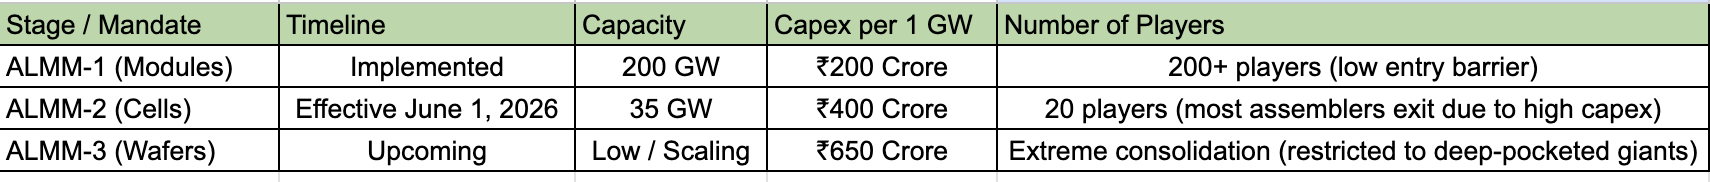
Ebitda margins in modules are around 10-15% as of today and in cells are around 35% making blended margins around 24-25%.
Financials & Projections

*Revenue and Margins are as per mgmt guidance
As we can see Fwd PE falls to 3.5-4 next year. LT Debt of company will peak at 360 crore, next year company is expected to close with approx 900 crore ebitda.
Competitive Landscape
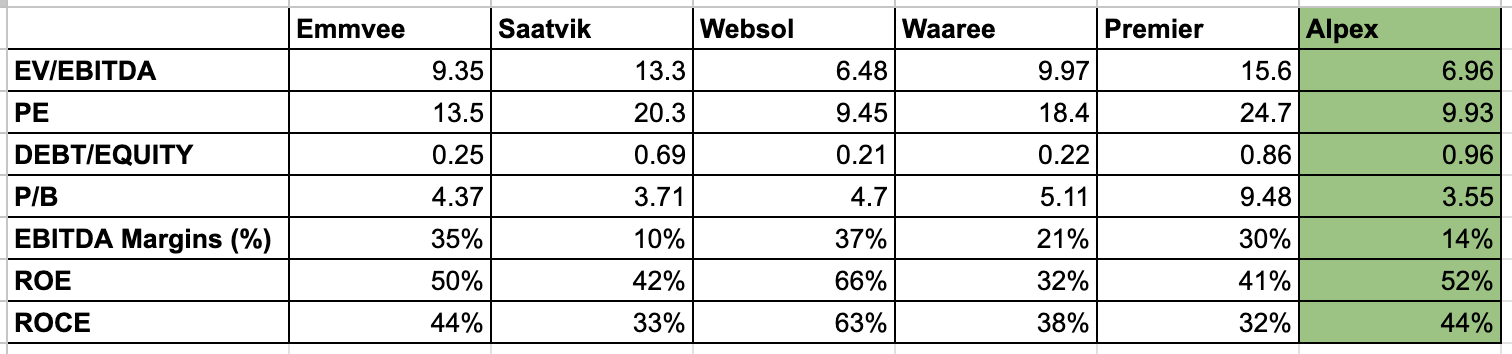
One thing to note here is that even 1 rs of cell is not yet contributed in the financials of alpex, still numbers are looking great, from Q3 Revenue & EBITDA will start moving up, Margins will go up from 14% to 22-24%, All capex has been incurred and now its time for revenue to pump in, company has spent 890 crore in 2.2GW cell plant and financed it via internal accruals, debt & promoter infusion.
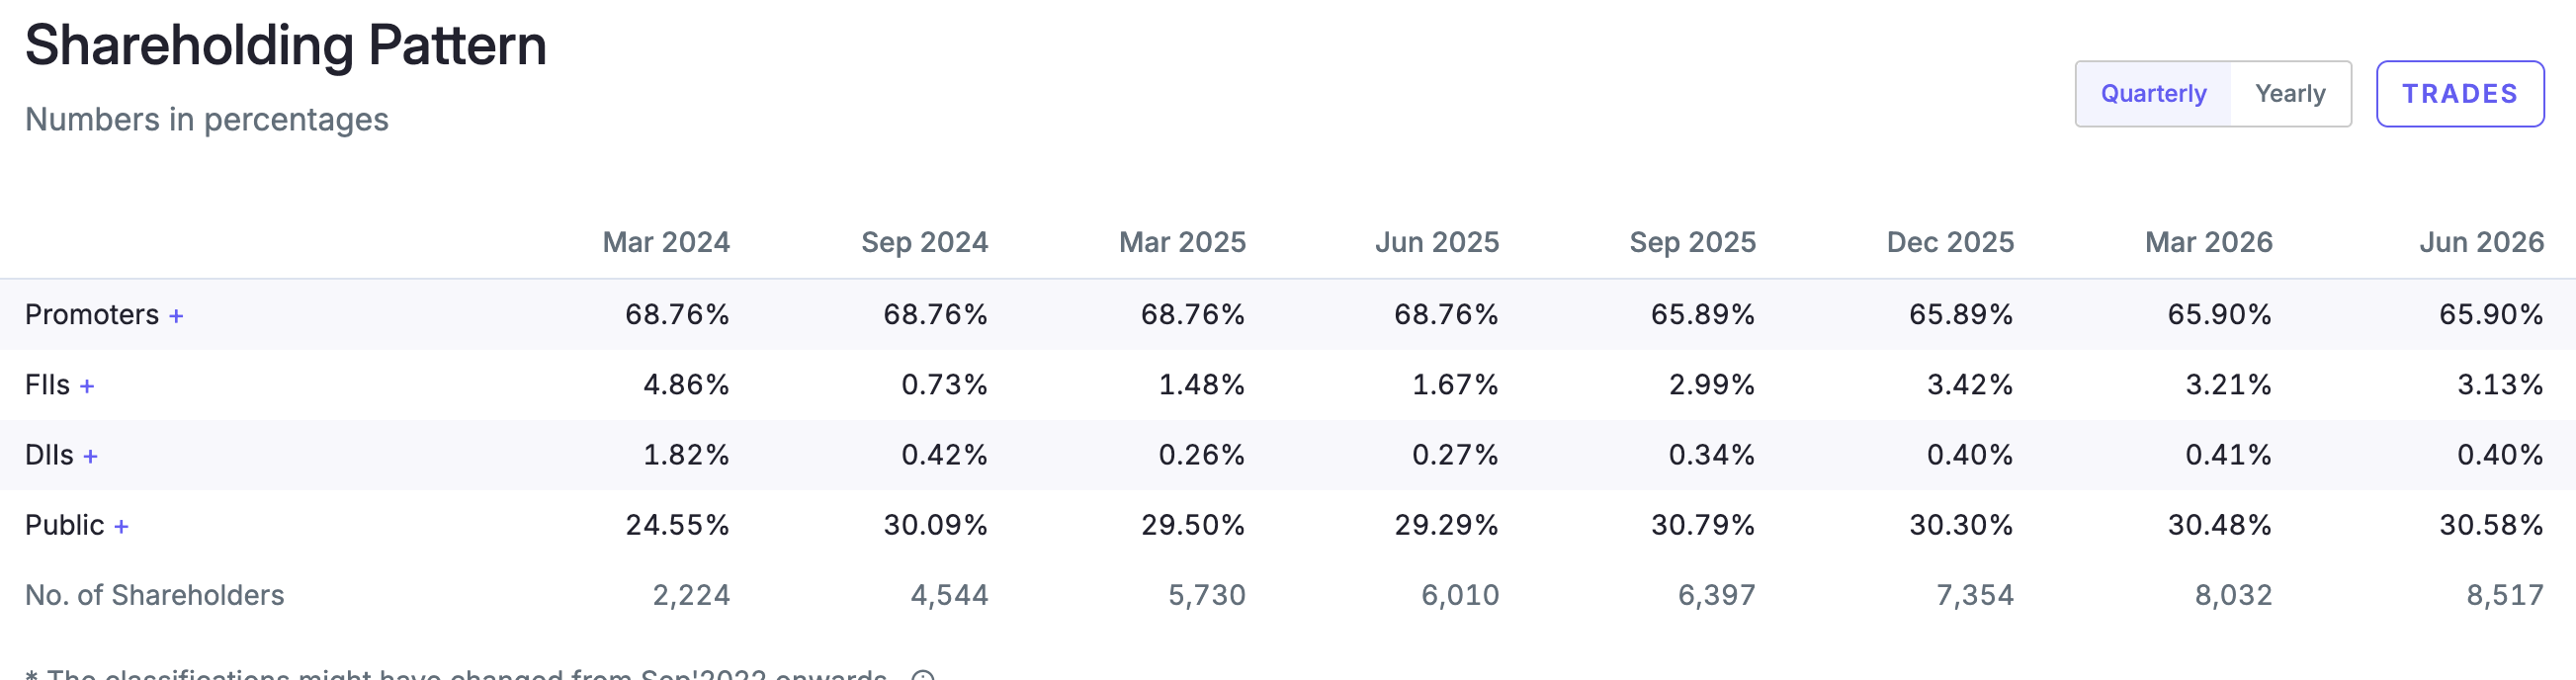
Industry wide a phenomenon is seen where companies are reporting great profits but PE is constantly falling, usually it is said that PE depends on growth but companies are growing very fast but PE multiple is falling, for example warree energies was enjoying PE of 35x a year ago and today it is trading at 18x,similarly premier energies was trading at multiple of 45x a year ago but today it is trading at 25x. But this cant happen with alpex anymore because it is already trading at PE of 10 and Fwd PE of 4. One more reason is ofcourse huge expansion in margins from 14% to 22-24%.
If today, you want to start a factory with 2.4GW module & 2.2GW cells, 12000MT aluminium and solar pumps, it will cost around 1600-1700 crore and this company is trading at EV of mere 2400 crore.
MGMT/ Promoters
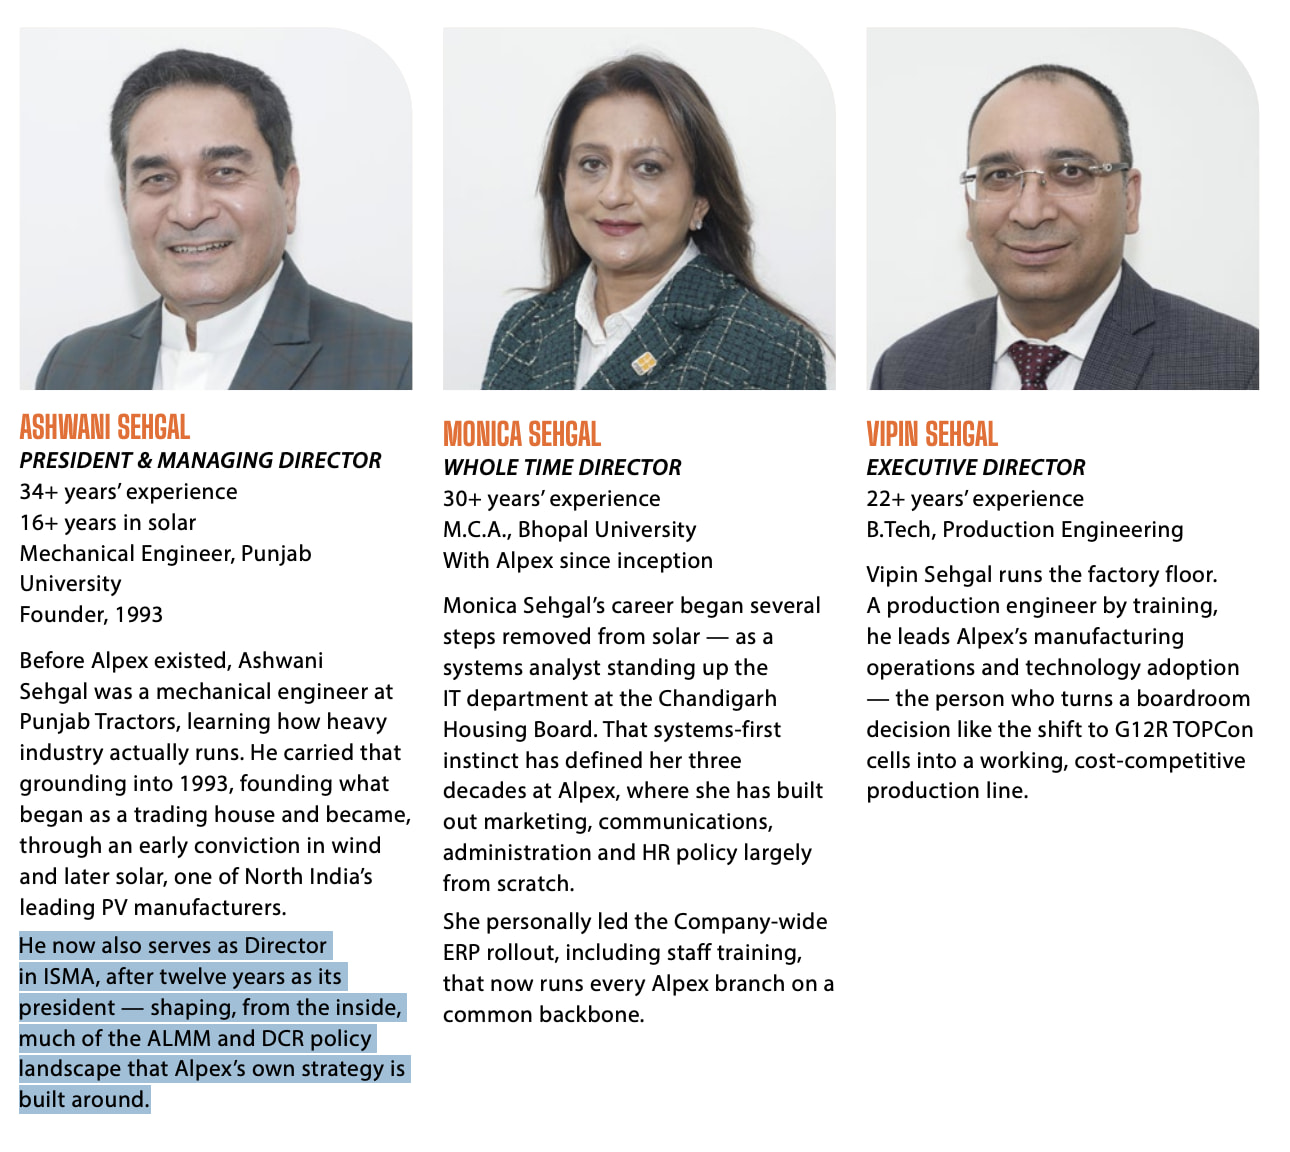
*ISMA means Indian Solar Manufacturers Association
Migration from SME to Mainboard
The company currently is trading at SME and as per regulation is eligible to apply for mainboard on 15th feb,2027, usually this process takes 2-3 months, company said they are already following all the regulations as a mainboard company and will apply for mainboard immediately next day of eligibility.
Risks
Delay in MNRE approval which company is awaiting for cell plant.
2 Likes
China’s proposed solar tech export controls: what it could mean for Alpex
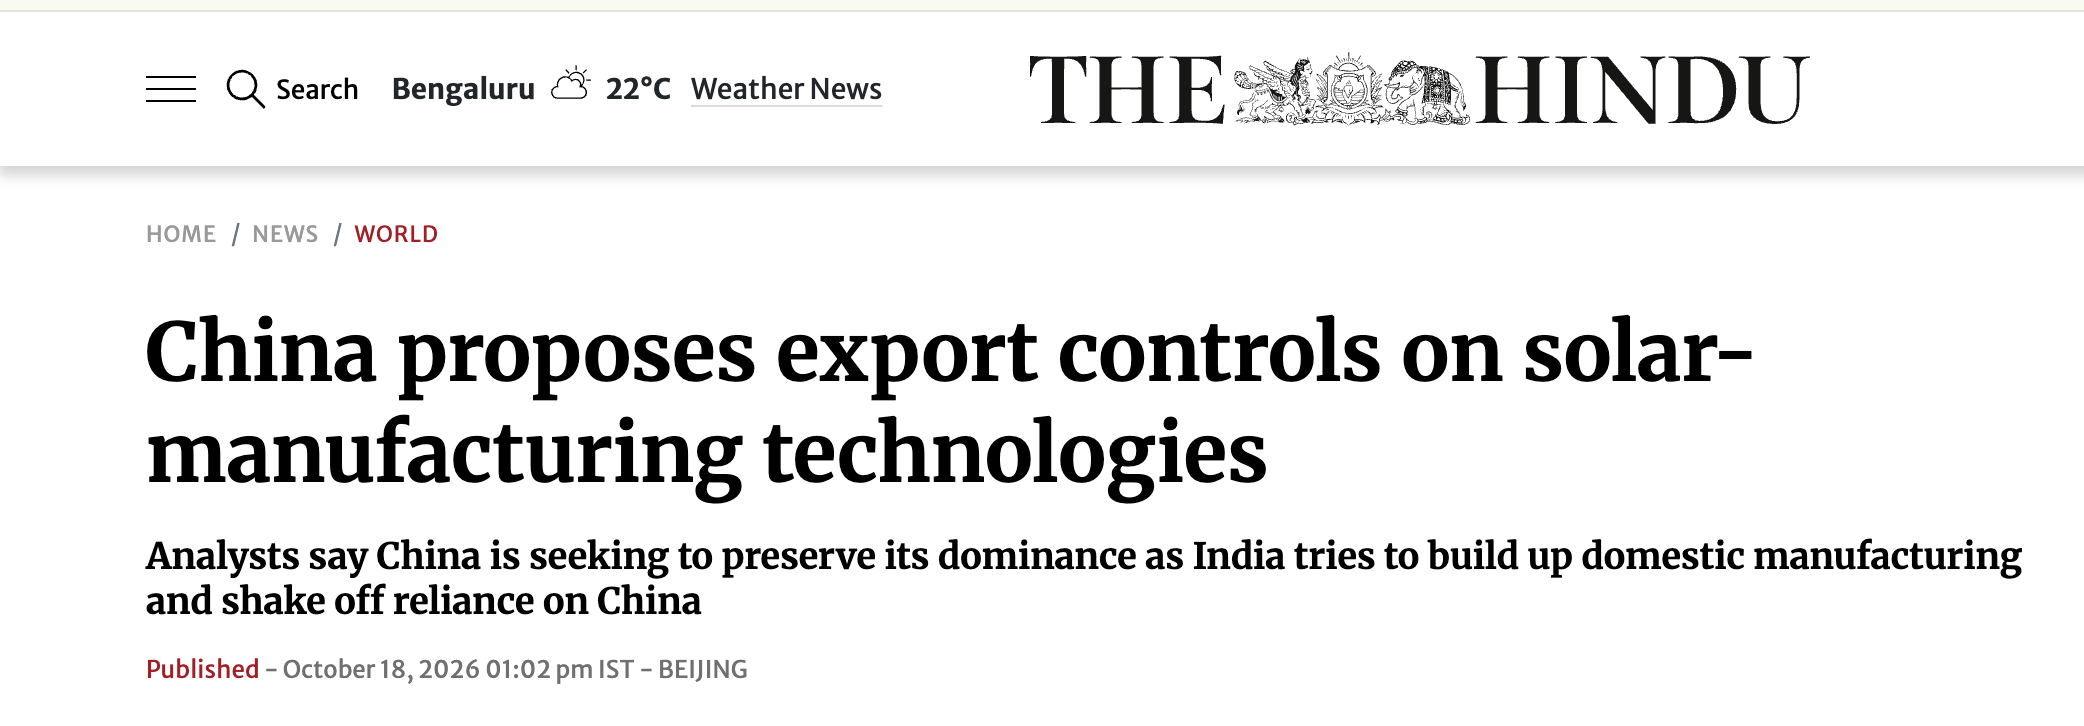
On Oct 16, China’s Commerce Ministry published draft export controls on 12 solar manufacturing technologies (Joint Announcement No. 48 of 2026).
- This is about know-how, not products. Finished cells, wafers, and modules are explicitly out of scope. The controls cover technology licensing, equipment exports, line installation and commissioning, and on-site technical support.
- Two tiers. Banned outright: perovskite/tandem cell manufacturing, fluidized-bed polysilicon processes, and very thin wafers. Restricted (licence needed): large polysilicon plant engineering, advanced ingot pulling and wafer cutting, and high-performance TOPCon, HJT and back-contact cell processes.
- One part is already live. Since Oct 16, Chinese exporters must register these technology transfers, including deals already underway. Public consultation on the full list closes Nov 15.
- The cell line itself is safe. Alpex commissioned the full 2.2 GW G12R TOPCon line in September. The pending MNRE evaluation is the near-term risk.
- The cell ramp depends on outside technical support. On the concall, management said technology consultants were on site commissioning the line and would train Alpex’s team over the coming months. Management said about 1 GW of cells would be available in H2 FY27, and this is where these restrictions, coupled with delayed MNRE approval, hurt.
- The bigger exposure is the 2.5 GW ingot/wafer plan. Management said the technology partner and machinery selection were about 70–80% done, targeting ALMM List-III, with active work starting once cells are running. Ingot pulling and wafer cutting are in China’s restricted tier, so this plan sits right in the path of the new rules.
- This could also work in Alpex’s favour. If new cell lines get harder to build in India, existing cell capacity becomes scarcer and more valuable, especially as ALMM List-II for cells comes in.
- The biggest unknown is the definition of “high-performance” TOPCon. If mainstream TOPCon falls below the threshold, most of the impact on Indian cell makers goes away. The wafer and ingot restrictions still stand either way.
Questions for the thread:
- Does anyone know if the consultants for the cell line and their on-site support will be affected by this?
- Do you see this as a net negative for Alpex, or as a moat for a company that already has a cell line commissioned?
CRISIL upgrades Alpex Solar’s bank facilities to A-/Stable and A2+; total rated facilities rise to Rs.1078 crore.