Is anyone covering this.
I went through the last concall of Alkem Labs.
My understanding is that they are looking to grow at par or better than Indian Pharma. Chronic is growing well and Acute is helping (though there is some seasonality). The raw materials prices are stable and helping recovery of bottomline. Biosimilars division is tiny and not expected to impact topline significantly atleast for another few years. US price erosion has come down to single digits now (earlier double digits). No major capex in sight except for an investment in the US. They are doing very well in ROW markets and expect to continue to do so.
Currently price at around 35 times earnings, I expect nothing extraordinary going forward - maybe 10-15% (at or above Indian Pharma growth). They had a great 2020 and 2021 due to uptick in Acute business; and not so good 2022 due to increase in raw materials prices and price erosion, etc. They expect Chronic segment (around 10% higher margin than Acute) contribution and debottlenecking to help improve margins (minor) going forward.
Yesterday there was a news with allegations of 1000 cr tax evasion against the company (read on social media, not reliable) and therefore the price dopped by 6% however they came out with clarification that this is completely false, and nothing to worry about.
I am waiting to see how the India Pharma and ROW story pans out - though I do not expect great returns from here (but who knows). It is only a small part of my portfolio and no transactions in the last 6 months. Sitting at much lower prices hence the cushion to wait and watch.
Alkem Labs -
Key highlights from FY 24 -
Continues to rank no 1 in Anti Infectives, No 2 in Vit/Min space in India
India business contributes to 68 pc of sales, grew by 5.4 pc
US business contributes to 21 pc of sales, grew by 10 pc
Rest comes from RoW mkts ( LATAM, Australia, EU ), grew strongly at 33 pc
Cash on Books @ 3550 cr
Anti-Infectives mkts were sluggish throughout FY 24, which affected company’s India performance. However, the company continued to do well in Anti-Diabetic, GI, Vit/Minerals and Derma therapies
Lesser pricing pressures in US and descent volume growth in US + RoW business helped improve overall gross margins. Company believes that the worst of pricing pressures in the US business should now be behind
Company’s domestic biosimilar business ( under its Subsidiary - ENZENE ), with 7 brands continues to ramp up well
Aim to grow revenues by 10 pc in FY 25 with stable gross and EBITDA margins ( with an upward bias )
Capex lined up for FY 25 @ around 600 cr
Expecting the anti-invectives mkt to pick up in FY 25 ( as FY 24 was exceptionally weak for this segment ). If this happens, company may outperform its guidance
30 pc of company’s India products are under NLEM
Company has the largest trade generics business in the country. At the same time, the branded generics business continues to do well. Company believes, both can do well simultaneously
As the company’s chronic business ramps up in India, Margins should improve further over the medium term
Launched 3 new products in US in FY 24. Going to launch 6 new products in US in FY 25
Expect to maintain 4.5 of sales as R&D expenses going fwd
Setting up a Bio-Similars plant in US under its Bio-Similars subsidiary - ENZENE. It’s mainly going to engage in contract manufacturing operations. Expect it to contribute meaningfully from FY 27. Capex required here should be around 400 cr
MR productivity for the company is 4.5 lakh / month. On the chronic business side, its about 3.5 lakh / month - clearly there is a lot of headroom to improve the productivity here
Company’s share of Chronic business is low at present @ 18 pc. There is a huge scope of improvement here. Expect it to cross 20 pc in next 2-3 yrs
Total MR strength for the company is around 12000
Trade generics contribute to around 20 pc of company’s India business
Company is working on another 5 biosimilars to be launched in India under its subsidiary - ENZENE
Cash on books - in all likelihood to be used to inorganic acquisitions - specially in the Chronic segment. Actively looking out for the same
Company is setting up a new business division - to manufacture medical devices. Will update investors as the business goes commercial. Focus here will be on the domestic Mkts to begin with
Disc: holding, Biased, Not SEBI registered
Alkem Labs -
Q1 FY 25 Concall and results highlights -
Revenues - 3031 vs 2967 cr
Gross margins @ 64 vs 59 pc ( huge expansion )
EBITDA - 608 vs 389 cr, up 56 pc ( margin @ 20 vs 13 pc !!! )
PAT - 545 vs 286 cr, up 90 pc
R&D expenses @ 125 cr, 4 pc of sales
Cash on books @ 3845 cr
Alkem’s rank in major therapeutic segments in IPM -
Anti Infectives - 01
Vit/Minerals - 02
Pain Analgesics - 03
GI - 03
Among the chronic therapies, Alkem is ranked 7th in Neuro, 15th in Anti-Diabetic and Respiratory, 20th in Derma and 26 th in Cardiac segments
Breakup of revenues -
India sales - 2022 cr, up 6 pc ( 67 pc of total sales )
International sales - 967 cr, down 4 pc
Out of this, US sales @ 641 cr, down 8 pc
RoW sales @ 326 cr, up 2 pc
Massive improvement in Gross and EBITDA margins on the back on sharper focus on profitability, favourable RM cost environment and cost control initiatives
Will continue to invest aggressively towards future growth opportunities ( basically ENZENE’s Biosimilars plant in the US which is likely to turn profitable only in FY 27. Company is spending 400-450 cr towards this facility ). These are likely to entail operational costs. Hence sticking to full yr’s EBITDA margin guidance of 18 pc for FY 25. However, if the API prices continue to remain soft and decline further, company may report higher margins
Domestic growth in Q1 is driven by volume growth of 1.5 pc, new products at 2.5 pc and price hikes of about 2 pc
US generics business is seeing price erosion in single digits
Guiding for an R&D costs at around 4.5-5 pc of sales for FY 25
Looking at single digit growth from US mkt in FY 25. Will be launching 3-4 products and filing for 8-10 new products for US in FY 25
Expecting the growth to pick up in a significant way in the European + EMs. These mkts are showing encouraging signs and company is hopeful of growing briskly and more profitably ( vs US ) here. These Mkts are a big focus area for the company. Q1 was weak because of some supply chain issues which now stand resolved. Guiding for a mid teens kind of growth from non-US International business for next 2-3 yrs. Blended margins in these international mkts are > US and < India
Trade generics contribute to around 20 pc of company’s India business
Tax rate guidance for FY 25 @ 11-13 pc
Share of Chronic therapies in company’s India business @ 19 pc. 81 pc is acute business
Medical devices, OTC products - are two business areas where the company is working hard. Will share updates with shareholders when they finally launch products in these spaces
Cash on books to be used for acquisitions / mergers etc to add value to the business
ENZENE Biosciences ( a subsidiary ), already has 07 biosimilars in the IPM. Aim to launch 05 more over the medium term. Their US facility ( under development ) will be utilised for contract manufacturing
Disc: holding, biased, not SEBI registered, not a buy/sell recommendation
Alkem Labs -
Q2 FY 25 results and concall highlights -
Revenues - 3414 cr, down 0.7 pc
Gross Margins @ 64.7 vs 61.4 pc
EBITDA - 752 cr, up 0.8 pc ( margins @ 22 vs 21.7 pc )
PAT - 688 cr, up 11 pc YoY
R&D expenses @ 147 cr, @ 4.3 pc of sales
Segmental sales -
India - 2461 cr, up 5.7 pc ( representing 73 pc of company’s total sales ). Company’s volume growth was at 1.1 pc. Company continues to maintain No 1 position in Anti-Infectives, No 2 position in Vit/Minerals, No 3 position in GI and Pain/Analgesics portfolios. Company is ranked No 5 in the IPM
International sales - 918 cr, down 13 pc ( 17 pc of company sales come from US mkts and 10 pc come from RoW mkts ). US sales de-grew 22 pc to 597 cr. RoW mkt sales grew 12 pc to 320 cr. Launched 1 product in US mkt and received 5 new approvals
H1 Highlights -
Revenues - 6446 cr, up 0.6 pc YoY ( India sales @ 4483 cr, up 6 pc. International sales @ 1885 cr, down 9 pc. US sales de-grew 15 pc in H1, RoW mkts grew 6 pc in H1 )
Gross Margins @ 64.5 vs 60.6 pc ( significant jump )
EBITDA - 1361 cr, up 20 pc ( margins @ 21.1 vs 17.7 pc - significant jump )
PAT - 1233 cr, up 36 pc
Company’s BADDI facility was inspected in Mar 24, EIR received in Jun 24
Going to launch 1 product in US in Q3 for which they have received 180 days exclusivity
US business in H1 faced supply chain issues due to which company lost some volumes. Also there was price erosion. Expecting a much better H2 in the US business. Expect to end FY 25 with mid single digit de-growth in US business
Company has been very selective wrt products that they sell in US. This meant that they did forego some thin margin product sales. This has helped them improve profitability ( H1 profitability in this FY has been better than LY in US despite the sales decline )
IPM breakdown of Acute : Chronic is about 62 : 38. But for Alkem, its about 81 : 19. Acute business has been slow this Q2. Hence company’s growth in IPM has been 1 pc lower than the mkt in Q2
Company expects much better growth in H2 vs H1 in the India business as well
Enzene’s Biosimilar plant ( their subsidiary ) in US should go commercial in Q1 FY 26 ( have spent 400 cr on the same ). Seeing good enquiries + Orders to be made from this facility. Will share more details at an appropriate time. This facility will focus on CDMO operations
Guiding for mid single topline growth for FY 25 with EBITDA margins in the vicinity of 19 pc for full yr
US mkt seeing 6-7 pc kind of price erosion
Company hopes that their Biosimilars CDMO plant should break even in FY 26
Company’s subsidiary - MedTech ltd’s plant should also go live sometime in Q3. It will manufacture Hip and Knee replacement implants under license from Exatech US. They should be able to launch their products in the mkt by Q1 or Q2 next FY
Commercialisation expenses for both these plants ( MedTech and Enzene ) should start flowing into P&L wef Q3
Lower sales in US + Lower API prices have helped company improve their Gross Margins in H1. As the RoW sales pick up, they should also support the Gross Margins
Company also has a domestic Biosimilars business. Have commercialised 7 products in India. Aim to commercialise 3-5 products globally ( including US ) in next 3-4 yrs
In IPM, company’s focus is to grow their Chronic therapies. For the next 3 yrs, should grow at rates significantly higher than therapy growth rates in India - that should increase company’s chronic mkt share
Aim to keep improving company level EBITDA margins by 100 bps every passing yr for foreseeable future. If company happens to make some acquisition that’s margin accretive ( as they have aprox 4000 cr of cash on books ), the improvement may be even faster
Company is also bullish about their RoW business. As time passes and the scale of RoW business increases, that should be another trigger for margin improvement
India business split @ 80:20 between Branded : Trade generics. Even the margins in trade generics are also improving because of better product mix
Company has 145 approved ANDAs in US. Out of these, 100 products are currently active in US
Company will be launching Mirabegron ( used to treat over active bladder ) in US in FY 27 as per their agreement with the innovator
Disc: holding, inclined to add more, biased, not a buy/sell recommendation, not SEBI registered
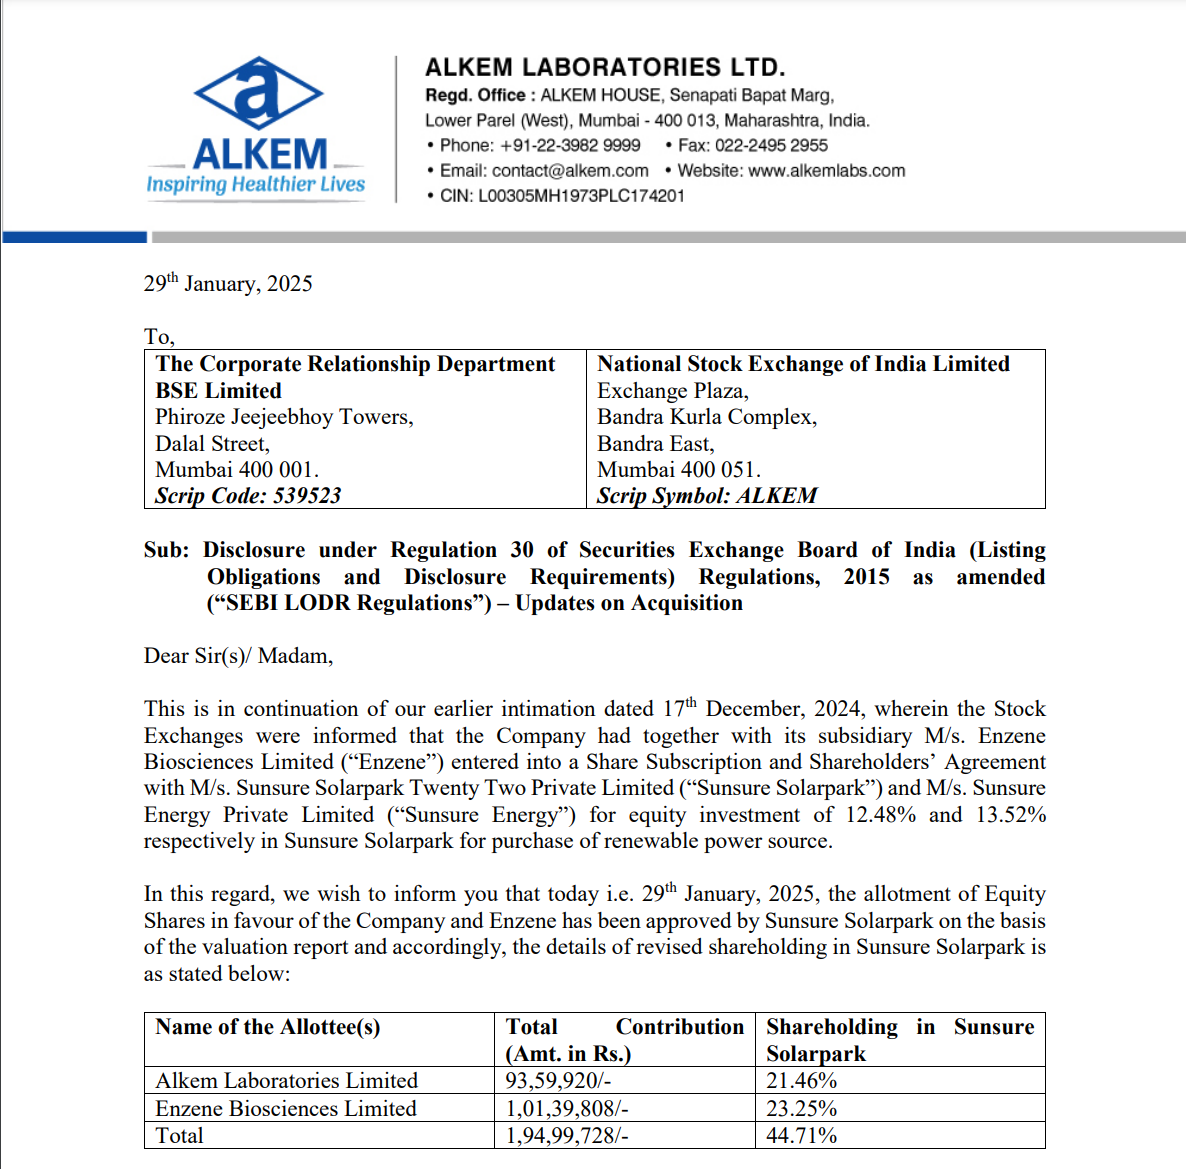
Company, along with its subsidiary Enzene Biosciences Limited, entered into a Share Subscription and Shareholders’ Agreement with Sunsure Solarpark Twenty Two Private Limited and Sunsure Energy Private Limited to invest 12.48% and 13.52% equity, respectively, in Sunsure Solarpark for the purchase of renewable power.
From Q3FY25 Concall
Financial Performance
- Total Revenue: ₹3,374 Cr, up 1.5% YoY .
- India Sales: ₹2,364 Cr, showing 5.9% YoY growth .
- International Sales: ₹960 Cr, experiencing a 6.2% YoY decline .
- EBITDA: ₹759 Cr, with a 22.5% margin , marking a 7.3% YoY increase .
- R&D Expenses: ₹131 Cr (3.9% of total revenue).
- Net Profit: ₹625 Cr, up 5.2% YoY .
- Market Performance: According to IQVIA, Alkem registered a 6% YoY growth , slightly lagging behind the 7.2% growth of the Indian Pharma Market (IPM).
9M Performance
- Revenue: ₹9,820 Cr, up 0.9% YoY .
- India Sales: ₹6,848 Cr (6.0% YoY growth ).
- International Sales: ₹2,846 Cr (7.7% YoY decline ).
- EBITDA: ₹2,120 Cr, EBITDA margin at 21.6% , a 15% YoY increase .
- Net Profit: ₹1,859 Cr, 23.8% YoY growth .
- Market Performance: Alkem registered a 6.9% YoY growth in 9MFY25, compared to IPM’s 8.0% growth .
Operational Highlights
Domestic Business
- Domestic sales accounted for 71.1% of total revenue, up from 68.6% last year.
- Outperformed in seven key therapy areas , including VMN, Anti-Diabetic, Gastrointestinal, Neuro/CNS, Gynae, Respiratory, and Urology .
- PAN-D was the fastest-growing brand in the IPM top 12, with a 15.5% growth rate .
- Volume growth of 1.1% despite a sluggish market (0.3% volume growth for IPM).
International Business
- US business contributed 19.1% of total sales in Q3FY25.
- Other international markets contributed 9.8% .
- Received two approvals from the USFDA during Q3, including one tentative approval.
- Chile market downturn due to tender exits and currency depreciation, leading to 30% degrowth ; stabilization expected in Q4.
Business Performance & Insights
- Trade Generics Business: ₹488 Cr in Q3FY25, totaling ₹1,378 Cr YTD.
- Forex Impact: Positive; every 1% appreciation in USD adds ₹10-20 Cr .
- NLEM Portfolio: Accounts for 30% of sales, limiting price growth opportunities.
- Enzene Biosciences: ₹200 Cr YTD sales, projected to close FY25 at ₹300 Cr , targeting 15-20% growth next year.
Strategic Moves & Acquisitions
Product Pipeline & New Launches
- India: First wave of GLP-1 Semaglutide launch.
- US: Key approvals include Sacubitril-Valsartan, gSuprep, and Carbamazepine ER .
- Upcoming US Launches: Topiramate oral solution and Varenicline .
- Filings: Three filed till Q3 in the year, expecting five more in Q4.
Acquisitions & Expansion
- Adroit Pharma (Dermato-cosmetology) : ₹140 Cr acquisition to expand into the dermatology segment.
- Bombay Ortho (Orthopedic Implants) : ₹147 Cr acquisition; manufacturing capacity of 2,000 hip & knee replacements/month .
- Exactech (Ortho Business Entry) : ₹133 Cr licensing deal for premium hip & knee implants, launch set for Dec 2025 .
Challenges & Risks
- Forex Loss: Booked ₹20 Cr loss due to Chilean currency depreciation in Other Income.
- Price Erosion in US: Mid-single-digit price erosion (~5%), expected to be offset by new launches & volume growth .
- NLEM Portfolio Pressure: Zero price growth in large parts of the portfolio, requiring a volume-driven growth strategy .
- Acute Therapies Slowdown: Market-wide slowdown in Q3 (5.7% growth), but Alkem expects a stronger Q4.
Guidance & Management Outlook
- Domestic Market Growth: 7% for FY25.
- International Business: Expected 13-14% growth .
- US Business Q4: Expected to remain flat YoY .
- EBITDA Margin Guidance: Q4 margin to be lower than Q3 (~13.7%).
- Big Acquisition Plans: Management is prioritizing Indian formulations expansion .
Alkem Labratories -
Q1 FY 26 results and concall highlights -
Revenues - 3371 vs 3031 cr, up 11.2 pc
Gross margins @ 65.3 vs 64.5 pc
EBITDA - 739 vs 608 cr, up 21.4 pc ( margins @ 21.9 vs 20.1 pc - significant margin expansion )
Exceptional gain - 129 cr ( due sale of company’s Indore facility )
PAT - 664 vs 545 cr, up 21.8 pc
Q1 R&D spends @ 118 cr ( 3.5 pc of sales )
Cash on books @ 4870 cr
Company’s segmental performance -
Domestic business -
Revenues - 2265 vs 2022 cr, up 12 pc. Domestic sales contributed to 68 pc of company’s sales. Volume growth @ 2.9 pc vs Mkt’s volume growth @ 1.5 pc
Domestic growth was led by - anti-infective which grew @ 6.5 pc, GI @ 10.5 pc, Vit+Minerals @ 18.1 pc, Pain management @ 9.2 pc, Neuro @ 11.6 pc
Company’s rank ( in IPM ) in their core therapies -
Anti Infectives - 1
GI - 3
VMN - 2
Pain / Analgesics - 3
Neuro - 7
US Business -
Revenues - 698 vs 641 cr, up 8.8 pc. US business contributed to 21 pc of company’s consolidated sales. In Q1, company filed its first Biologics License application in US. In addition, received 5 ANDA approvals, launched 3 ANDA products
RoW business -
Revenues - 355 vs 326 cr, up 9 pc. RoW sales contribute to 10 pc of company’s consolidated sales. Sales growth in RoW mkts was driven by Aus + EU mkts
Total field force @ 12,500
Company is a leading player in Trade generics segment
18 of company’s brands in India clock revenues > 100 cr
Company’s RoW business margins are much better than their US margins. Company is now focussing on growing the RoW pie with renewed thrust
IPM breakdown of Acute : Chronic is about 62 : 38. But for Alkem, its about 81 : 19. 30 pc of company’s domestic business is under NLEM
Company has been improving their margins in the trade generics segment. Their margins in this segment are now very close to their corporate avg EBITDA margins. Growth in trade generics business is generally a function of growth in the acute therapies
If the Q2 performance is also good ( like Q1 ), company may up their FY 26 EBITDA margin guidance given earlier of 19 - 20 pc
Company expects MedTech business to start breaking even starting FY 28
R&D spends are expected to be much higher in H2
Actively looking at inorganic acquisitions in the Chronic space ( as the current business is heavily lopsided towards Acute therapies )
Capex planned for FY 26 @ 750 cr
Adroit Biomed ( acquired in LY ) clocked Q1 revenues of 15 cr
Aim to keep improving the consolidated business’s EBITDA margins by aprox 100 bps / yr till they hit 25 pc kind of EBITDA margins
Looking to commercialise their first Biosimilar in US towards the end of FY 27
Enzene clocked revenues of aprox 90 cr in Q1
Tax rate for full FY should be around 13 pc
Disc: holding, biased, not SEBI registered, not a buy/sell recommendation, posted only for educational purposes
Alkem Labs -
Q3 FY 26 results and Concall highlights -
Revenues - 3736 vs 3374 cr, up 10 pc
Gross margins @ 65.9 vs 64.3 pc
EBITDA - 828 vs 759 cr, up 9 pc ( margins @ 22.2 vs 22.5 pc )
Exceptional charges @ 53 cr - on account of implementation of new labour codes
PAT - 636 vs 625 cr, up 1.6 pc
Domestic business -
Revenues @ 2495 vs 2364 cr, up 5.5 pc - representing 67 pc of company’s consolidated sales. Company’s secondary sales grew @ 10.9 pc vs 9.8 pc growth reported by IPM. Their secondary acute and chronic sales grew by 8.8 and 15.8 pc respectively ( both segments outperforming the IPM by a small margin )
Company’s brands with sales > 500 cr @ 2
Company’s brands with sales > 150 cr @ 12
Company’s brands with sales > 50 cr @ 12
US Business -
Revenues - 753 vs 634 cr, up 19 pc - led by new launches + volume growth in existing portfolio. US sales represent 20 pc of company sales
RoW business -
Revenues - 462 vs 326 cr, up 42 pc. This business represents 12 pc of company’s sales and is their fastest growing business. In Q2, RoW growth was @ 32 pc
Alkem’s Subisiadry - Alkem MedTech announced the acquisition of Occlutech ( Switzerland based MedTech company ) for 1074 cr for 55 pc stake. They make Cariac implant devices ( Occluders ) - delivered without an open heart surgery ( via a catheter ). Their LY’s revenue was @ 534 cr, growing @ 16 pc CAGR for last 3 yrs with EBITDA margins @ 7-8 pc. Alkem is confident of driving these margins to as high as 23-24 pc in next 3-4 yrs using their existing infra in GCC region. Occlutech currently has minimal presence in developing mkts. Alkem sees this as a key growth opportunity. Alkem Medtech is currently into Ortho Implants only. This acquisition vastly expands their tgt mkt. Company aspires to clock 1000 cr kind of revenues with 23-24 pc kind of margins from their implants business in next 3-4 yrs. Their current revenue run rate from cardio + ortho implants is @ 534 cr + 15 cr
Enzene ( their BioTech subsidiary ) clocked sales of 360 cr for FY 25. Here again, company aspires to clock EBITDA margins > 20 pc in 4 yr’s time
Cash on books ( adjusted for Occlutech Acquisition’s outgo ) @ 4500 cr - still very healthy
Continue to grow ahead of the mkt in Derma, Respiratory and Anti-Diabetic categories. Company is as such very strong in Pain management, Anti Infectives and VMN segments
Plan to invest another 200-300 cr in their consol MedTech business over next 3-4 yrs ( bulk of investments have already been made )
Occluder - is a minimally invasive, catheter-delivered implant used to seal holes or abnormal connections in the heart, such as Atrial Septal Defects (ASD), Patent Foramen Ovale (PFO), or Ventricular Septal Defects (VSD). Usually made of nitinol mesh and polyester, they allow tissue growth over the device, eliminating the need for open-heart surgery
Occlutech has a loan on books of around 450 cr @ interest rate of 10 pc. Post Alkem’s takeover, this rate of interest should come down meaningfully ( backed by their corporate guarantees )
Another product under development - LAA ( Left Arterial Appendage Occluder ) - is a crown jewel in Occlutech’s pipeline - helps prevent heart strokes due clot formation in Left Atrial Appendage. Once ready - they intend to launch it in EU mkts to begin with
Company’s chronic portfolio continues to do well in the IPM - a key positive ( also critical from company’s PoV to maintain this growth )
Have launched Semaglutide ( in Mar last week ) under the brand names - Semasize / Hepaglide / Obesema - costing Rs 450 / week for the treatment
Should be able to grow the India business in double digits in Q4 ( going by the demand trends seen in Jan )
Trade generics is a large business for Alkem labs. Their focus on this segment shall always remain sharp
Should be able to clock 14 pc CAGR wrt Occlutech’s business ( includes geographical expansions but doesn’t include launching new products like LAA, PFO Occluders )
Another prominent product under development @ Occlutech is PFO Occluder. Patent Foramen Ovale - it’s an opening in the wall between left and right Atria. This opening, if too big can cause heart strokes
IQVIA data doesn’t cover the trade generics businesses
Company’s trade generics business grew in low single digits in last 3 Qtrs - mostly deliberate as the company was restructuring their trade generics vertical in current FY
Disc: hold a small tracking position, not SEBI registered, biased, posted only for educational purposesDisc: hold a small tracking position, not SEBI registered, biased, posted only for educational purposes