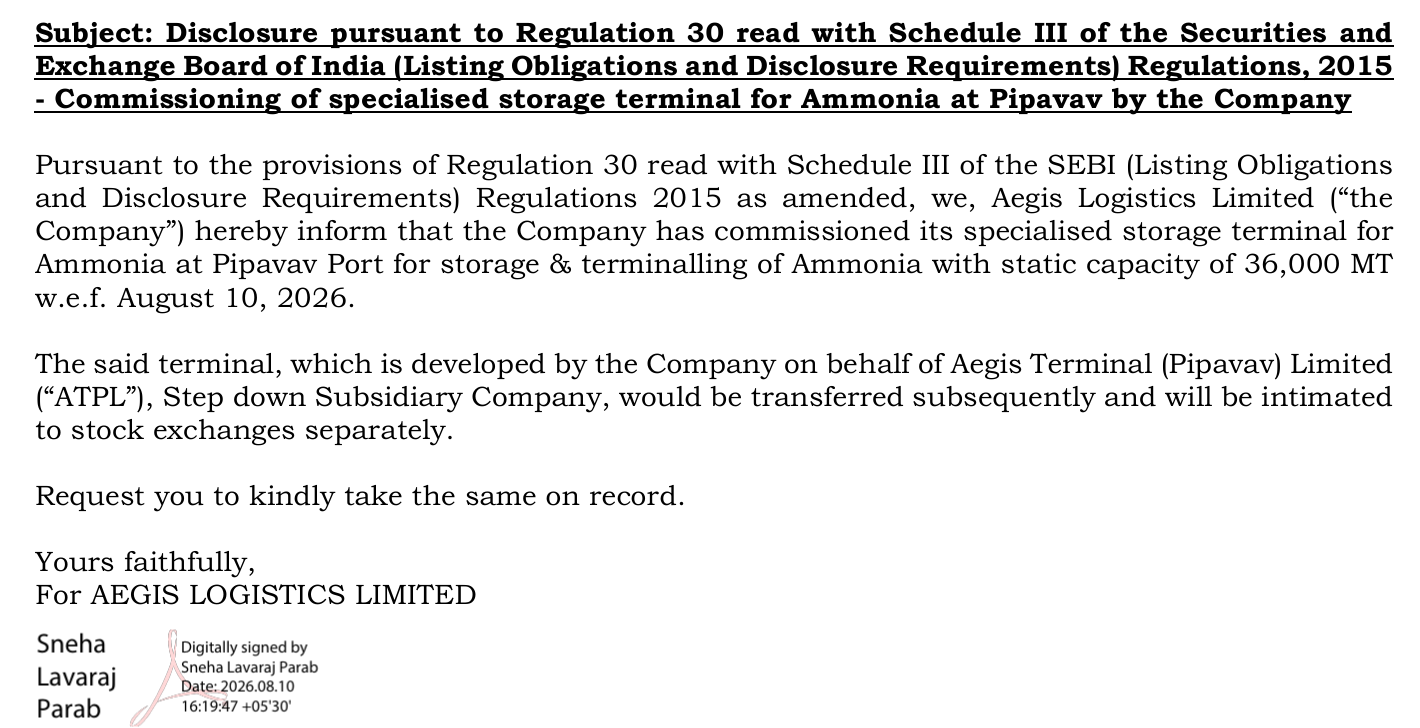
Ammonia comes online in H1FY27. Notice - Commissioned its specialised storage terminal for Ammonia at Pipavav Port
2 Likes

I assume discussions may be on, but management is unlikely to officially confirm anything until there is some form of agreement or the deal is finalized. Let us wait and see what emerges from the negotiations.
AEGIS FUND RAISING ANNOUNCEMENT.pdf (265.3 KB)
It seems the talks between Aegis Logistics Limited and Tristar group UAE have been definitive.I have compared using “Gemini” ,Aegis and Tristar group’s 3 year financials. below is a snapshot.
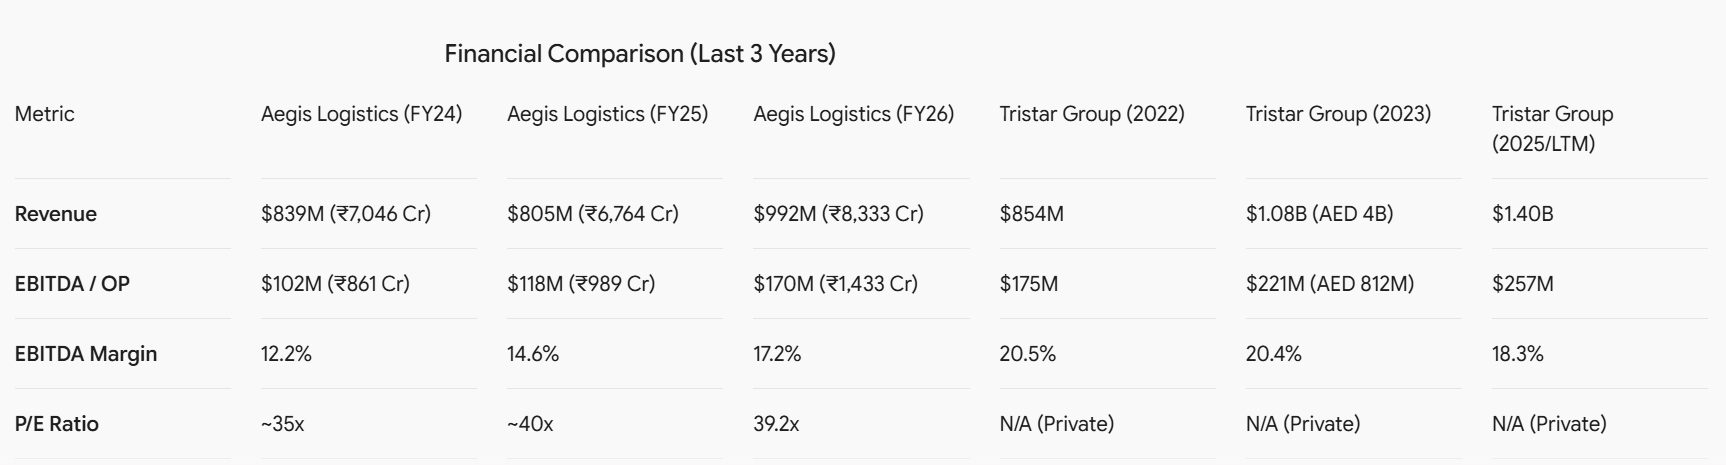
I have assumed a 10% equity diluton for Aegis. Following is the outcome in that case:
Merger Synergies & Margin Accretion
Synergies
A merger combines Aegis’s dominance in Indian LPG handling and gas distribution with Tristar’s global footprint in maritime fuel farms and liquid logistics. Tristar operates in over 30 countries and handles major peacekeeping contracts for the UN, as well as energy logistics for Abu Dhabi National Oil Company (ADNOC) and Total SA. The combined entity would create a fully integrated supply chain across West Asia and India, reducing reliance on third-party shipping charters, optimizing procurement logistics, and shielding operations from regional geopolitical volatility.
Margin Accretion
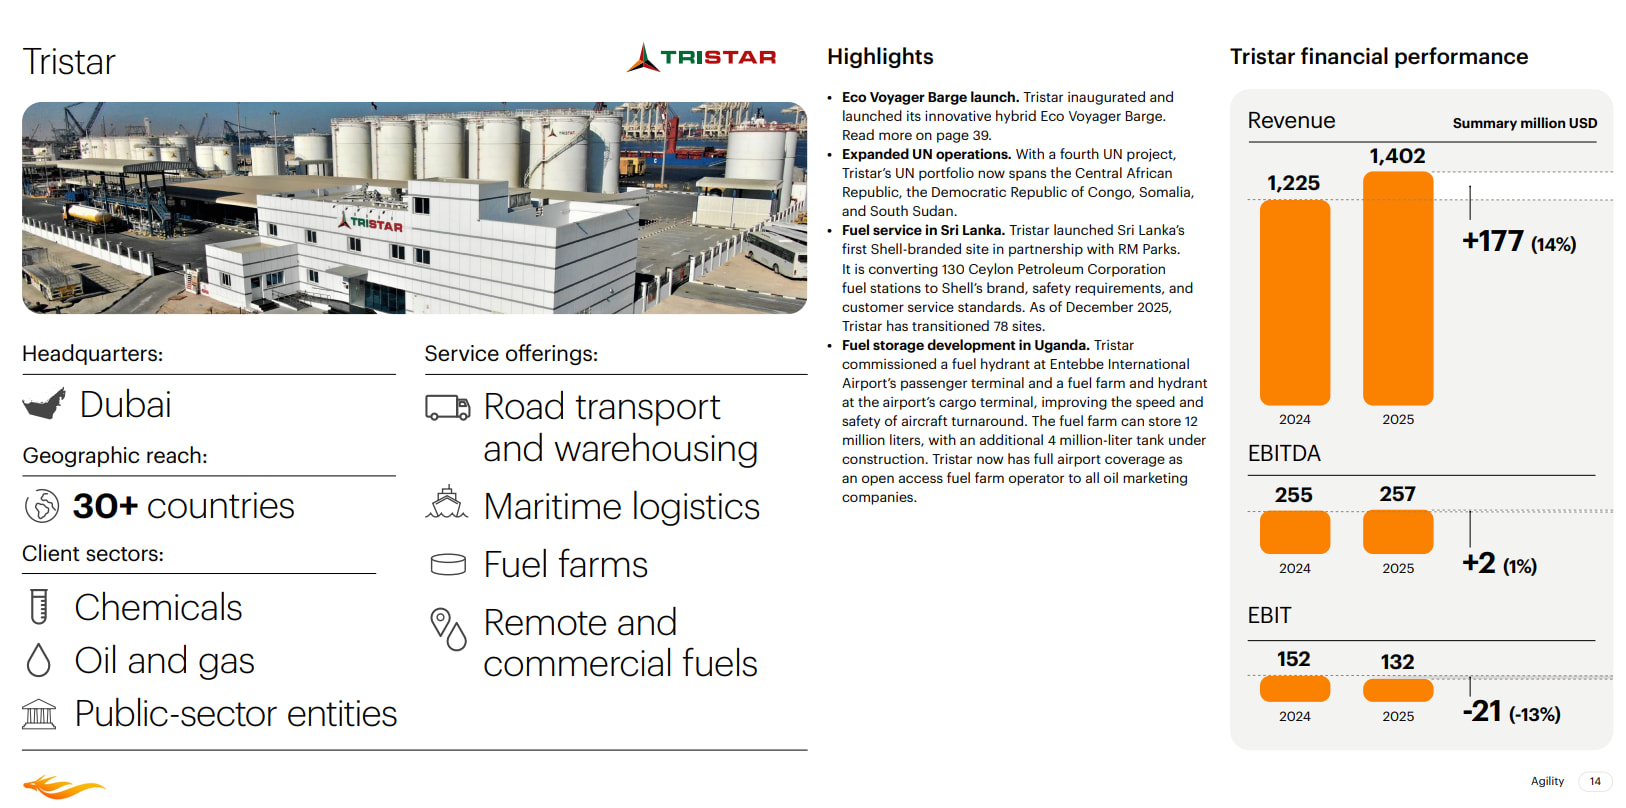
An acquisition of Tristar would be highly margin and EPS accretive for Aegis Logistics. Tristar consistently generates higher absolute EBITDA ($257 million vs. Aegis’s $170 million) and operates at robust historical EBITDA margins of 18–20%, which blends favorably with Aegis’s 12–17% margins. Furthermore, Aegis trades at a high market multiple (~35x EV/EBITDA), whereas Tristar is being negotiated at an implied buyout valuation of ~$1.5 billion—equating to a highly discounted ~5.8x EV/EBITDA multiple. Absorbing a highly profitable, lower-multiple target immediately boosts consolidated earnings per share.
Tristar Group LBO Valuation Estimate (10% Dilution)
To determine the implied Leveraged Buyout (LBO) Enterprise Value of Tristar Group based on a 10% equity dilution constraint from Aegis Logistics:
-
Equity Contribution: Aegis Logistics currently commands a market capitalization of roughly $5.9 billion (₹49,745 crore). A 10% equity dilution yields an equity financing pool of $590 million.
-
Debt Structure: The transaction structure involves Aegis taking on or refinancing Tristar’s existing debt of $600 million, while raising an additional $400 million to $500 million in new acquisition debt. Taking the midpoint for new debt ($450 million), the total debt load equals $1.05 billion.
-
Implied Enterprise Value: Combining the debt and equity components ($1.05 billion + $590 million) results in an LBO valuation of $1.64 billion.
This implied $1.64 billion LBO target value closely aligns with recent negotiations pricing the deal near $1.5 billion. At this structure, the acquisition would value Tristar at a 6.3x multiple on its recent $257 million EBITDA.
3 Likes
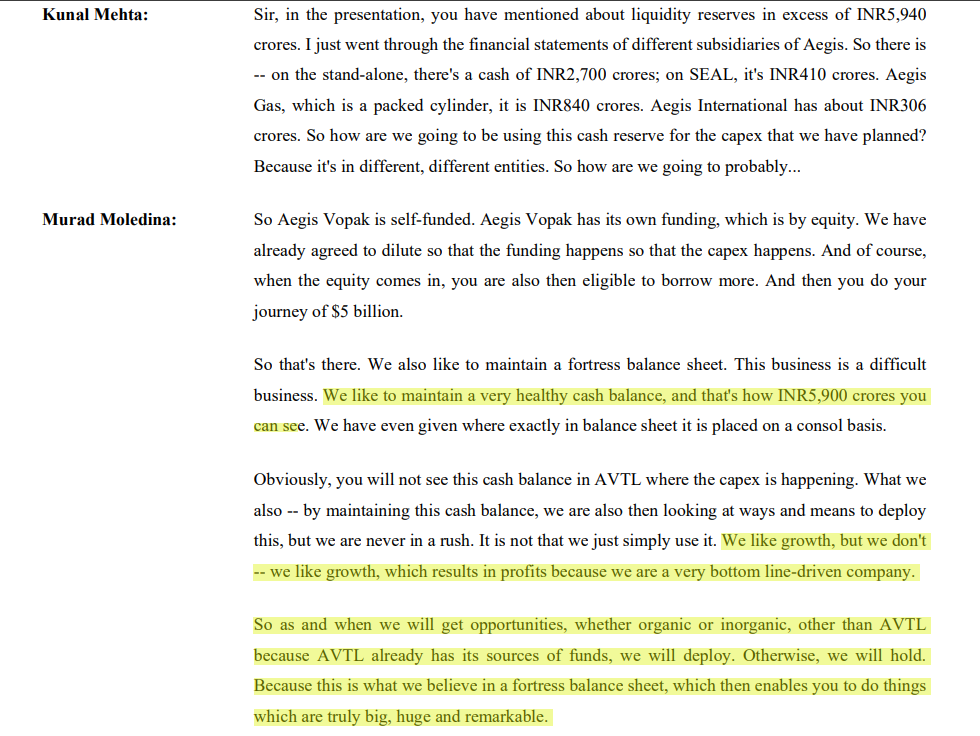
Q1 FY27 concall: management highlighted strong cash reserves and said they are looking for opportunities, both organic and inorganic.
Aegis Logistics had liquidity reserves of around 5900crs as of Mar’26. For FY27, assuming cash flows similar to FY26 and interest income of 400-500crs on these reserves, we can expect cash reserves of around 7000-7500crs. On this basis, the company may need an additional 8000crs to fund this deal – through equity dilution, debt, or a combination of both.
The merged entity is estimated to have EBITDA of ~4500crs and EV of ~58000crs, implying an EV/EBITDA of 12-13x.
Is Aegis Logisitics taking over Tristar or is it under AVTL?
as per media sources, it is Aegis Logistics.
Aegis Logistics has approved fund raise of up to 6,000crs through equity shares, NCDs, preferential issues or other financial instruments.
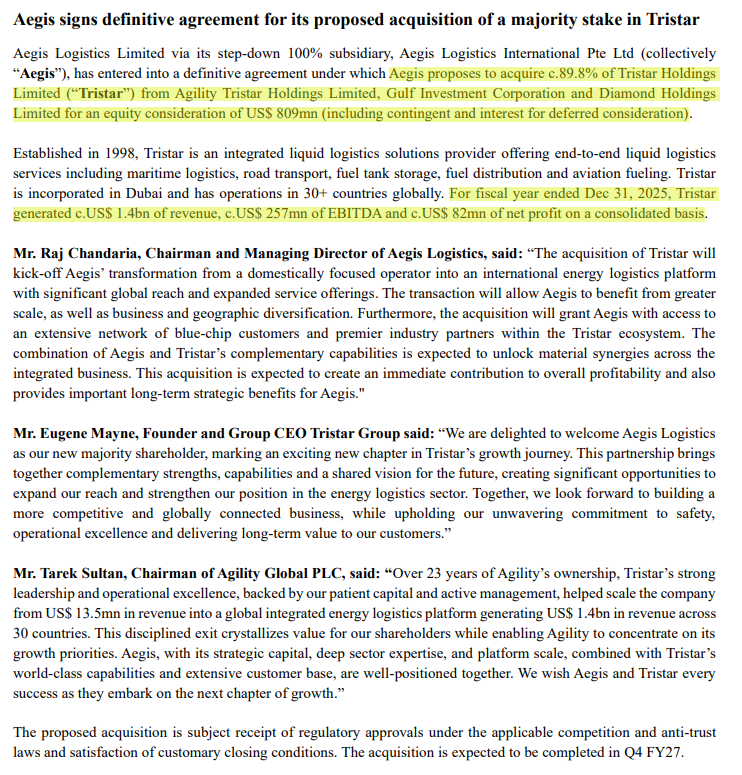
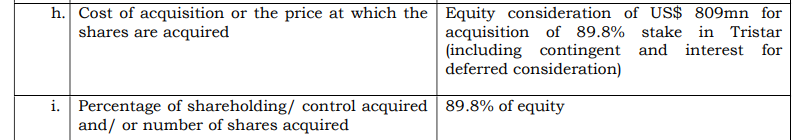
809 million usd for 89% seems much better than 100% for 1.5billion usd.
1 Like