Just an update on the recent promoter buying.
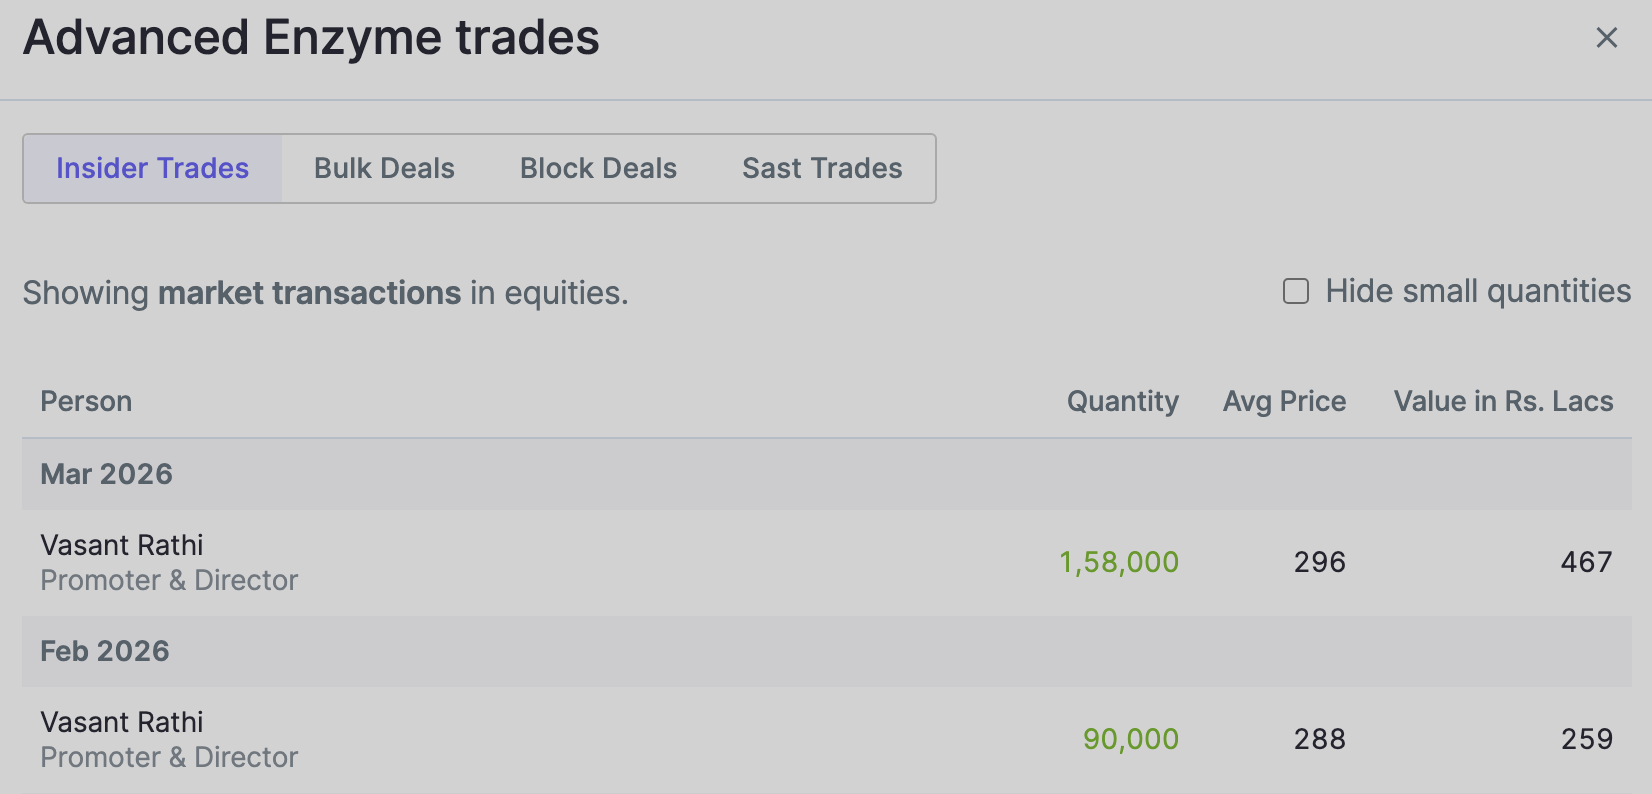
Recently took a 2% allocation after seeing this.
Will track it closely after the coming quarterly results.
Sharing my thoughts on Advanced Enzymes, would love to get feedback. Feel free to point out inaccuracies, or help me improve my understanding.
Starting with optionality…
1. EU sales could increase with the new approvals and eVoxx starts to support sales of products, in addition to continuing R&D.
2. Acquisition a strong possibility, done in past, acquisition of JC Biotech, SciTech, eVoxx.
3. Growth in US business a possibility, but will take some time (“Mr. President is busy”).
4. Bio-Catalysis for API mfg, under trial with a few customers, is a focus area.
5. Working on a few products/solutions already. New R&D center will help develop more products.
6. Probiotics, working on new products, market is highly competitive, but is also big.
7. Wellfa, B2C business, lots of trials and errors may happen, B2C can be a difficult business, have a dedicated team which is a good sign, shows focus, but challenging.
8. Novel Food Ingredient in EU (Serratiopeptidase)…time consuming and very difficult approval process, but once approved, will grow well in couple of years post approval.
Now some numbers…
EV = 3150 (mcap) + 20 (borrowings) - 600 (cash+investments) = 2570 Cr
CFO = 140Cr
EV/CFO = 2570/140 = 18.3 (for a business which converts 70% of Operating profits to CFO but is not growing, this number is not cheap, but acceptable. If going forward there is growth, then current valuation starts to look cheap).
EBIDTA = 200 Cr.
EV/EBIDTA = 2570/200 = ~ 13 (Its cheap for a 30% margin business, which is debt free, has superb balance sheet with cash which is conserved for acquisition, and does not need lots of cash for regular capex).
Net profit for FY’26 could be between 145 to 155 Cr.
EV/Earnings = 16.5 to 17.7
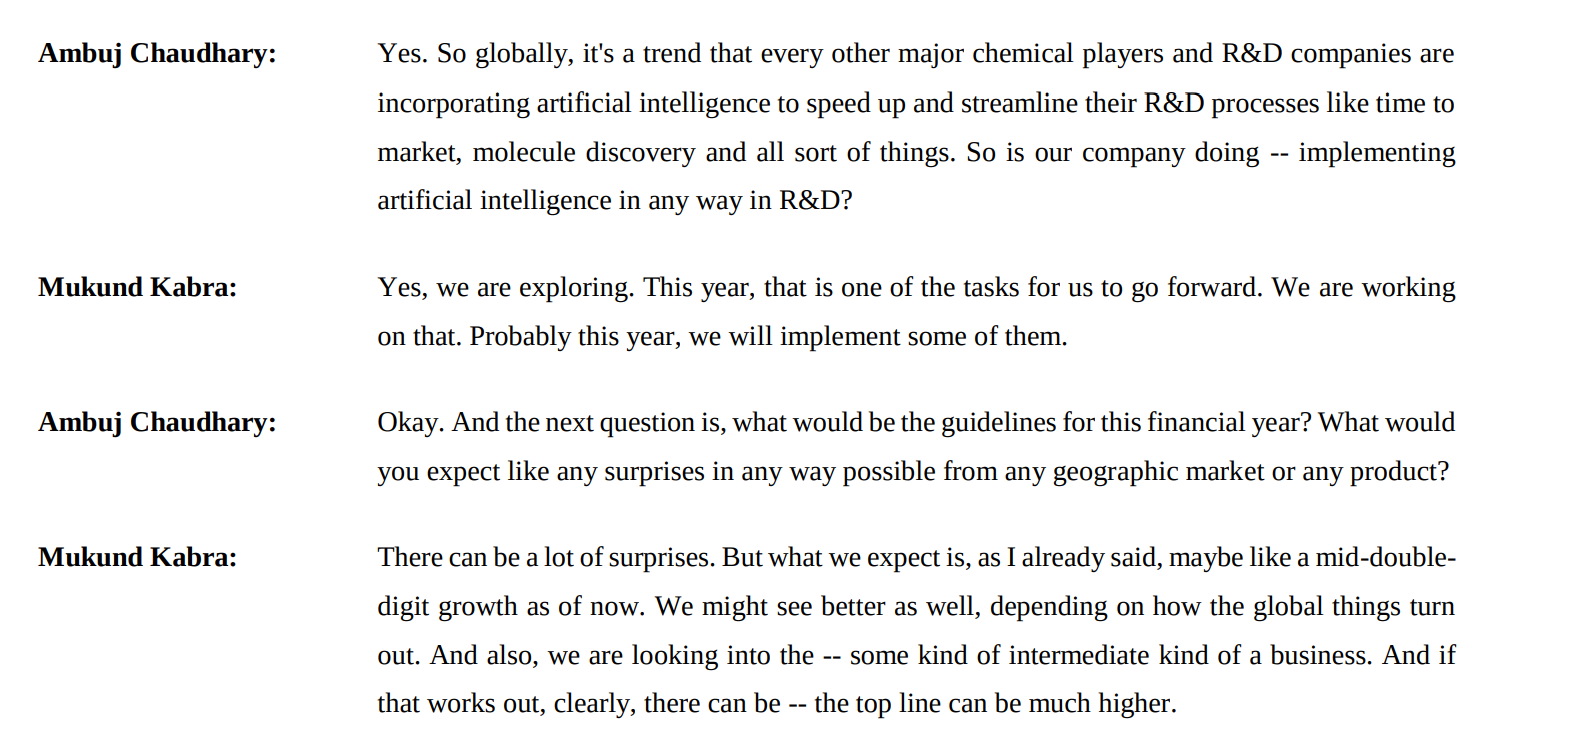
So the business is reasonably priced, but if there is no growth, then can be a value trap. Having said that, there are multiple levers of growth. Management has hinted at possibility of surprises, so I am inclined to believe some positive developments will happen, will look for some concrete developments in the upcoming quarters.
Disc: Invested, biased
They have been saying it for some time now. A lot of R&D - not sure for what? last 5y sales 7%, last 5y PAT 0%
Sr. VP and Marketing head resigned this month.
I agree nothing new seems to be coming out of R&D, but at the same time their approval process is also long. For example EU is pretty strict with approving. The Novel Food Dossier that they have submitted, that is taking very long time, and one doesn’t even know if the approval will come through. If you look at the total EU contribution, its pretty low at 6%, and that has not improved in the last 5 yrs. But this year hopefully it will do better.
Also if we see their segments other than Human Nutrition, all are showing slight upward trend, indicating slowly but surely things are improving.
Regarding the resignation of the SVP, people leave, hopefully that shouldnt impact the company.
Interesting results for Q4 and FY26. I was wrong on PAT, they did better (Pulak Prasad said that very few can forecast accurately, most either undershoot or overshoot  ). Overall, good growth after a long time, all 4 segments had good growth. Geo-wise, US is struggling, all other had good growth.
US is mostly the B2B neutraceuticals business and is highly competitive. Mgmt cites tariffs and recent happenings as the reason for stagnation, but over the last 4-5 years it has not improved much, I guess the competitive intensity is too high, still gives good margins though. Nonethless mgmt is positive that growth will come back. US will take time to recover bcos the interest from its customers is subdued.
On the EU approval for their Novel Food Dossier which is their flagship product (Serratiopeptidase), mgmt feels they will get the approval this year, this is a very positive development as once the appproval is given, they will be the only company to sell this product in EU. The ramp up in sales will however take time, so may take couple years post approval to see meaningful contribution in the revenue.
Probiotics currently is very small, but they consider it their strong area. Also they clarified that the reported numbers (which is small) is for the commoditized products, probiotics is used in other segments as well. So if they are strong in probiotics, that could support growth in other segments, example neutraceuticals combined with probiotics, or effervescdent products combined with probiotics.
On Biocatalysis, they mentioned there are multiple products under trial. And while the trials are going on for some time, they need to tweak to get it right. But once they acheive what their clients want, which I feel they will in due course, this will also contribute to growth.
So overall, it feels their growth is slow (we want our businesses to keep growing at 20%+ ), but a lot seems to be happening in the background which is not obvious to us. All of that, one by one, will keep adding…need to have patience.
On acquisition, unfortunately there was no discussion, I too missed to ask, but I have a strong feeling they would do some soon as the cash on balance sheet is not being returned to shareholders.
disc: invested, biased, just sharing my thoughts, no reco.
a couple years back there were chatters on bringing in professional management. I believe ICICI had a note on that. nothing so far has been announced or not even hinted.
I’ve put the business in too hard pile.
The business hasnt demonstrated pricing power and operating leverage to justify the price its trading at. Estranged promoter’s firm seems to have caught up on the major products like serratiopeptidase, so i feel competition will only increase going forward. Management also mentioned in last concall that going forward they won’t be providing segment wise breakup. Acquisition and R&D in past haven’t delivered meaningful returns. No clarity on buyback policy and dividend payout % varies wildly YoY. Might re-enter when price has good margin of safety and management delivers by expanding topline and margin on sustained basis.
You maybe right on pricing power, and the proof of that could be the reduction in margins from 40s to 30s at the operating level. However, change in product mix over period of time could also be the reason. Having said that, I feel there are very few businesses which operate at such high margins.
Regarding operating leverage, they are not operating at high utilization levels currently, they have ample capacity available to scale up any product if required without incurring major capex. So when volumes rise, operating leverage will kick in nicely.
There is a difference in the 2 companies, Advanced Enzymes is more into fermentation and manufacting of the key material, like an API in a formulation, whereas Advenza is into the formulation itself. With time, Advenza could come up with its own fermentation capacities, but for now I guess they are operating in different segments. But competition from other players is indeed there, the mgmt has acknowledged it.
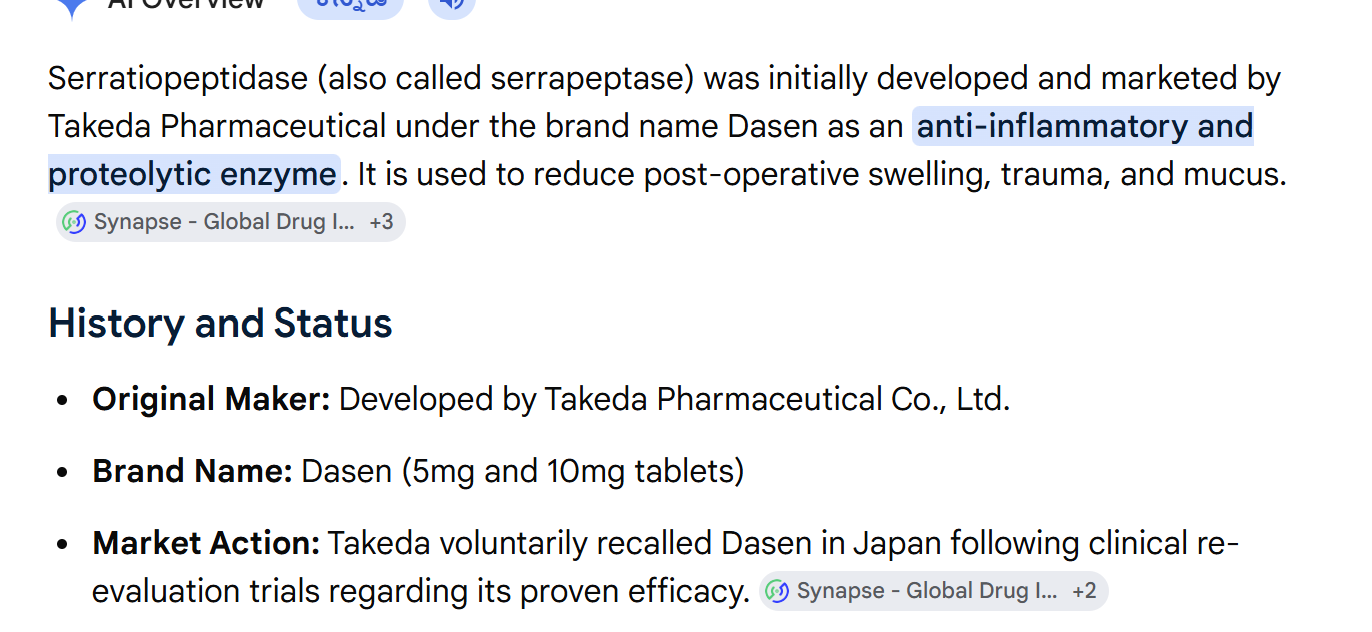
Serratiopeptidase - the main Enzyme’s efficacy produced by the company seems questionable where Japan’s Takeda Pharma took it back from the market voluntarily. The company seems has not address the question regrading the same. Anybosy can throw some light on this?
This is interesting. Serratio is one of the largest contributor to the co’s revenue and profitability. They expect it to continue. Additonally, the novel food dossier filed in EU is also for Serratio. The co is expecting to receive the approval after a long wait, as EU was taking time to evaluate. Once approved, the co would be the only one to supply serratio in EU (till the time another co gets approval, but getting EU’s approval takes time). And to that effect, they’d have this enzyme continue as a large contributor to their revenues, however, the EU ramp up would not be fast as they need to increase awareness.
Serratiopeptidase was withdrawn by the Japanese innovator because post market surveillance studies failed to show efficacy greater than a placebo. This could be because the oral formulation does not provide adequate bioavailability for the drug to be concentrated in the inflammed tissue and have an effect. Another reason is acute inflammation is usually self limiting and so it’s difficult to know for sure if the drug did help reduce it.
The innovator was required by the Japanese regulator to conduct more trials to confirm the results, but the company thought the cost benefit ratio was not favourable and hence decide to withdraw the product instead.
It is still widely prescribed in India (as part of a fixed drug combination with diclofenac). I can tell you, anecdotally as someone who has prescribed serratiopeptidase in the past, that I haven’t seen it reduce inflammation significantly in my patients. But that’s not necessarily strong evidence since it’s highly subjective.
Unless they have done more clinical trials to generate evidence to show efficacy, it is not a given that EU will give approval. I would wait and watch for further updates.
Disclosure: Not invested
Thanks a lot Vivek for your insights. My concern was that if the efficacy is questionable, it is difficult to establish a market. I can even assume that it is safe on humans but questionable efficacy itself for any product restricts the market size in great way. India also in past has restricted many FDFs containing Serratio now I am obviously not sure it was because of Serratio’s efficacy or some other drug or a combination.
Discl : I recently bought.
Can you please share the source, where it’s mentioned that post market surveillance studies failed to show efficacy greater than a placebo. Thanks
I tried finding the research article but apparently they never published the studies in a peer reviewed journal. They presented it to the regulatory body who asked them to conduct more studies. They decide to withdraw the drug from the market instead.
Japan MHLW Drug Re-evaluation Subcommittee minutes, 19 Jan 2011. Three Takeda randomized, double-blind, placebo-controlled trials reported to PMDA in May 2010, all 10 mg three times daily:
- Chronic bronchitis: 311 participants, 2 weeks, sputum clearance. No significant difference vs placebo.
- Ankle sprain #1: 301 participants, 1 week, CT ankle swelling area (only 190 evaluable). No significant difference.
- Ankle sprain #2: 280 participants, 1 week, CT ankle area. No significant difference.
The minutes give no p-values, arm means or tables. Japanese only.
Despite Not Encouraging results why Company is going after legacy molecules !!
Strong results posted in Q2FY27. Best quarterly results ever in terms of topline and PAT. Operating margin also showed a significant improvement.
Disc.: invested