Just looked at SUN TV valuations ( see: Sun TV Network - Investment Thesis )
And thought let me compare ZEE .. valuations rock bottom. is there a case ion unlocked value of parts?
Then saw @suryascoper made a good point of the music and lets compare it with a peer (Tips music) .
| Metric |
Tips Music Ltd (TIPSMUSIC) |
Zee Music Company (ZEE) |
| YouTube Subscribers |
145.3 Million (Network) |
122 Million (Main) |
| Total YouTube Views |
54.5 Billion |
86.7 Billion |
| Annual Revenue (YouTube) |
₹350 Cr ($42M USD) |
₹550 Cr ($66M USD) — Extrapolated* |
| Revenue per 1M Views |
~₹64,200 ($770) |
~₹63,500 ($760) — Estimated |
| Operating Profit Margin |
79% (Industry Peak) |
~18-22% (Group Est.) |
| Catalog Strategy |
90s Nostalgia (High Margin) |
New Bollywood (High Growth) |
**While Zee has more views, their revenue per view is slightly lower than Tips because Zee pays massive “Minimum Guarantees” (MGs) to film producers for new hits, whereas Tips owns its 90s catalog outright with zero ongoing acquisition costs.
If we use Tips Music as a pure-play benchmark to value Zee Music Company (ZMC), the math suggests that the market is valuing the rest of ZEEL’s massive empire - including all its TV channels, ZEE5, and movie studios at almost zero.
- The Benchmark: Tips Music
Tips Music has become a market darling due to its high-margin, asset-light model.
- Valuing Zee Music (The Extrapolation)
Zee Music is significantly larger than Tips in terms of reach (122M+ YouTube subscribers vs Tips’ ~65M) and catalog depth.
- The “Rest of ZEEL” Valuation
Now, let’s look at the actual consolidated Market Cap of ZEEL and subtract our derived value for the music business:
| Asset |
Value (INR Cr) |
| ZEEL Consolidated Market Cap |
₹7,296 Cr |
| Less: Zee Music Implied Value |
(₹10,285 Cr) |
| Residual Value for All Other Assets |
–₹2,989 Cr |
According to this math, the “rest of ZEEL” is being valued at negative ₹2,989 Crore. In simple terms, the market is currently saying that if you buy the music business at a “Tips-like” valuation, someone will pay you ~₹3,000 Crore to take the TV channels, ZEE5, and the movie business off their hands.
What are these “Free” Assets? By buying ZEEL at ₹7,296 Cr, you are essentially getting the following for a “negative” price:
-
Broadcast Business: 30+ domestic channels with an ~18% network viewership share.
-
ZEE5 (Digital): A platform with ₹1,000 Cr+ annual revenue and growing.
-
Zee Studios: One of India’s top film production and distribution houses .
-
Library: 260,000+ hours of television content and 4,800+ movie titles.
-
bonus Cash on Hand: ZEEL maintains a healthy cash balance (approx. ₹2,180 Cr as of late 2025).
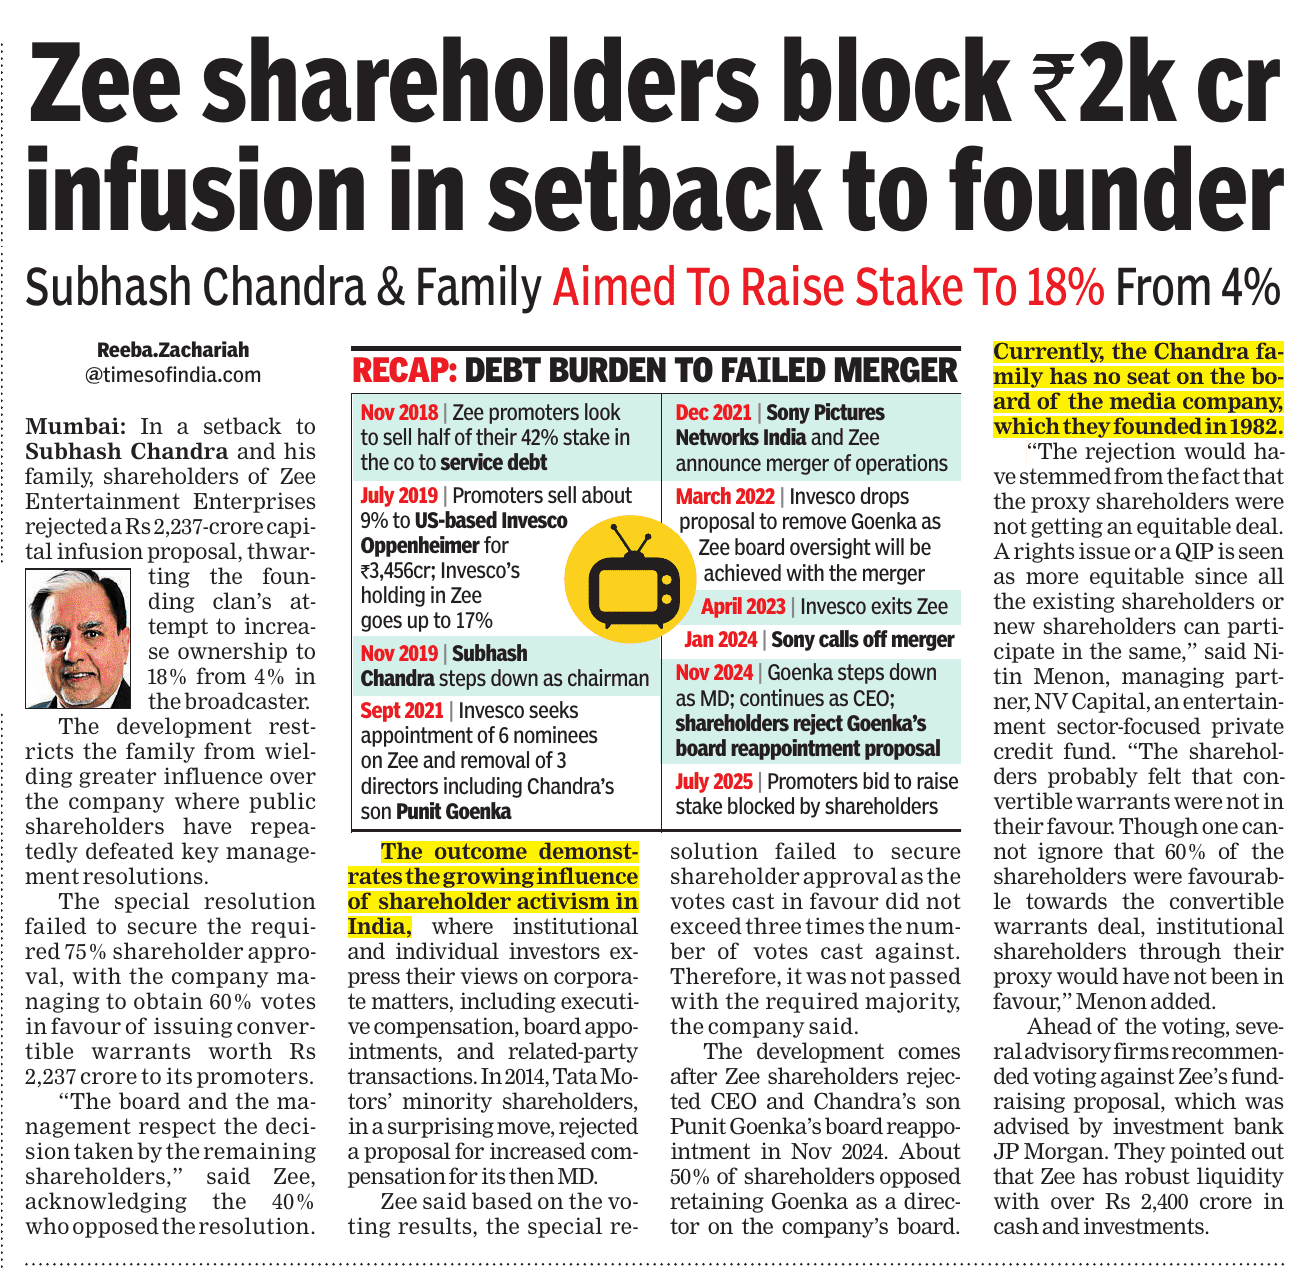
The reason for this “broken” math is obviously past failed merger and litigation overhangs.
But is market gone overboard in downgrading ZEE business because of the failed merger with Sony?