Waaree Energies Ltd Q2 FY26 Result and Concall Analysis
-
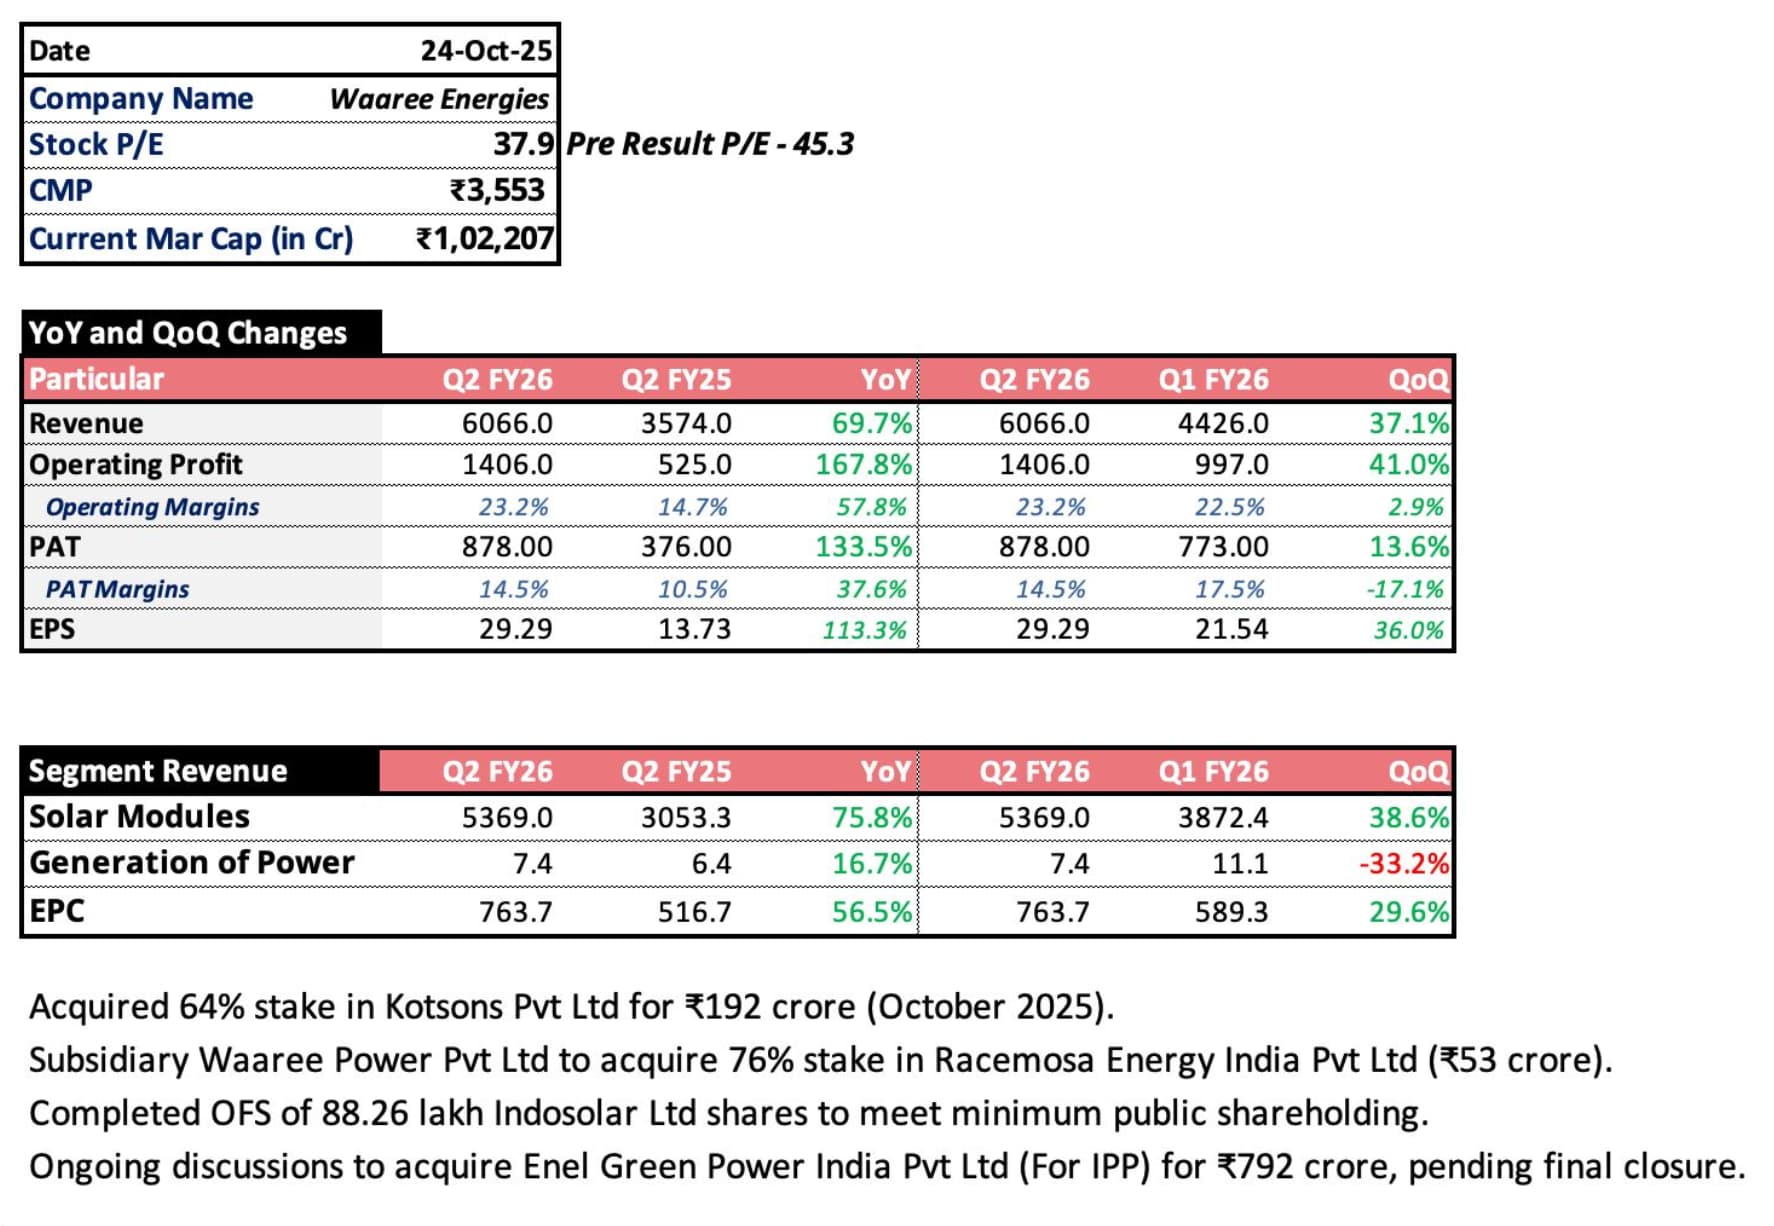
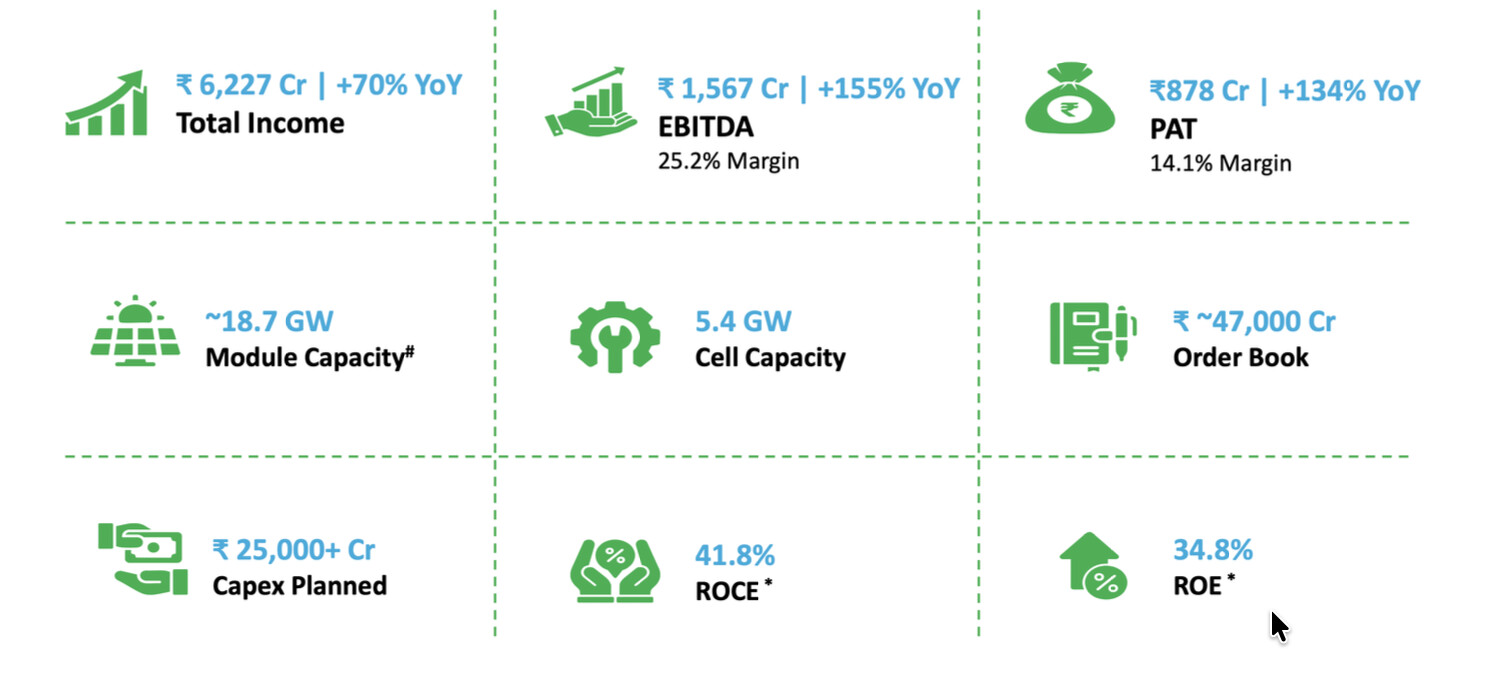
Company has produced highest ever modules in Q2 (2.6 GW)
-
0.6 GW Solar Cells are produced in Q2. (Production is ramping up and it will further improve in H2 of FY26.
-
Order Book Stands at ₹47000 Cr (24 GW)
– 40.5% Domestic and 59.5% Overseas.
– 100+ GW is under pipeline. -
Q2 – Domestic Revenue is 53% and 47% Overseas.
-
Lower GST from 12% to 5%, reduce cost will improve affordability for consumer leads to more demand.
-
ALMM Requirement for cells will be started from 1 June 2026.
-
ALMM Requirement for Ingots and Wafers will be started from 1 June 2028.
-
Both ALMM requirement will boost the domestic production.
-
Company has set up additional 2.75 GW of module capacity at Chikhli.
-
Board also approved additional capex of ₹8175 Cr for:
– Storage Cells and BESS: 3.5 GWh to 20 GWh Capex (₹8000 Cr)
– Electrolyser: 300 MW to 1 GW (₹125 Cr)
– Inverter: from 3 GW to 4 GW (₹50 Cr) -
Company has to do lot more as there are far more opportunities are available.
-
Company has well established in EPC and O&M, at Developing stage in BESS and Inverter and Transformers, at Nascent stage in Power Infrastructure and Green Hydrogen.
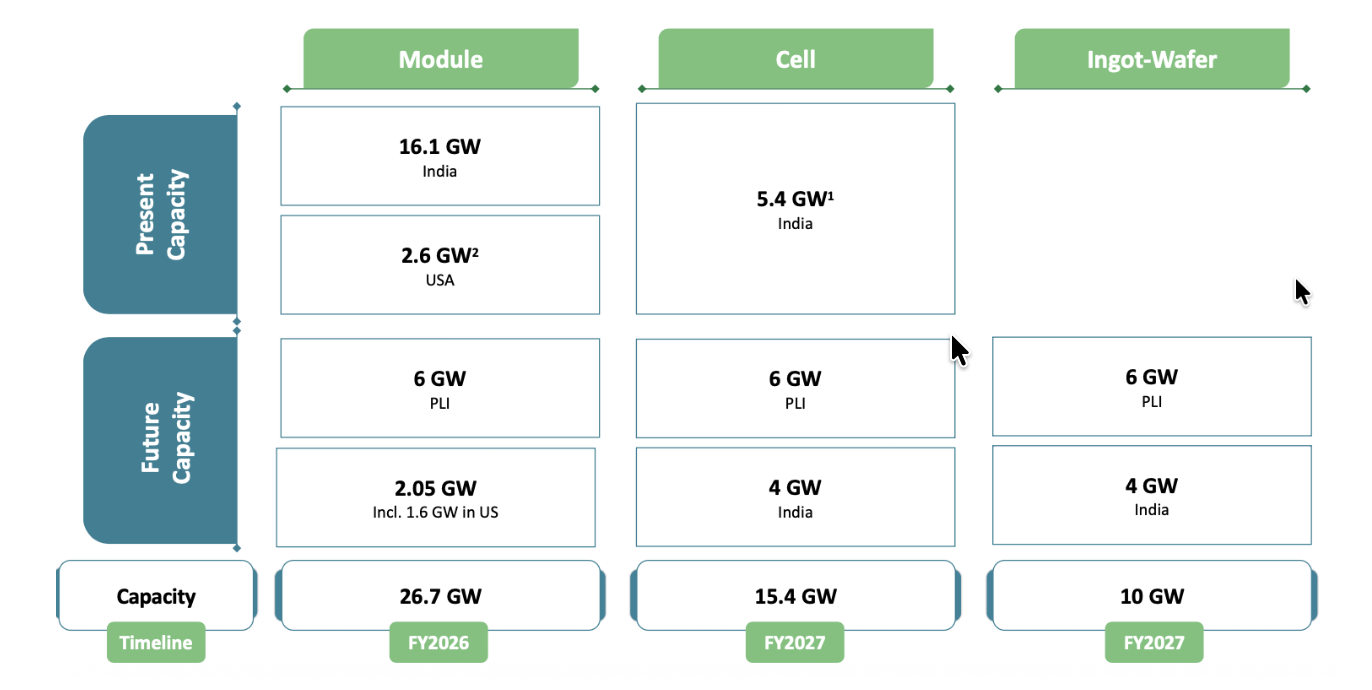
- Cells production was started from this FY , capacity utilisation will ramp up in coming time. All future capacity expansion in on track as per timelines.
- Additional Module capacity will be live by end of FY26
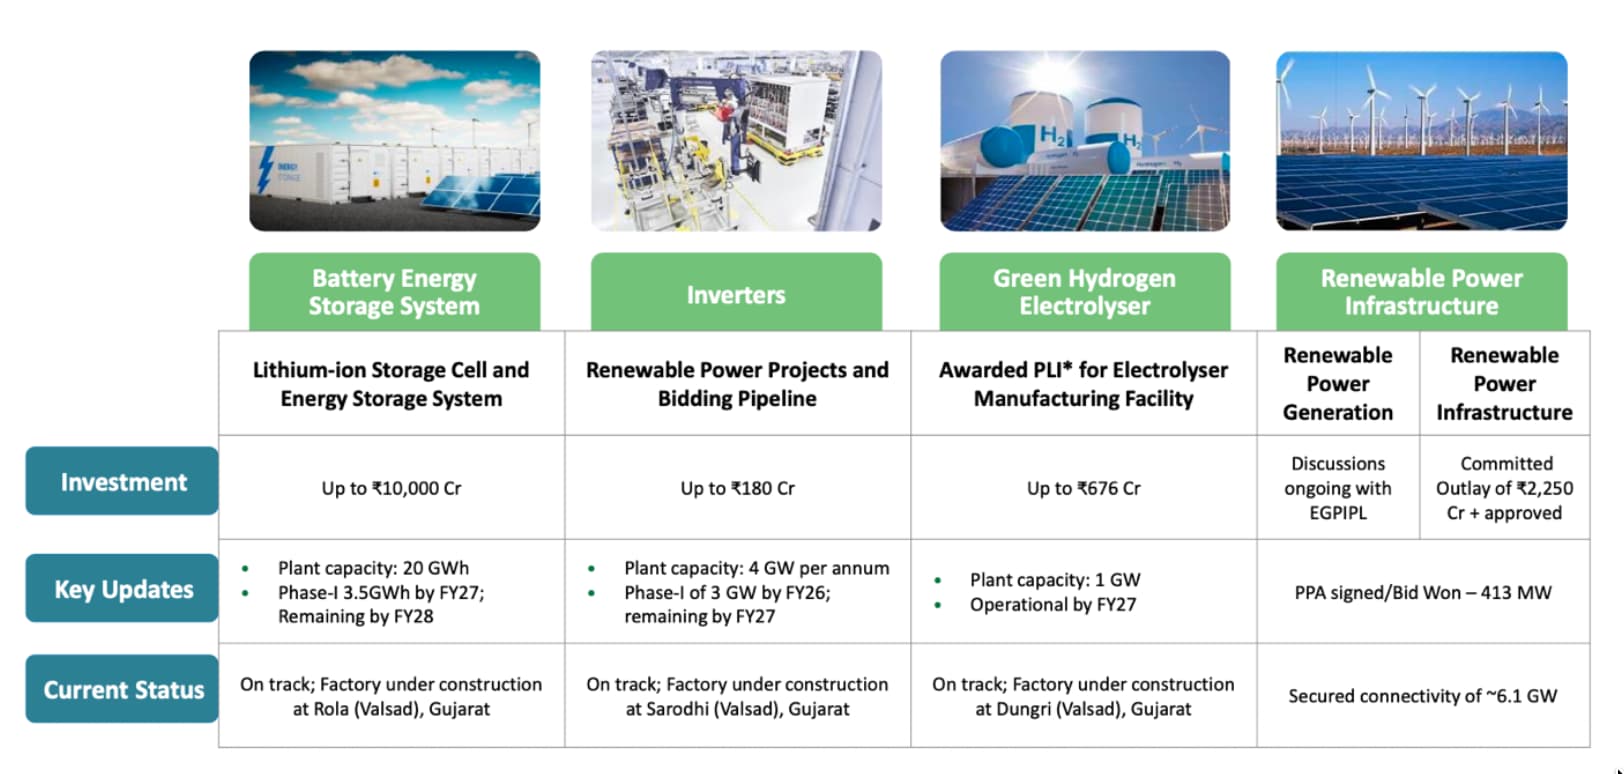
- 100 MW capacity of green hydrogen will be started by FY27.
- Government of India want to setup 236 GWh BESS capacity by FY32.
- Non DCR cells having 18-19% Margins where as DCR cells will get 22-23% Margins.
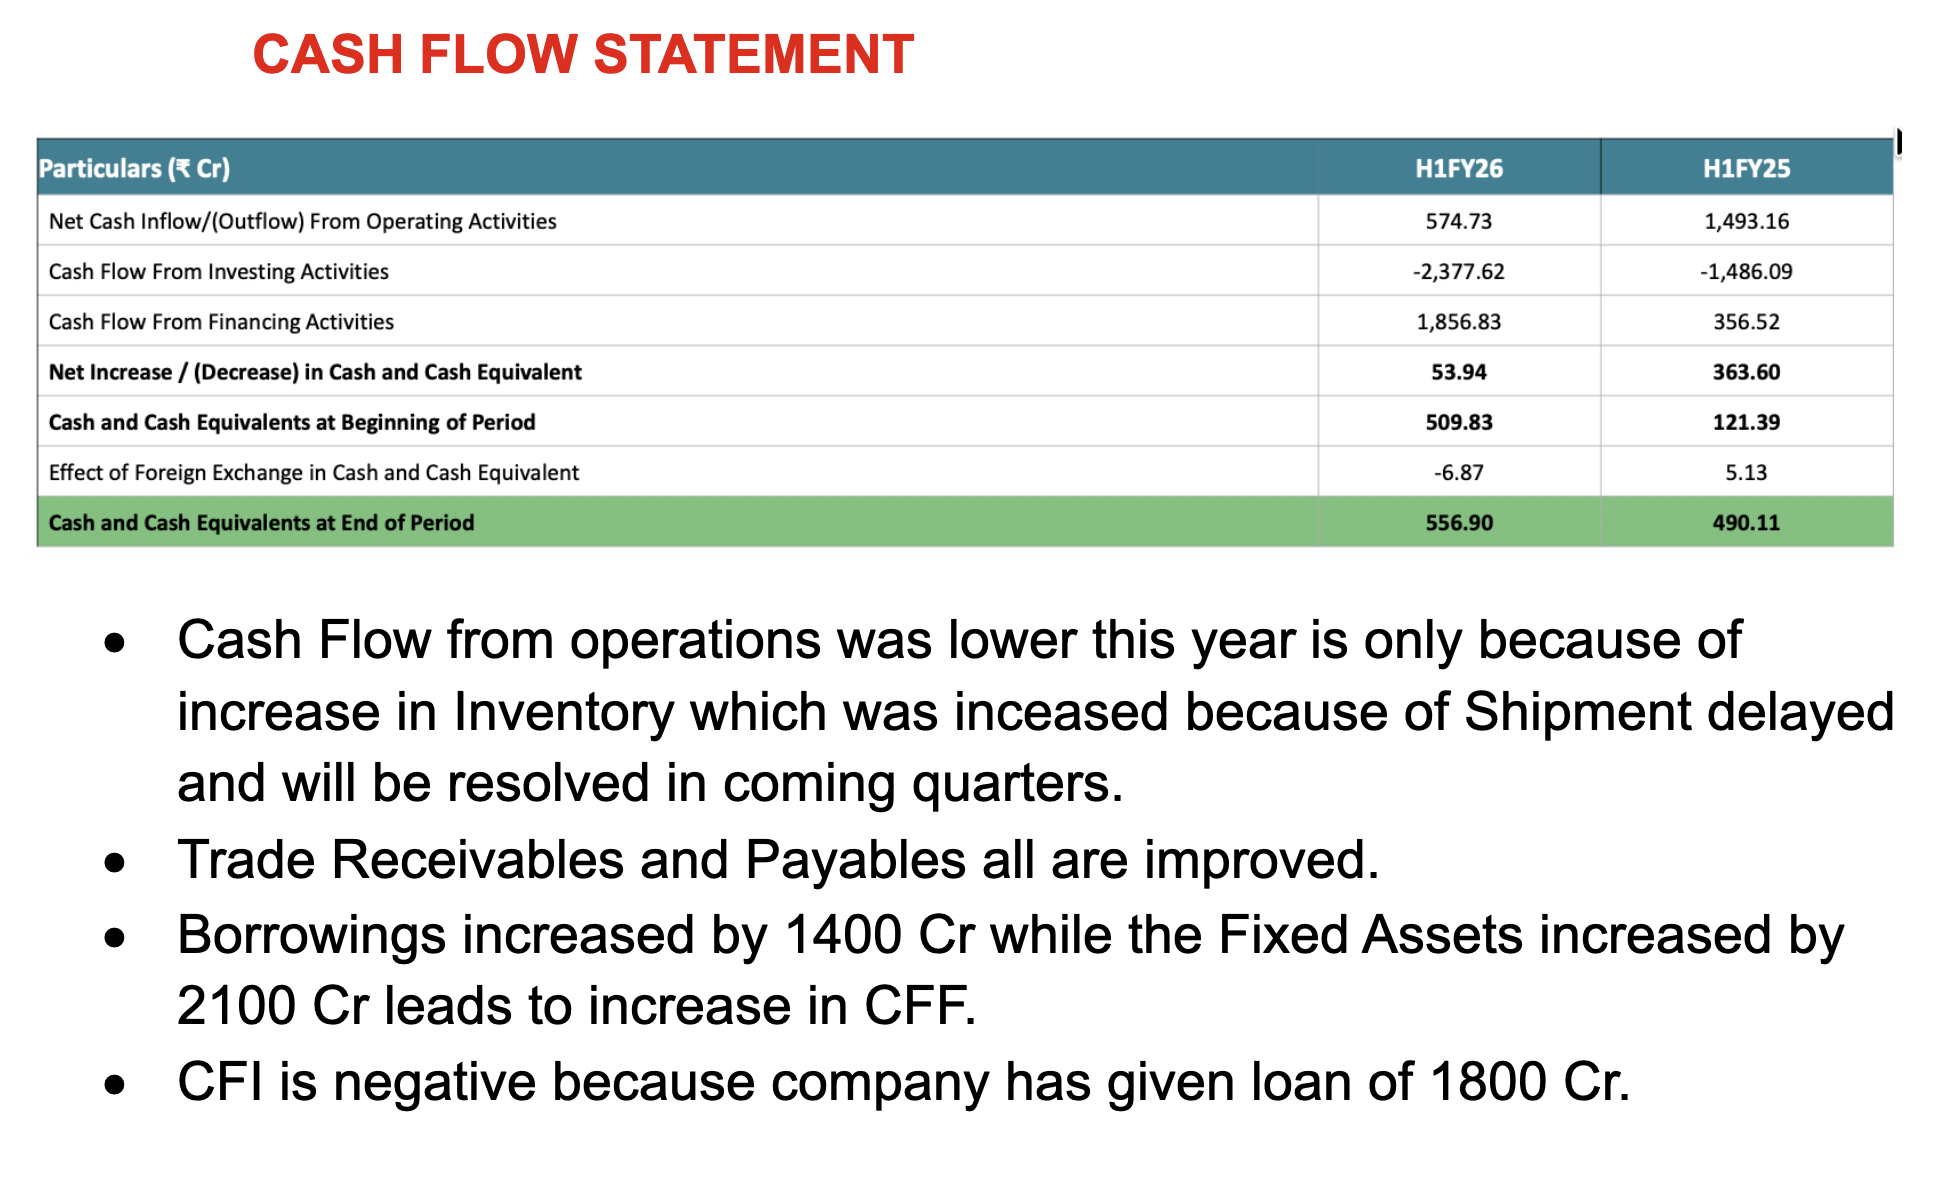
- In Cash Flow Statement increase in inventory is because of shipment haven’t reached to the customer its in the middle way, that’s why company has show this as inventory in the books. This will be recognised in Q3 which will reduce it to the normal levels.
- Advances from customer stands at 3200 Cr which will further increases as the tariff situation got improved as company is unable to take much new orders from US.
- For US orders company currently not sourcing cells from India, cells were sourced from the countries which have lower tariff and company is able to maintain the profitability at the given pace.
- In future company will be able to fulfil US demand from their US facility only.
- Domestic Sales is about 19-20% from retailers and rest of from Institutional Customers.
- Order book doesn’t include retail contribution as there are cash and carry basis.
- Realisation of Solar Modules in US is about 28-30 Cents, where as cost is also higher but net to net profitability is pretty higher than India.
- The actual grid capacity plant of 250 GW from Solar by FY30, when we convert this into modules it will be much higher. Because Solar panel generates energy in DC and electricity then converted to AC which remains 75% of the DC. As per this 250 GW of power from Solar needs 330-340 GW of Modules installation. Rest the module efficiency also matters not all Modules are highly efficient, Real Yields levels will be around 75-85% of total Capacity this will further need more modules to get planned capacity of 250 GW.
- BESS – company will comeup with both pack and module at the same time by Next FY with a capacity of 3.5 GWh Capacity. Plant is already under construction.
- Management said we are expecting same ALMM types policy for BESS aswell by the Government soon. Some words are also going with government regarding this.
- Heavy capex will be done in Next Fiscal as this whole year capex was done and going on. As company has a plan of 25000 Cr of capex in 24 months.
- Actual Benefits of capex will be visible from FY28 onwards.
- 25k Crore capex will be done as follows
– 25-30% in FY26
– 50% in FY27
– And balance will be in FY28