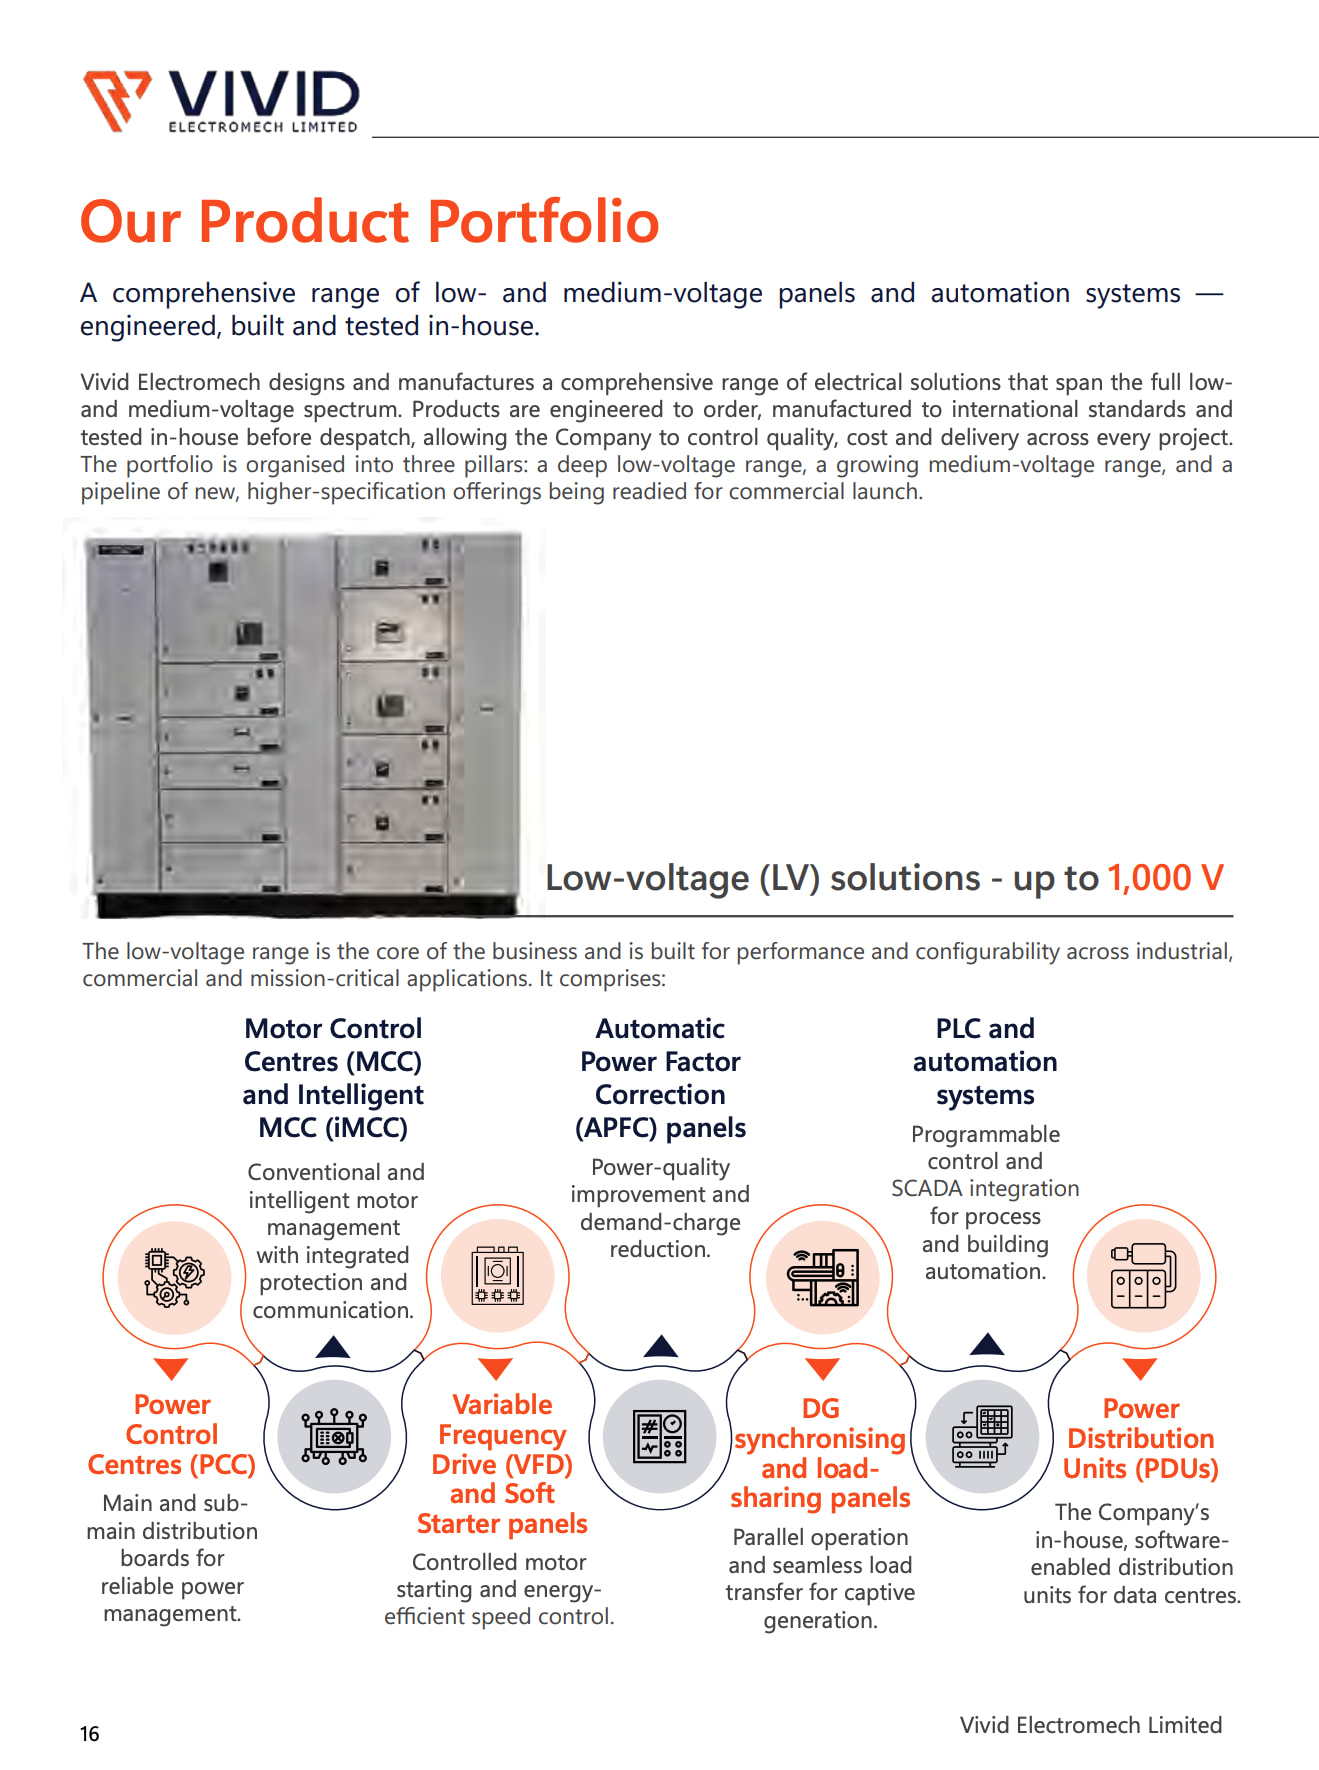
Please correct me if iam wrong, this is my basic understanding of the business as an engineer. The stock will continue to do well due to the theme of data centres and the demand for the same. They make control panels. That is they get steel, maybe cut the steel plates to the correct sizes, make holes for the various electrical fittings(breakers, alarm annunciators, switches, voltmeters,ammeters etc), powder coat the panels, weld them and assemble them at the designated data centre. Then they fix all the fittings as mentioned above(supplied by someone like ABB, Schneider etc) and then the wiring done according to a drawing provided by ABB/Siemens etc. So iam wondering what exactly is the value add here.Will they be taking over the design part done by ABB and would Vivid’s electrical drawings/designs be approved by the data centre. If they were doing the design part, receivables wouldnt be so high.
If this is so simple everyone will do it. There is a lot of complexity involved. Drawings are not provided by ABB/Siemens for panels. They just provide few key components.
Please read more especially the PDU part where they are the only Indian vendor so far.
Regards,
Raj
Disc: Second largest holding for me. Very bullish on the prospects. .
i just put forward of what i understood about the business. I have gone through what the initiator posted and pasting sections of it to put across my point of view, that this more of an assembly business than a design one. Vivid also has a design of its own,but i couldnt find data of how much they sold. The same post says 65% of business is ABB. Again would like to be corrected if iam wrong.
The design is still ABB’s, Vivid would be the assembly manufacturer, IP would still be ABB’s. It still calls for some competence to execute the design and Vivid is an authorized/certified vendor. This competency is also difficult to find but completely different from a design competency which can demand higher returns/ better payment terms. The issue with these kind of arrangements is that OEM’s like ABB/Siemens etc wont allow vendors to make great returns and that sort of explains the long payment cycle.However since the demand is large, maybe everything is forgotten. Since the theme is DC/Power this may also do well and they will also learn as they execute. The PDU development is one such.One has to be vary of valuations just like others in the sector and be ready to get off the bus. I have quite a bit of exposure to the power sector already, but would like to try this as an experiment if it corrects.
Being from the Low Voltage Switchgear industry, I have some concerns for investing in such companies. Basically, most of them are panel builders and mostly depend on OEM product design like ArtuK, Sivacon, BlokseT etc. There are European players like Cubic (now part of Rockwell), Logstrup and Natus who have their own design type tested with major OEM products. This gives them a competitive advantage with the OEMs. For those who do not have their own design has to depend heavily on pricing support from the OEMs and OEMs also prefer to play along with multiple builders.
Unless you have your own product, its difficult to sustain growth in this sector. Marine Electricals on the other has developed their own products for the marine segment which might give them certain edge but not in their main business of LV Switchboards.
Data Center LV Boards as such does not have any specific requirements or special technology that others cannot imbibe, so competition would be heavy which would have a toll on profitability.
The switchboards volume is big in DCs and one who has the financial prowess will deliver the best results.
I think its better to elaborate on what these panel builders actually do. If we take example of Siemens who has their own LV Board design called Sivacon. The franchise builder has to set up the entire manufacturing system on their own which means investing in CNC machines, bus bar bending and cutting machines etc. The end user or the consultant provides the builders with Single Line diagram, the builders do not develop anything on their own. The SLD is fed in a software designed by the OEM like SIMARIS Sivacon for Siemens and entire board design is prepared in the software and is automatically fed to the CNC machine for cutting the sheet steels.
ABB/Schneider Franchise partners buys the metal parts as Flat pack thereby eliminating any investment in machinery. But if you are big, its better to invest in CNC to have the felxibility and ease of sourcing.
But as you can see, the entire system is managed by the OEM, the PB does the execution, which is also not a simple task.
I am not taking the credit from the PBs, but what differentiates PBs is domain knowledge like Marine Electricals has on Marine. But Data Center designs are basic with some additional features like hot spot management etc.
I hope the business is now somehow clear to all.
Hi,
I was looking for the closest peer of Vivid Electromech operating in USA…I found Powell Industries is matched peer in USA…Powell industries however works on complete integrated power control rooms…but it operates in electrical distribution units, control and protection systems…
If we see trajectory of the business of Powell industries, it has really turbocharged due to data centre business…it also trading at multiples of 35~40…So, my assessment is even Vivid Electromech is panel builders..due to scarcity of approved panel builders for Data Centre…Vivid will enjoy tailwinds atleast for 3~5 years…because just for saving few bucks, Data Centres will not invite non qualified panel builders…As Vivid Electromech is approved partner with AWS…As I am new to this company, ready to get corrected…
Comparing Vivid to Powell is like comparing chalk and cheese. First they have their own switchboard design for ANSI & IEC like that of Natus, Logstrup & Cupid. Additionally they have E-Houses, Blast proof enclosures, DC Systems and there total revenue is more than $ 1 billion.
I have personally worked with all the companies I mentioned, bought some cubicles from Powell for their legacy system installed in O&G customer.
If Vivid is approved by AWS with ABB, Schneider and Siemens will try to get their builders approved to have a fair play and AWS cannot say no.
Again LV switchboard for DC is not a rocket science - Schneider has an added advantage as it provides a comprehensive solution with their Ecostructure environment combining LV with ELV.
I am only providing these details so that people are well informed before they take a decision.
I have nothing against Vivid Electromech and as a disclosure was with Siemens for 26 years handling LV , MV & Automation.
Good interview on Vivid, there show a glimpse of their current factory. New factory would have good amount of automation to reduce manpower as compared to existing one.
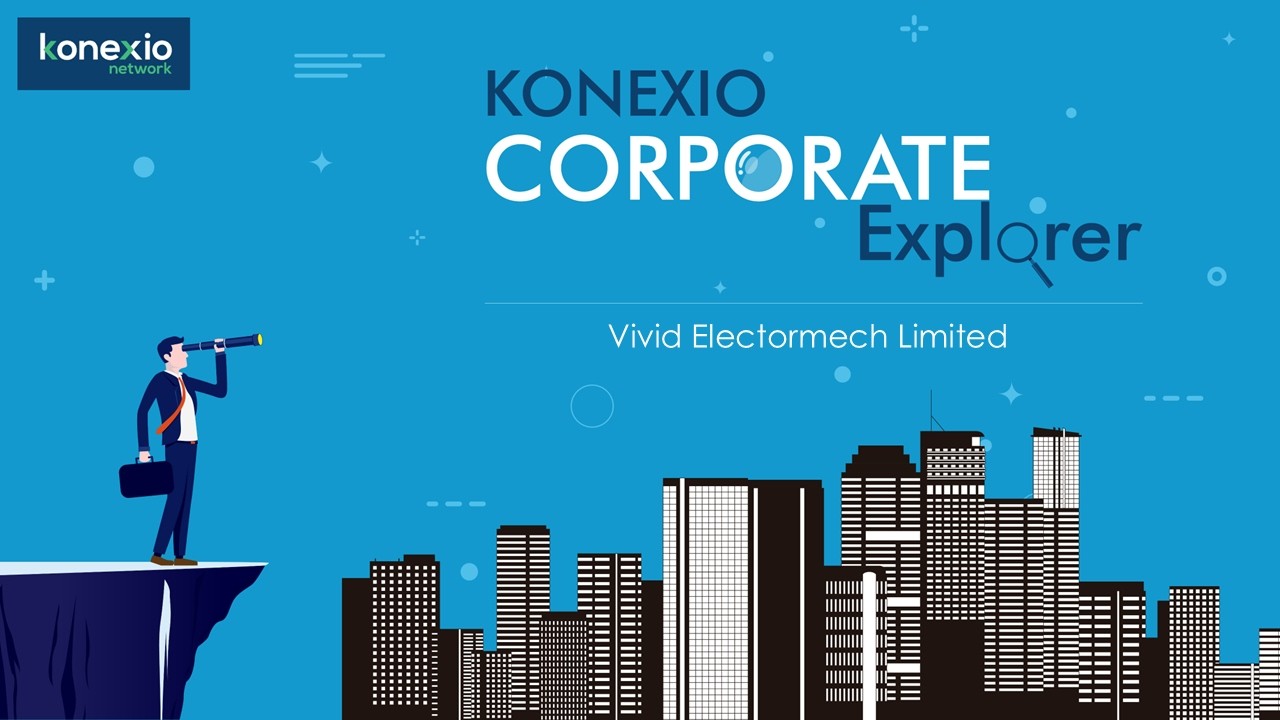
Some Snippets from the recent AR.
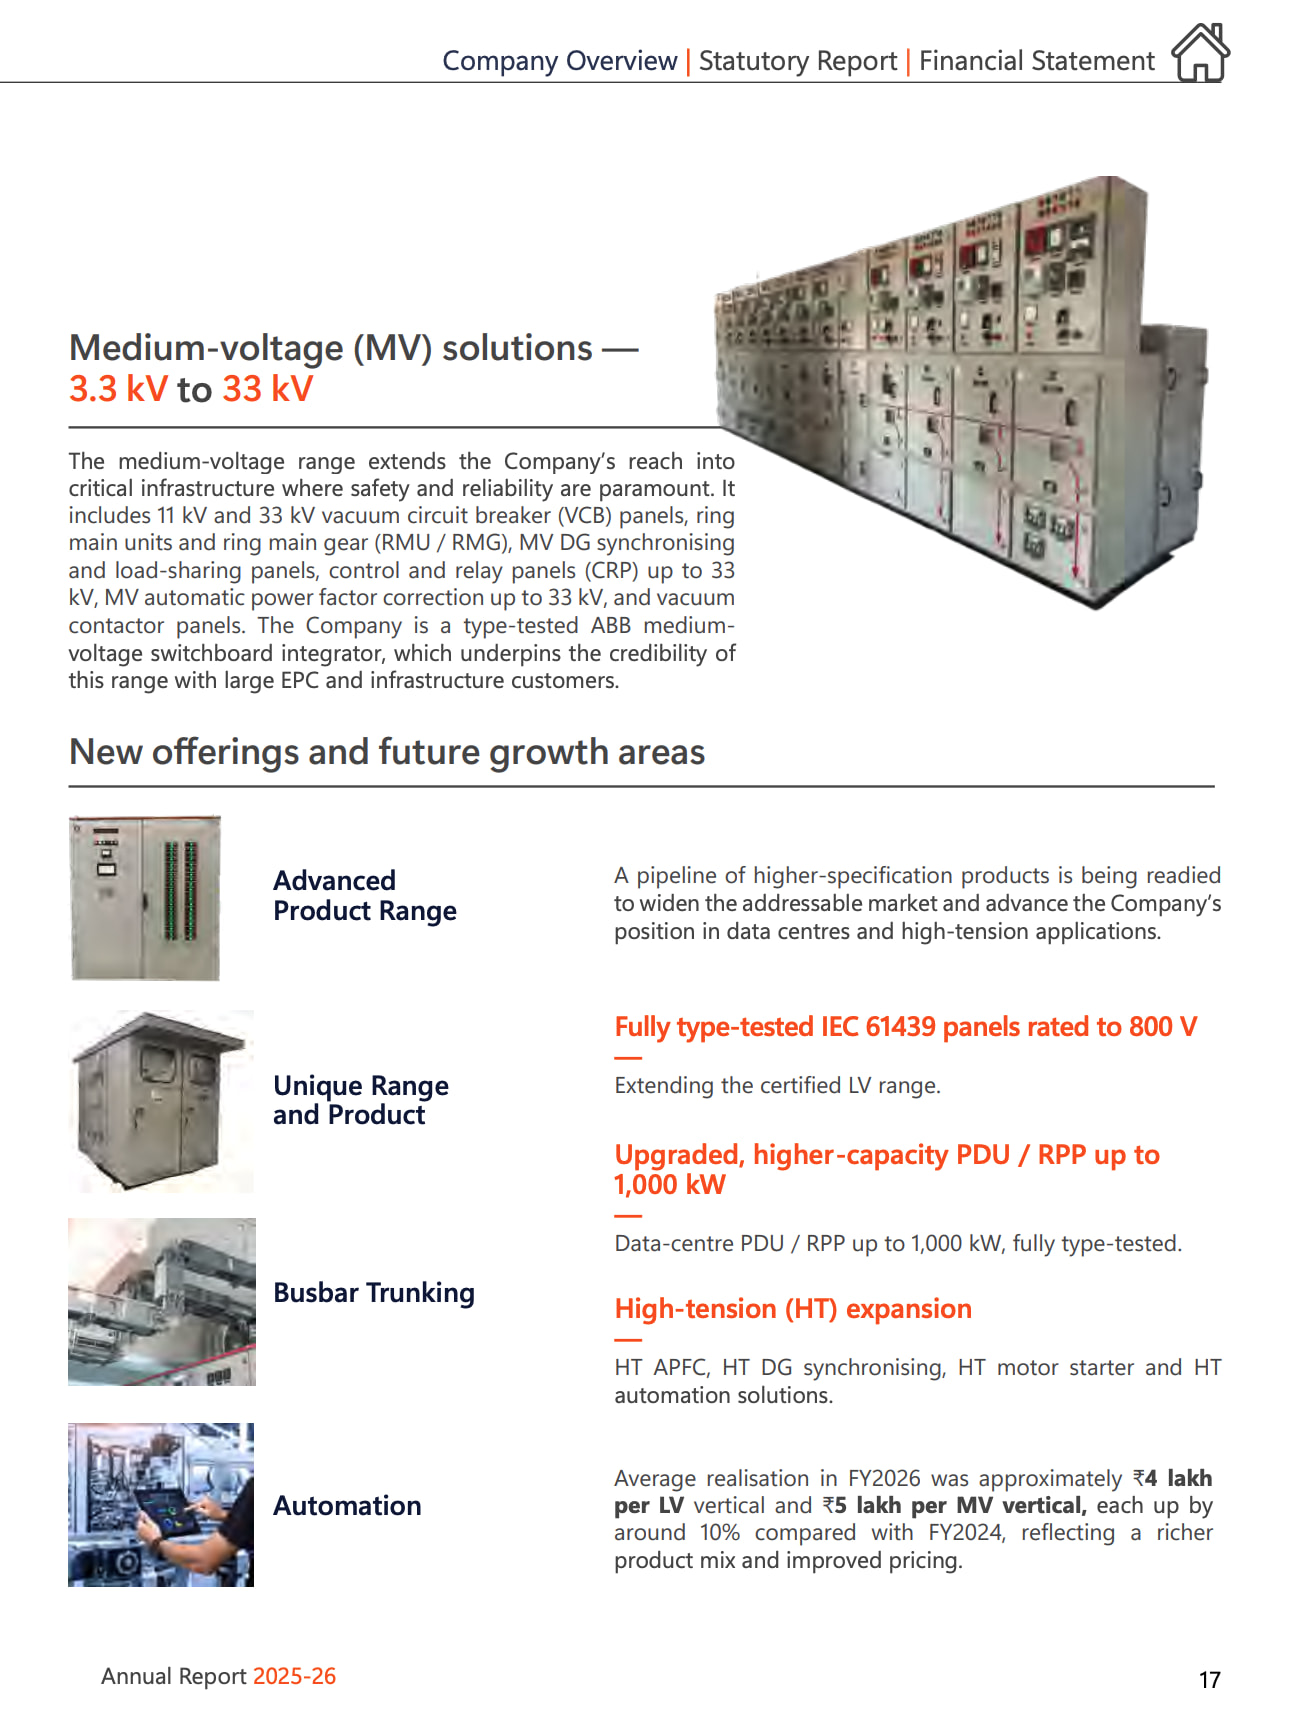
PDU for data centre is their proprietary solution as per claims.
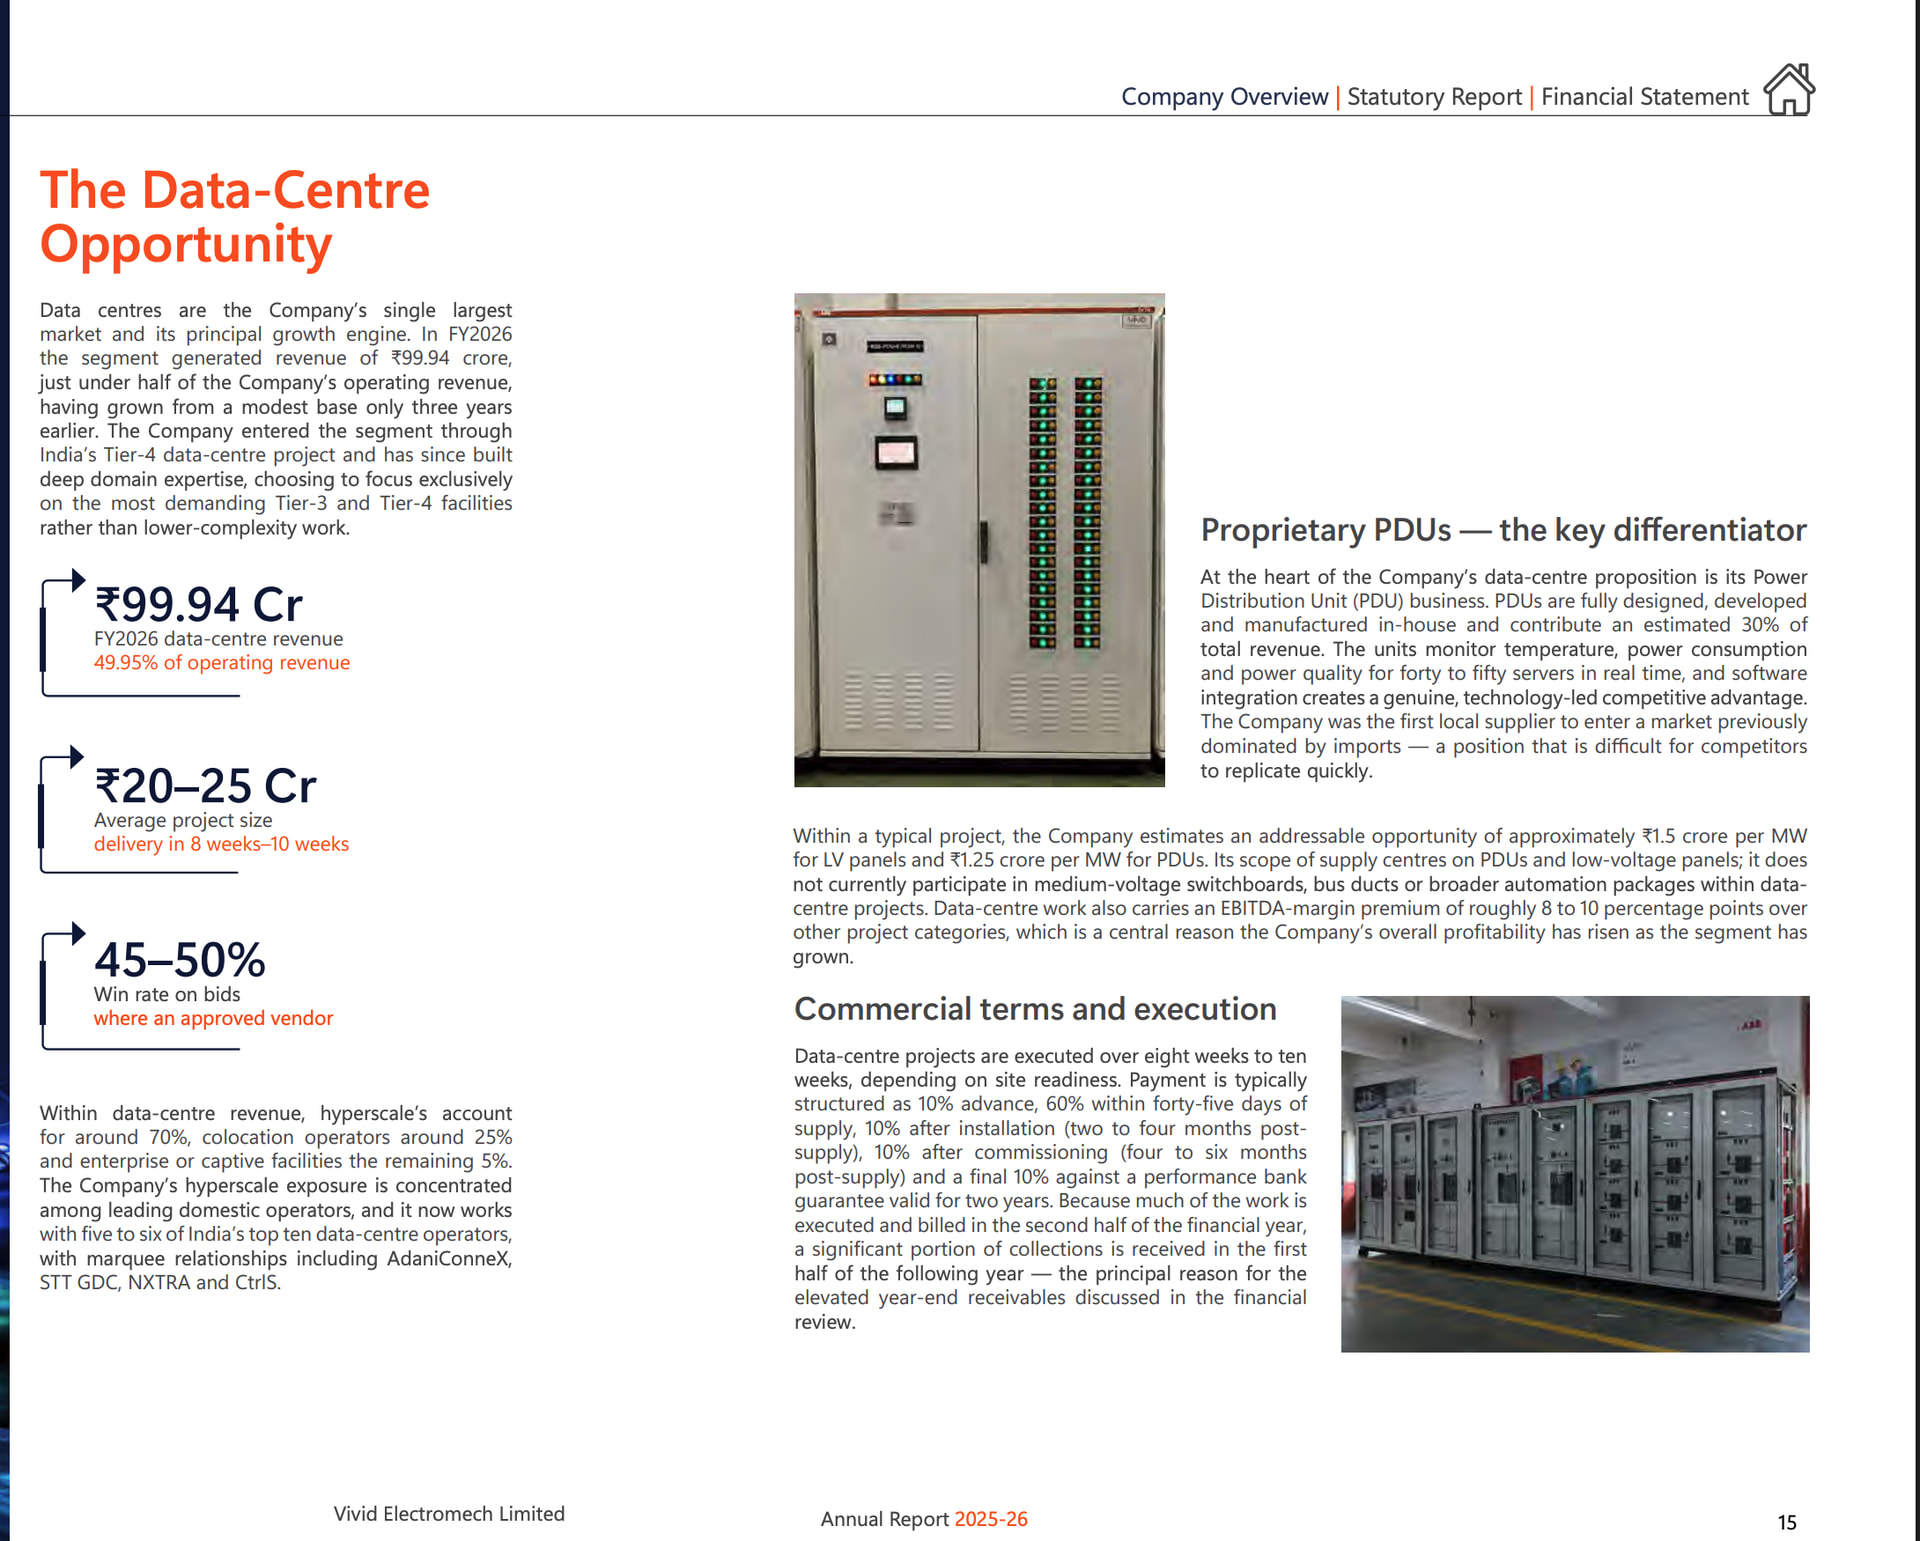
PRINCIPAL INPUT RISK Copper at a record high LME copper reached an all-time high of about USD 14,527 per tonne in late January 2026 — the Company’s single largest margin variable, managed through pricevariation clauses and back-to-back procurement.