I believe they should stick to their current business and venture only in related business areas.If at all they want to start something new then the group is cash rich enough to start a separate company. Such foray into un related sector in the comapny implies that management does not have clarity regarding the future. Acquisition led growth,foray into unrelated sectors are signals of mediocre future prospects.

Tube Investments is planning to build a new precision steel tube manufacturing facility in Western India.
This facility will help them expand their capabilities and better serve their customers in different regions. The new facility is intended to produce various types of steel tube products, but the exact manufacturing capacity is not determined yet.
The estimated cost of this project is Rs. 211 Crores, and they plan to fund it mainly through their own earnings (internal accrual).
They anticipate completing this project during the fiscal year 2024-25.
2 Likes
What is source of Rs 551cr other income in this quarter. It was shown as income from discontinued business but not given details of which business has been discontinued. If anyone can give information regarding this, please let me know.

CG Power one of the leading companies in Industrials have seen good growth in Order book for the Financial Year 2023-24. The same has been discussed below:
The unexecuted order book for Q4 standalone as of 31st March 2024, was 45% higher year-on-year at Rs. 6276 crores against Rs. 4319 crores as of March 31, 2023.
Segment wise bifurcation of order book for FY23:
For Industrial Systems, the unexecuted order book was 25% higher, year-on-year at Rs. 2,544 crores vas against Rs. 2,040 crores as of March 31st, 2023.
For Power Systems, The Order book was 64% higher year-on-year at Rs. 3,731 crores as against Rs. 2,279 crores as of March 31st, 2023.
This shows a great potential of growth in the upcoming years. However, the execution of these orders will take around 2-3 years. The Company has also seen a lot of order inflow form the railways for the 4Q of FY23.
The CEO of the Company has quoted that it expects a strong growth for the year 2024, with topline growth being 40% for the railways.
2 Likes
Just sharing this interesting article on Tube Investment. It’s worth an in-depth reading.
I hope you find it useful.
dr.vikas
1 Like
If Marcellus has entered, it means it is now time for the rest of us to exit 
Disclaimer: this is a joke.
12 Likes
TII’s market cap of about Rs.81000 crore is almost equal to the the value of its stake in two of its listed subsidiaries, CG Power (58% stake) and Shanti Gears (70% stake).
On standalone basis, its PAT was Rs.735 crore in FY24, which grew at a CAGR of 24% in last 5 years.
Its EV subsidiary TII Clean Mobility has trucks, 3 wheeler and EV component business and have plans to launch LCVs and Tractors, apart from ramping up components business. TII clean mobility has raised Rs.3000 crore through equity and CCPS from reputed funds.
Other key businesses, which are in early stage, include medical devices and CDMO.
One may argue that there should be significant holding company discount assigned to the listed subsidiaries and current market cap might also be indicating the same.
However, in my personal view, extent/existence of holdco discount in future may depend upon extent of success in new businesses and also if it is be able to achieve its aspiration of becoming a manufacturing giant.
Disc: Invested. I am not SEBI registered Advisor/Analyst. My view may be positively biased. I am not suggesting any investment action. The information provided above is for education purpose only.
8 Likes
Most listed companies of the group hold leadership position in their respective verticals and given the management’s amazing track record and conducive Govt policies, each one of them will keep generating positive cashflows for a long time to come.
Rather than locking capital in one/more companies, moving cash between them gives a better return on invested capital. I have been doing this holding TI, EID Parry, Carborundum & CG Power, with a strict cap of 50% combined value allocated in any one company.
Ongoing family feud in the group and an imminent split is the major threat facing all these companies from what otherwise an unshakable collective strength of all the member companies in the group.
2 Likes
Family Fued is cleared,
They have done a settlement with sanction of all members.
Certain members have left board positions and stock holdings listed as non promoter now.
Differences in family are like cracks in glass, impossible to be fixed. Seeming fixes are to be taken with a pinch of salt.
Group premium assigned to each stock can be wiped off as and when a split becomes obvious. Until then juggling between the stocks should pay well.
1 Like
TI, EID Parry, Carborundum & CG Power, with a strict cap of 50% combined value allocated
Can it be inferred like going in with 1-2 yrs time frame focusing on the sectors offering good demand…say for ex.power > cg power.or for ex.consumption >eid parry.
or Did i read it wrong, How this possible juggling can be planned ?
D-New recruit, Small position at CG.
The way I move is by keeping a cap of 5% on all equity exposure in Muruguappa as a group and with a further cap of 2.5% on any one company within the group that I have chosen without a bias on any one. All stocks selected moves in different patterns and with certain spikes and troughs. All I do is ploughing some from the out performers and feed them to under performers.Collective return being the objective, I don’t hesitate exiting fully from any one and remain open to re enter same later.
Working well so far and will continue to move on these lines knowing well the maximum downside on stock level as well as Murugappa as a group level.
1 Like
Exactly, family was cracked. Thus, the settlement where shareholding is divided, and management control is with one section of the family.
This is a two year old story that I have tracked well since CGPower is a core holding of mine since 2020.
4 Likes

Decent to Good Set of Numbers in Q1 FY26
Capex Plan of ₹1,000 crore in FY26, with the majority of the capex allocated to the engineering and metal division.
(Disc: Not Invested, Just Tracking)
3 Likes
Anyone Tracking this company? No updates since one year. The below are the updates I found and may be worth noting. The stock has delivered negative returns in last one year and the PE is rather high compared to the sector, at nearly 86. But given the turnaround story of CG Power, any Murugappa Group company is worth tracking.
The Growth & Aggressive Alignment: TII is essentially the incubator and holding engine for the Murugappa Group’s most aggressive growth bets. They are heavily expanding into the Electric Vehicle (EV) ecosystem (via Montra Electric for 3-wheelers and heavy commercial vehicles) and clean energy.
The Turnaround Pedigree: TII is the actual parent company that acquired and engineered the massive, highly successful corporate turnaround of CG Power. By investing in TII, you get a diversified piece of CG Power’s upside alongside TII’s core engineering, precision steel tubes, and industrial chains infrastructure.
3-4 Year Horizon Outlook: Management’s recent commentary highlights aggressive expansion plans (capex) and structural long-term agreements designed to scale up margins significantly over the next few fiscal years
3 Likes
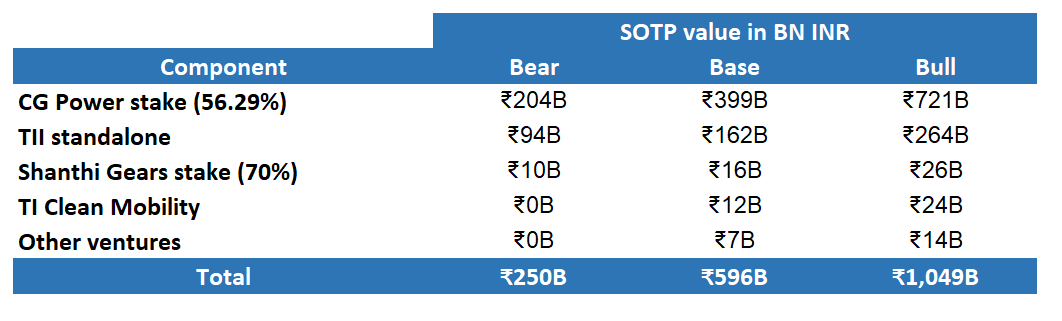
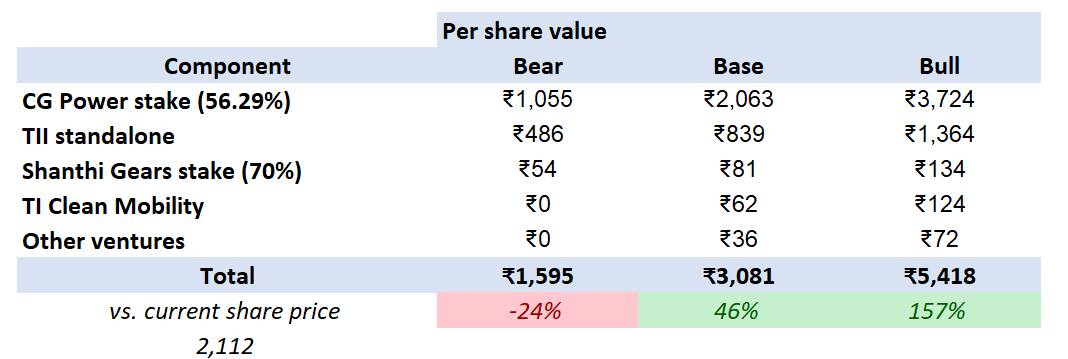
I recently did a deep-dive and valuation of TII after the sell-off in the last few months. It currently trades at 60% HoldCo discount, which is largely un-justified in my opinion. My base case sum-of-the-parts valuation shows a 46% upside, with the bear case showing a 24% decline and bull case showing the stock more than doubling
Summary:
-
TII (Tube Investments of India) is a Murugappa group holding company which calls itself “India’s Premier Engineering Company”. It owns 56.29% of CG Power (worth ₹720B) and 73% of Shanthi Gears (worth ₹26B). TII itself trades at ₹402B, down ~34% in a year.
-
CG Power is one of the largest beneficiaries of the AI-driven electricity boom in India and overseas. Even before AI, India’s power demand was growing faster than almost any major economy: electricity demand grew about 7.3% annually over FY21–FY25, outpacing China (6.3%), the US (2.1%) and the global average (2.8%)
-
It also owns a high quality standalone tubes business (precision tubes, chains, door frames, cycles) that generated ₹8.3B in FCF in FY26, grew top line by 8% and generated a 44% pre-tax ROIC
-
A management team with a history of exceptional capital allocation: 90x return on CG Power investment, 6x return on Shanthi Gears (both before dividends) and a pristine balance sheet, with net cash of ₹32B
-
The catch: the ever-present “conglomerate discount”, CG Power seems to be priced for perfection at ~94x trailing earnings and an EV start-up arm (TI Clean Mobility) that lost ₹1.5B in Q1 FY27.
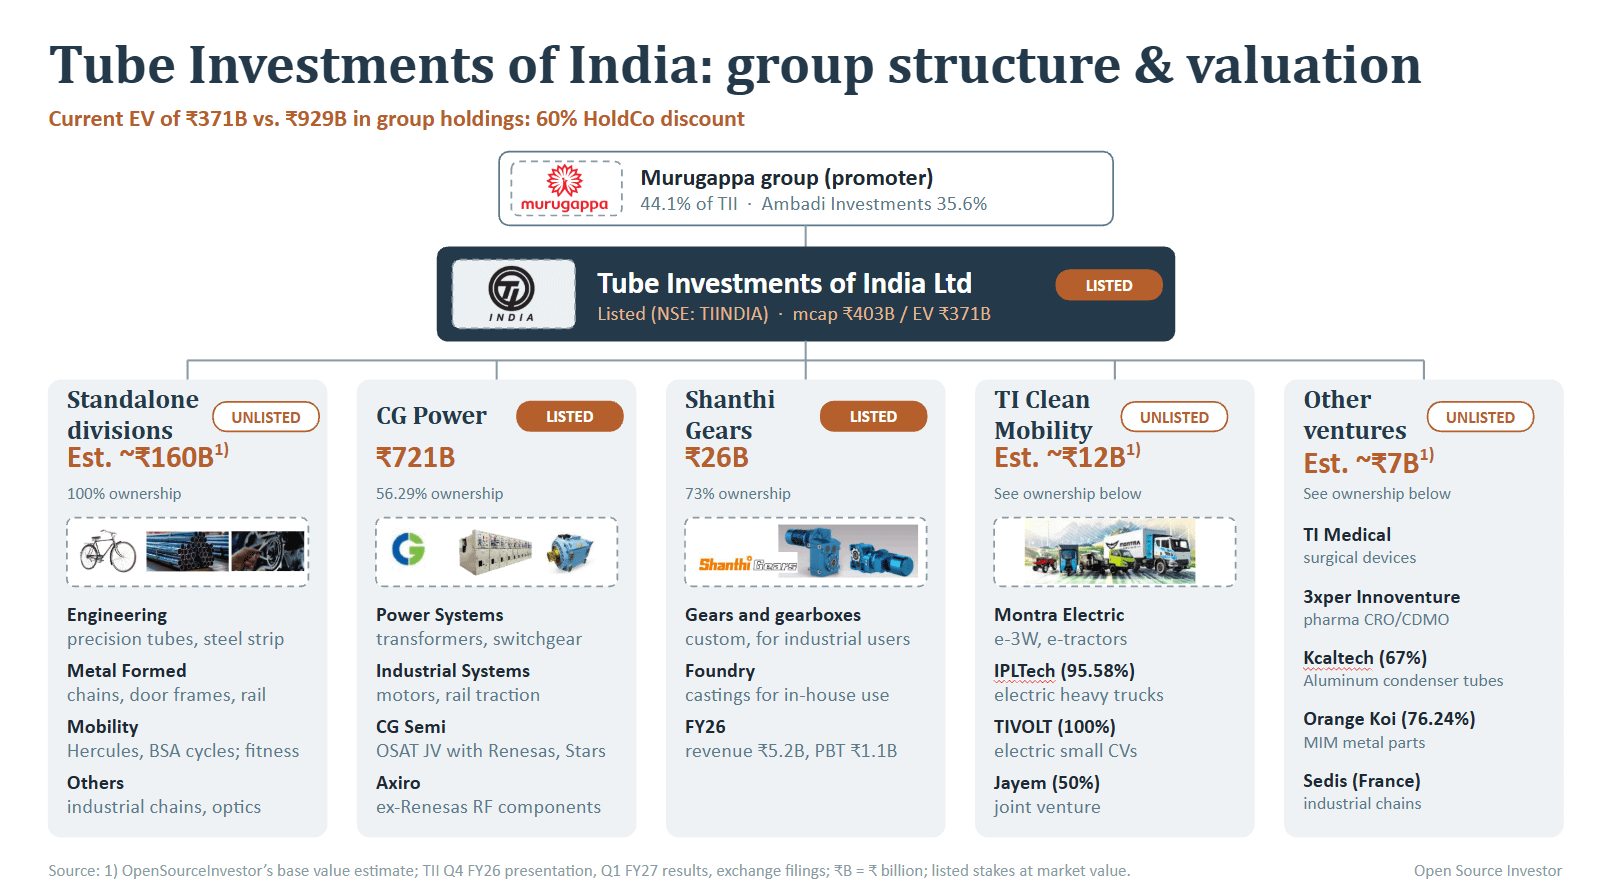
Sum-of-the-parts valuation:
-
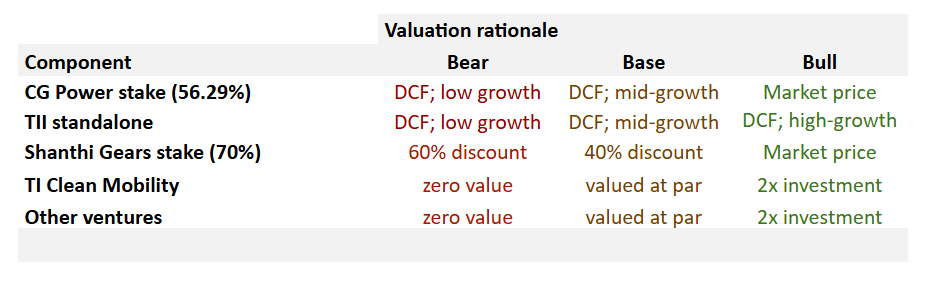
Bull case: listed subsidiaries valued at current market price; Note : CG Power seems very over-valued, at 94x earnings (1% earnings yield!); This would only be reasonable if earnings grow 25%+ for the next 10 years, which is a very hard bet to make.
-
Base case: DCF-based valuation using mid-growth assumptions for CG Power and TII; Shanthi gears valued at 40% discount. Venture bets valued at par.
-
Bear case: DCF-based valuation using low growth assumptions and margin compression; Shanthi gears valued at 60% discount. Venture bets valued at zero.
Valuation link (excel)
Conclusion
In the AI gold rush, CG Power has found itself well placed to sell the picks and shovels. Its ₹236B order book (up 58% in a year) says that the transformer party is far from over. The catch is that CG Power is priced as if it has already struck gold, at roughly 92x TTM earnings.
TII offers a side entrance to effectively buy CG at about half price. Thrown in for free are a tubes-and-chains business earning 44% pre-tax returns on capital, a majority stake in Shanthi Gears, and a handful of new ventures.
However, this company is far from a “no-brainer”, and any minority investor has to trust the management team to continue to make prudent capital allocation decisions or return the excess capital to shareholders. I currently hold a mid-sized position in my India portfolio and plan to hold for the next few decades (or ideally forever).
Please let me know if you have any feedback or think I missed any key points. Thanks!
3 Likes