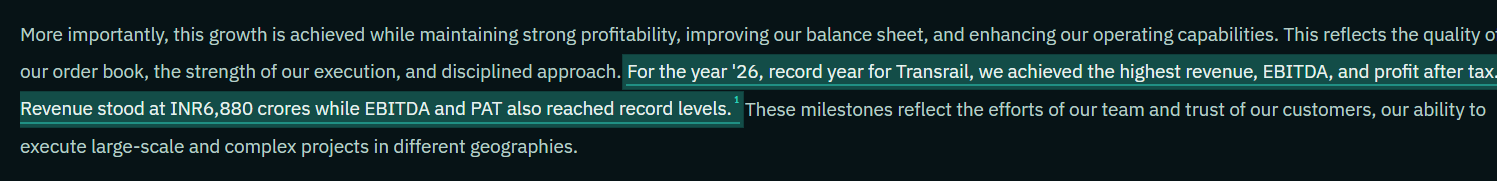
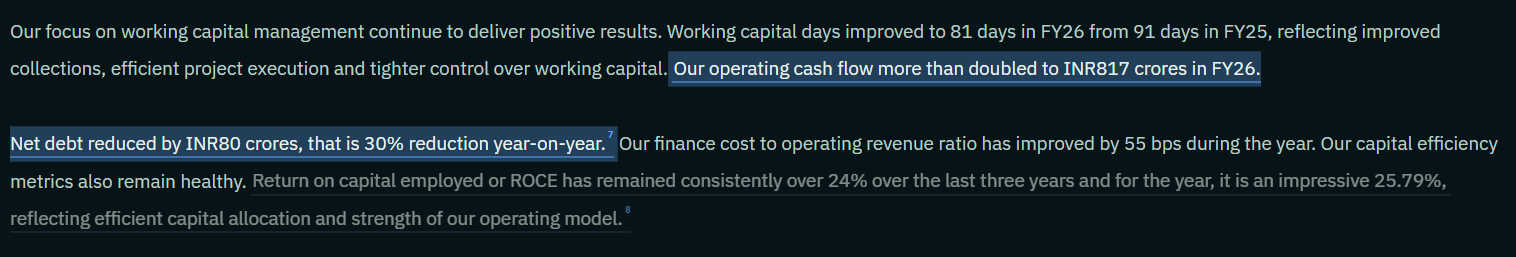
They are guiding for 20 percent growth in fy 27 11 percent margin this Yr the ocf is 600 cr and even fcf is 500 cr have a very lage order book over 14000 cr a reasonable pat margin around 6 typical epc power like kec high receivables and payable and contract asset but better roce than kec but why Market is pulling this price down to the ipo level
What is the issue Promoter is holding 71 percent not Pledged the net debt without ipo is 250 cr cfo said in concall
Why Market is bought price down to 465 level it is in a booming power transmission segment
Just reading even all the comments above but could not fix the reason Market the mr right
can the experienced person in this epc field shed some light.
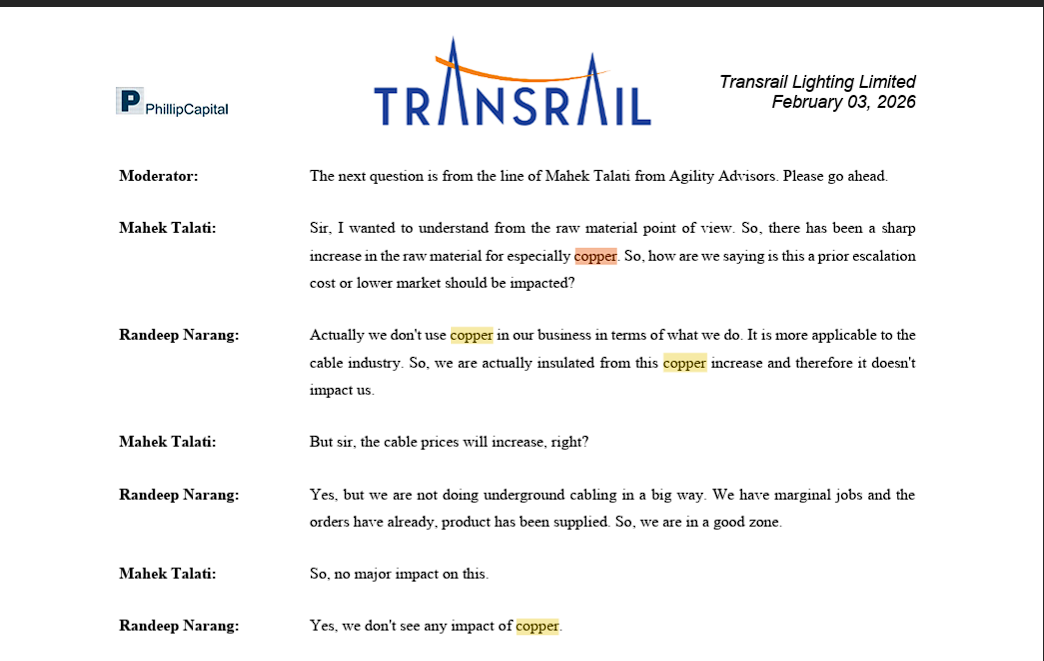
I think it is because of the rising commodity prices, and the market is afraid of margin compression due to the higher input prices. Disclosure: invested.
The company’s financial position appears comfortable, with a debt-to-equity ratio of around 0.3x and operating cash flow of ₹287 crore compared to net profit of ₹327 crore in FY25. This indicates that profits are converting into cash reasonably well. The increase in working capital is mainly due to higher trade receivables, contract assets, and inventory required to support growth. However, this remains an area to monitor because large amounts of capital are tied up in ongoing projects.
The key risks in Transrail are:
(1) high dependence on project execution — delays, cost overruns, or execution issues can hurt margins
(2) working capital intensity — contract assets of around ₹2,522 crore and trade receivables of around ₹1,317 crore mean a significant amount of money is locked with customers/projects
(3) EPC industry competition — aggressive bidding can reduce margins over time
(4) limited pricing power — the company generally executes projects based on competitive tenders
(5) earnings cyclicality — revenue and profits can fluctuate depending on order inflows and project completion cycles
(6) dependence on government and utility spending, where payment cycles can sometimes be slow.
The positive side is that Transrail has an backward integrated manufacturing capability, a strong order environment, manageable debt, and decent cash generation. The investment case depends on whether the company can maintain margins, improve cash conversion, and generate high returns on capital while scaling. The biggest factors to track going forward are receivable days, contract asset growth, ROCE, order book quality, and whether operating cash flow consistently matches or exceeds reported profits.
What i could some up from this concall summary (Disclaimer:Used a financial Investor and analysis platform which uses AI) is that they missed their order intake annual targets by 15% and only a margin of their orders have pass on clauses meaning other disruptions come out of their pocket. But someone mentioned that copper price fluctuations do not affect them that much.
I personally think that the GST Penalty has been blown out of proportion alongwith their order intake target reduction.
Disclaimer: Invested and if i have made any mistake in this post please do correct me veterans as this is my first time posting in this depth.
This stock nosedived. Breaking it’s 52 week lows aswell but upon digging, I am unable to find any concrete reason. Seems planned 600 Cr capital raise via QIP is one of the reason but still such fall is pretty unexpected.
I think they are siphoning off money to the promoter entity in the form of loans every year.
They have continuous related party transactions with their promoter entity that has nothing to do with the company.
Related-Party ICDs: ₹79 Cr unsecured loan to Burberry Infra (used to acquire Gammon’s distressed asset Deepmala Infra) was repeatedly rolled over and flagged by statutory auditors. Former CFO Rajesh Neelakantan held overlapping directorships across these entities.
Pre-IPO Promoter Structuring: FPCCL acquired a 40% stake in late 2023 at an entry multiple of ~4.5x FY23 PAT, followed by an IPO exit/listing at ~23x P/E within 15 months.
Regulatory Overhang: Prior MCA inquiries into ₹77 Cr bad-debt write-offs and RPT impairment disclosures, compounded by the Income Tax Department’s search and seizure in March 2026.
It’s suspicious about the unsecured loan, but when this was asked in the concall, the company said that the repayment of the loan from Burberry Infra is in line with their FY27 expectations. They also said that they are earning 12% interest on the loan, which is higher than the interest rate at which the company borrows.
They also mentioned that ₹31 crore of debt was recently repaid by the Burberry infra.
Another suspicious aspect of Transrail is that when you look at the pre-IPO shareholding, there appear to be 3–4 layers between the actual promoters and the listed company.
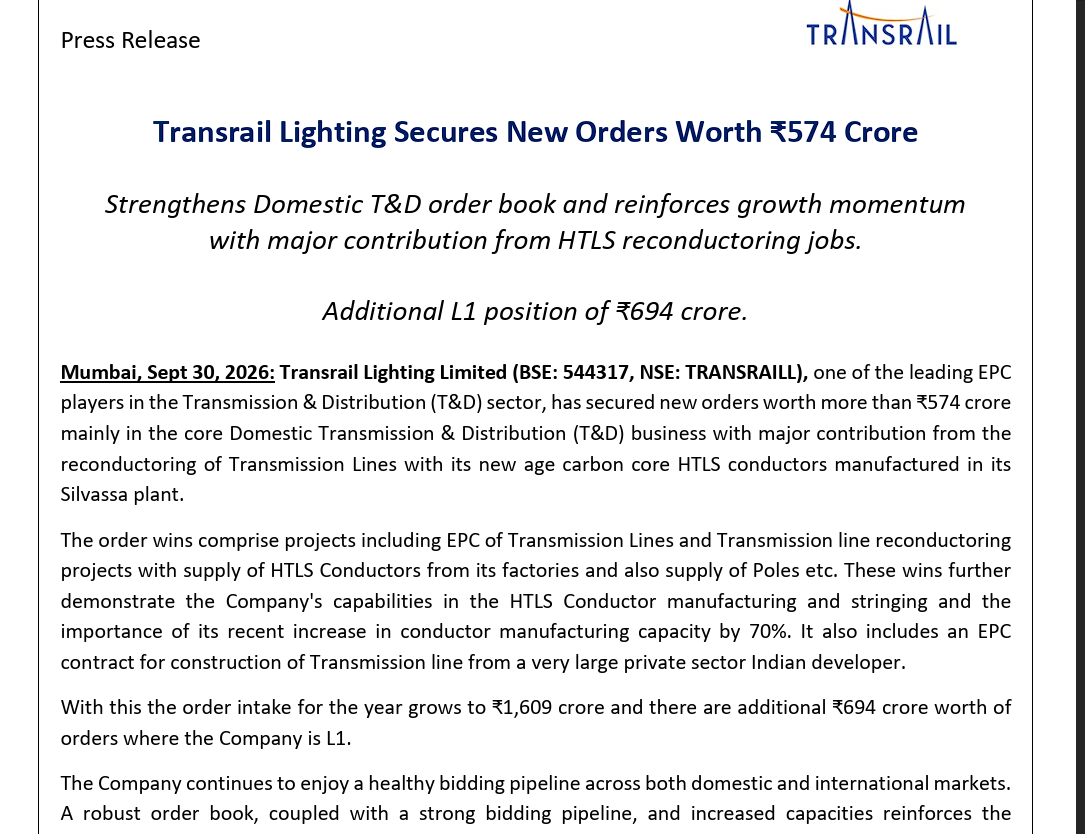
Company got its first order for HTLS conductor after commissioning of new plant but the major concern is their order rate per quarter. Company managed to achieve only 1609cr fresh orders as of now whereas their guidance for full year is 10000cr
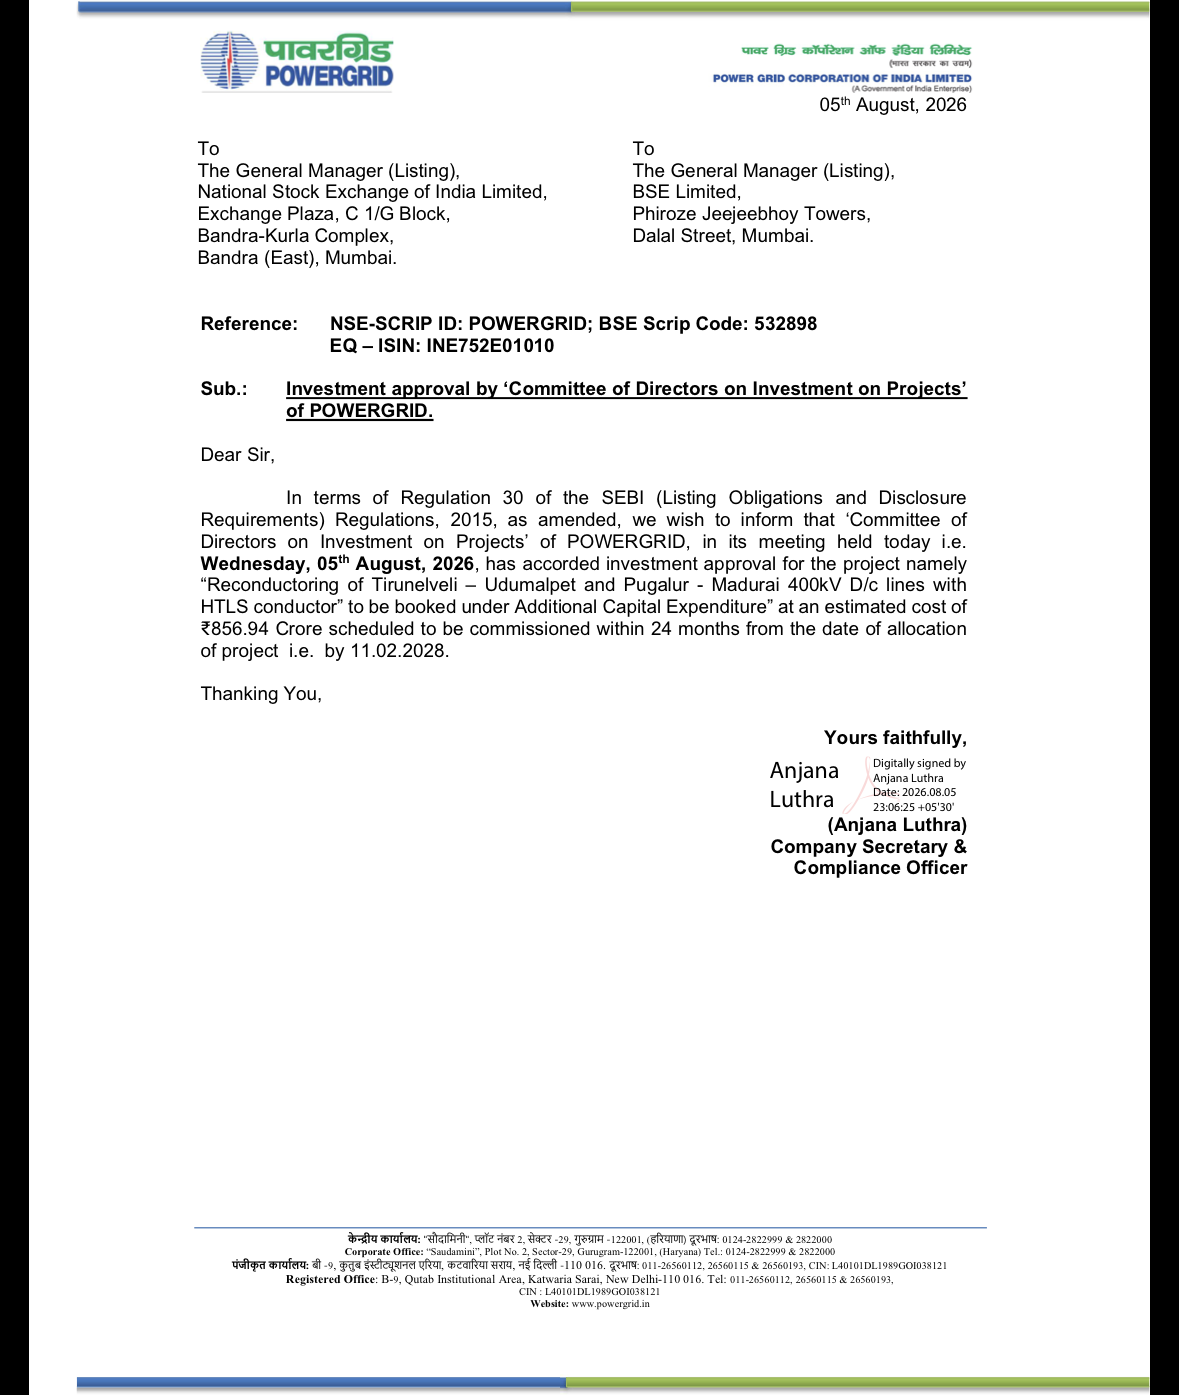
Recently, transrail won an order for HTLS reconductoring project for this D/C line and powergrid has raised its capex. Many reconductoring tenders have already been floated and with TBCB winning multiple projects in various states recently will open doors for HTLS conductors in coming months. Another multiyear growth opportunity for transrail is GEC(III) project recently announced by GOI . Next 4-5 years look attractive for transrail in terms of order pipeline