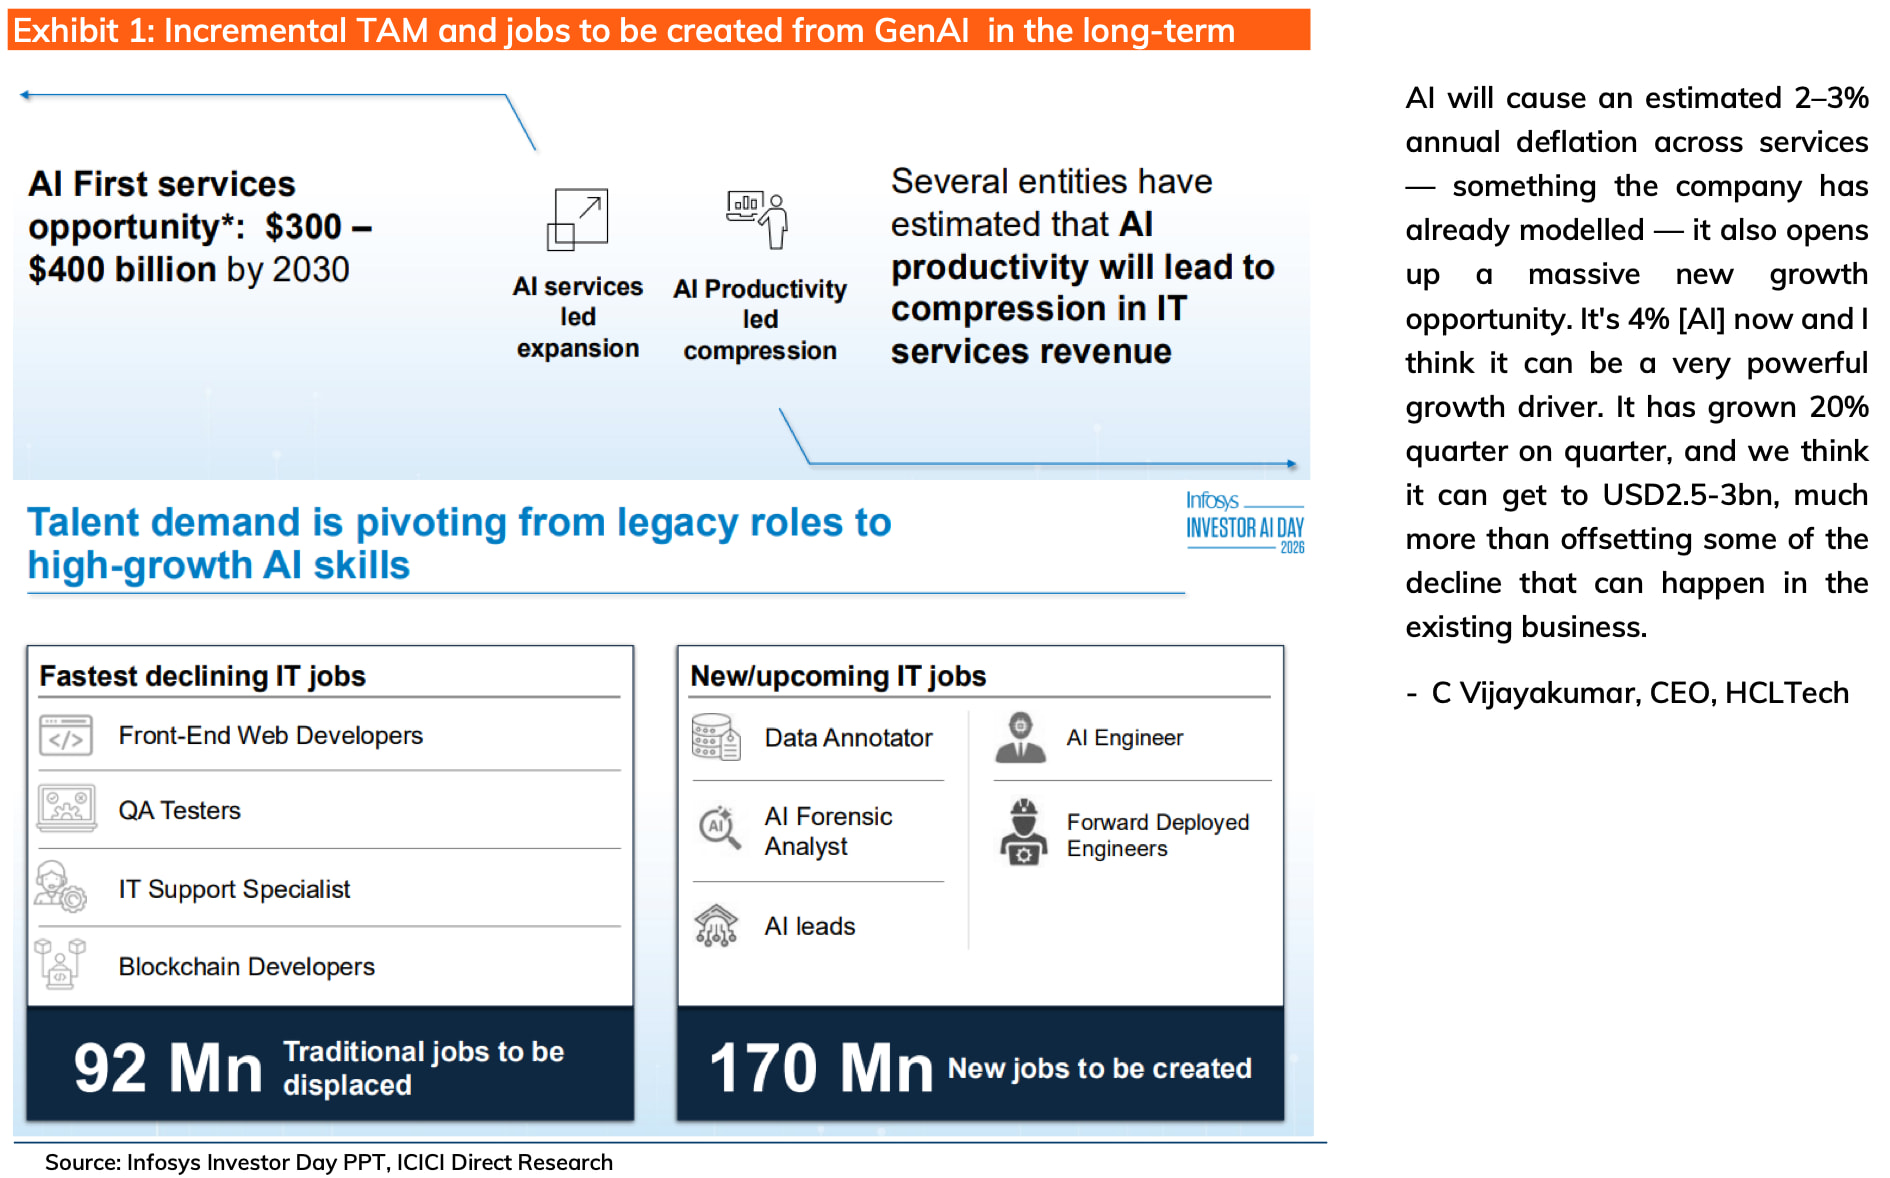
The AI Paradox: Why Traditional IT Services May Thrive, Not Die

A few thoughts on the threads since my last post.

On AI capex sustainability (Deven): Cash side is largely settled. Most recent FY numbers for the four big hyperscalers:

Combined CFO $557B vs capex $360B and capital returns $129B, with $427B cash on balance sheets and D/E between 0.12x and 0.27x. CFO comfortably covers capex + buybacks + dividends. The open question is ROI, not fundability. The bet is that AI capex feeds cloud (50-60% gross margins), and Google’s just-released Q1 2026 numbers are an early datapoint that the flywheel is showing up: Google Cloud revenue $20.0B, up 63% YoY, with operating income tripling from $2.2B to $6.6B. Cloud backlog nearly doubled QoQ to over $460B, and Pichai called out enterprise AI solutions as the primary growth driver for the first time. If that pattern holds across hyperscalers, the capex pays for itself many times over. If it stalls, capex plans get cut. That is the signal to watch.

On the LLM-dead-end video (Vivek_Shetty): Worth being precise. The video isn’t saying LLMs don’t work, it’s saying LLMs can’t lead to AGI. Different claims, and the AGI one is irrelevant to whether IT services get disrupted. The Sikka paper it references only shows an LLM can do a bounded amount of computation per forward pass; that’s nearly trivial and says nothing about chain-of-thought, which is where frontier models are now. Current LLM capability is already enough to disrupt parts of the IT services value chain, AGI or not.

3 Likes

Yes, they will be disrupted the same way YouTube disrupted traditional TV/News/Movies. It will democratize code and level the playing field.

Complex projects / movies are still mainly done by bigwigs, while the tasks that are lower in value chain is up for grabs, its gonna be a brutal pricing war in that segment. Overall it’s gonna be like 2000s again, the companies adapt and reinvent themselves will thrive.

Unfortunately we’re not partying like it’s 1999 when it comes to stock prices.

Couple of days ago, an AWS executive publicly called out the views of Infosys co-founders Nandan Nilekani and Narayana Murthy “outdated” — arguing that their incremental, services-first mindset could push India “into a ditch” in the 21st century. Instead, he says the country needs “more Vishal Sikkas” and leaders willing to bet on building powerful, homegrown AI models.

3 Likes

I would tend to agree. Ruchir Sharma has also mentioned that, India has already lost AI innovation in comparison to USA and China and only building data centers and AI based applications, and Need to innovate rapidly.

Next century may not reward only hard work but it will reward smart innovation and out-of-the-box thinking, and our IT leaders are still only taking small steps. At national level, only large population will not able to take economy forward, but “Science based innovation” is needed.

Only building hardware, to me, is not necessarily moving forward.

I may be wrong in my analysis. (ex IT professional).

1 Like

Anthropic announced today that they are launching their own AI services company to help deploy AI in companies, i.e. compete directly with traditional IT service providers. They claim that this is focused on smaller firms and large IT consulting companies will serve the enterprise, but every SMB software business goes after mid market and enterprise customers eventually. How is this not massively bearish for IT services?

Why we’re building this

Putting Claude to work in an organization’s core operations takes hands-on engineering and deep familiarity with how each business runs. Systems integrators in the Claude Partner Network lead that work for the world’s largest enterprises today, and we are continuing to invest deeply in those partnerships as Claude reaches more customers. This new firm extends that delivery capacity further. Companies from community banks to mid-sized manufacturers and regional health systems stand to gain from AI, but lack the in-house resources to build and run frontier deployments.

“Enterprise demand for Claude is significantly outpacing any single delivery model. Our partnerships with the world’s leading systems integrators are central to how Claude reaches large enterprises,” said Krishna Rao, Chief Financial Officer of Anthropic. “This new firm brings additional operating capability to the ecosystem and capital from leading alternative asset managers. We are proud to build it alongside Blackstone, Hellman & Friedman, Goldman Sachs, and our other partners.”

6 Likes

Hi team, I wanted to share some thoughts, I’ve been pondering over this for a while, but been stupidly lazy to sit and write this down. But got some time now so here goes:

Before that, Disc: took a position in Infosys recently.

First thoughts, companies like meta, microsoft, google, and amazon were traditionally seen as asset light firms, and that was their moat. But of late over the last few years - all that free cash flow generation has been going into building data centre - hyperscalers

So that ease of mobility isn’t the same. With these investments - they’re going to be having payback periods but the GPUs being used for these hyperscalers are depreciating very fast, so at some point this large scale of investment has the risk of being obsolete. If one were to follow Moore’s law (transistors in the chips keep doubling) then eventually higher computing power will be available for cheaper prices sooner or later, and at that poitn data centre payback periods may increase.
Currently capital is easily available from private equity - investors like what they’re seeing so firms like blackstone etc find it easier to raise capital for such “AI” projects. This AI boom is mainly funded by equity privately owned.

Hence that risk may get tranferred when Open AI and Anthropic comes out with their IPOs.

The risk here is not complete destruction of value but rather - just a small slowdown or change in expectations can take the valuations from the sky down to earth. More possible when equity is listed as compared to private markets.

Case in point: please watch Mark Cuban’s argument that OpenAI will never be able to pay back the trillion they’re raising. https://www.youtube.com/watch?v=oEVHNvE_jDw

But yes - if one believes in the growth of AI - then they must also equally believe that what you see today isn’t the final stage - and there is more yet to come. In such a scenario - it would be unwise to bet on a single LLM or a single chipmaker without knowing the future. Too much innovation related risk.

And this is what Indian IT Firms have done actually! Infosys has Topaz, TCS has TCS WisdomNext. Basically indian firms have tried to formalise the AI integration process - using multiple different AI models - so as and when a better tool is available that can be easily integrated through this platform. yes indian firms are trying to stay relevant. TCS is the only big Indian IT firm which has set aside funds for investments in Data centres (project called HyperVault) over next 5/7 years, this will be asset heavy and will dilute their above average return ratios.

(If you watched the Mark Cuban interview, you’d notice he praises Apple - they have gadgets that can adopt the winner of the AI race. They’re uniquely positioned for this. Indian IT firms can also be thought of in a very similar manner, it’s not gadgets but rather enterprise integration expertise, that’ can employ the winner of the AI race.)

But pureplay AI firms already have risk-on from their capex heavy investments, and they would rather outsource the integration part to service firms. I think Indian IT has taken the right decision, and I’m glad. (I stick to this despite the small intiatives from Anthropic and OpenAI to set up integration from their end for enterprises).

(Another example: Anthropic had created an AI based HRMS, but Workday CEO claimed that despite having created this, Anthropic with its small team still used workday as its HRMS ironically)

Social media points to Mr Murthy and other leaders not being innovative enough but it’s not a lack of risk - but they’ve done a good job protecting shareholder money without taking a risk into the unknown. For that kind of risk - they have their own VC firms like catamaran, etc.

So doing buybacks, and slowly acquiring niche firms is the way to navigate unknown territory whilst also keeping yourself relevant to clients by providing AI integration tools. Legacy systems is the key word here because there is so much complex minute data for all these businesses that it’s really hard to immediately put on to an LLM and expect automatic integration - that will cause more harm than benefit. So this is a long drawn process, and reimaging how this can be done will generate more revenue streams for service providers.

A sepculative guess here - by partnering directly with AI only firms - you also the run the risk of sharing all your data, and them learning from private data, which many firms would rather avoid, hence bringing a trustworthy IT firm - with long standing domain expertise and relationships is key.

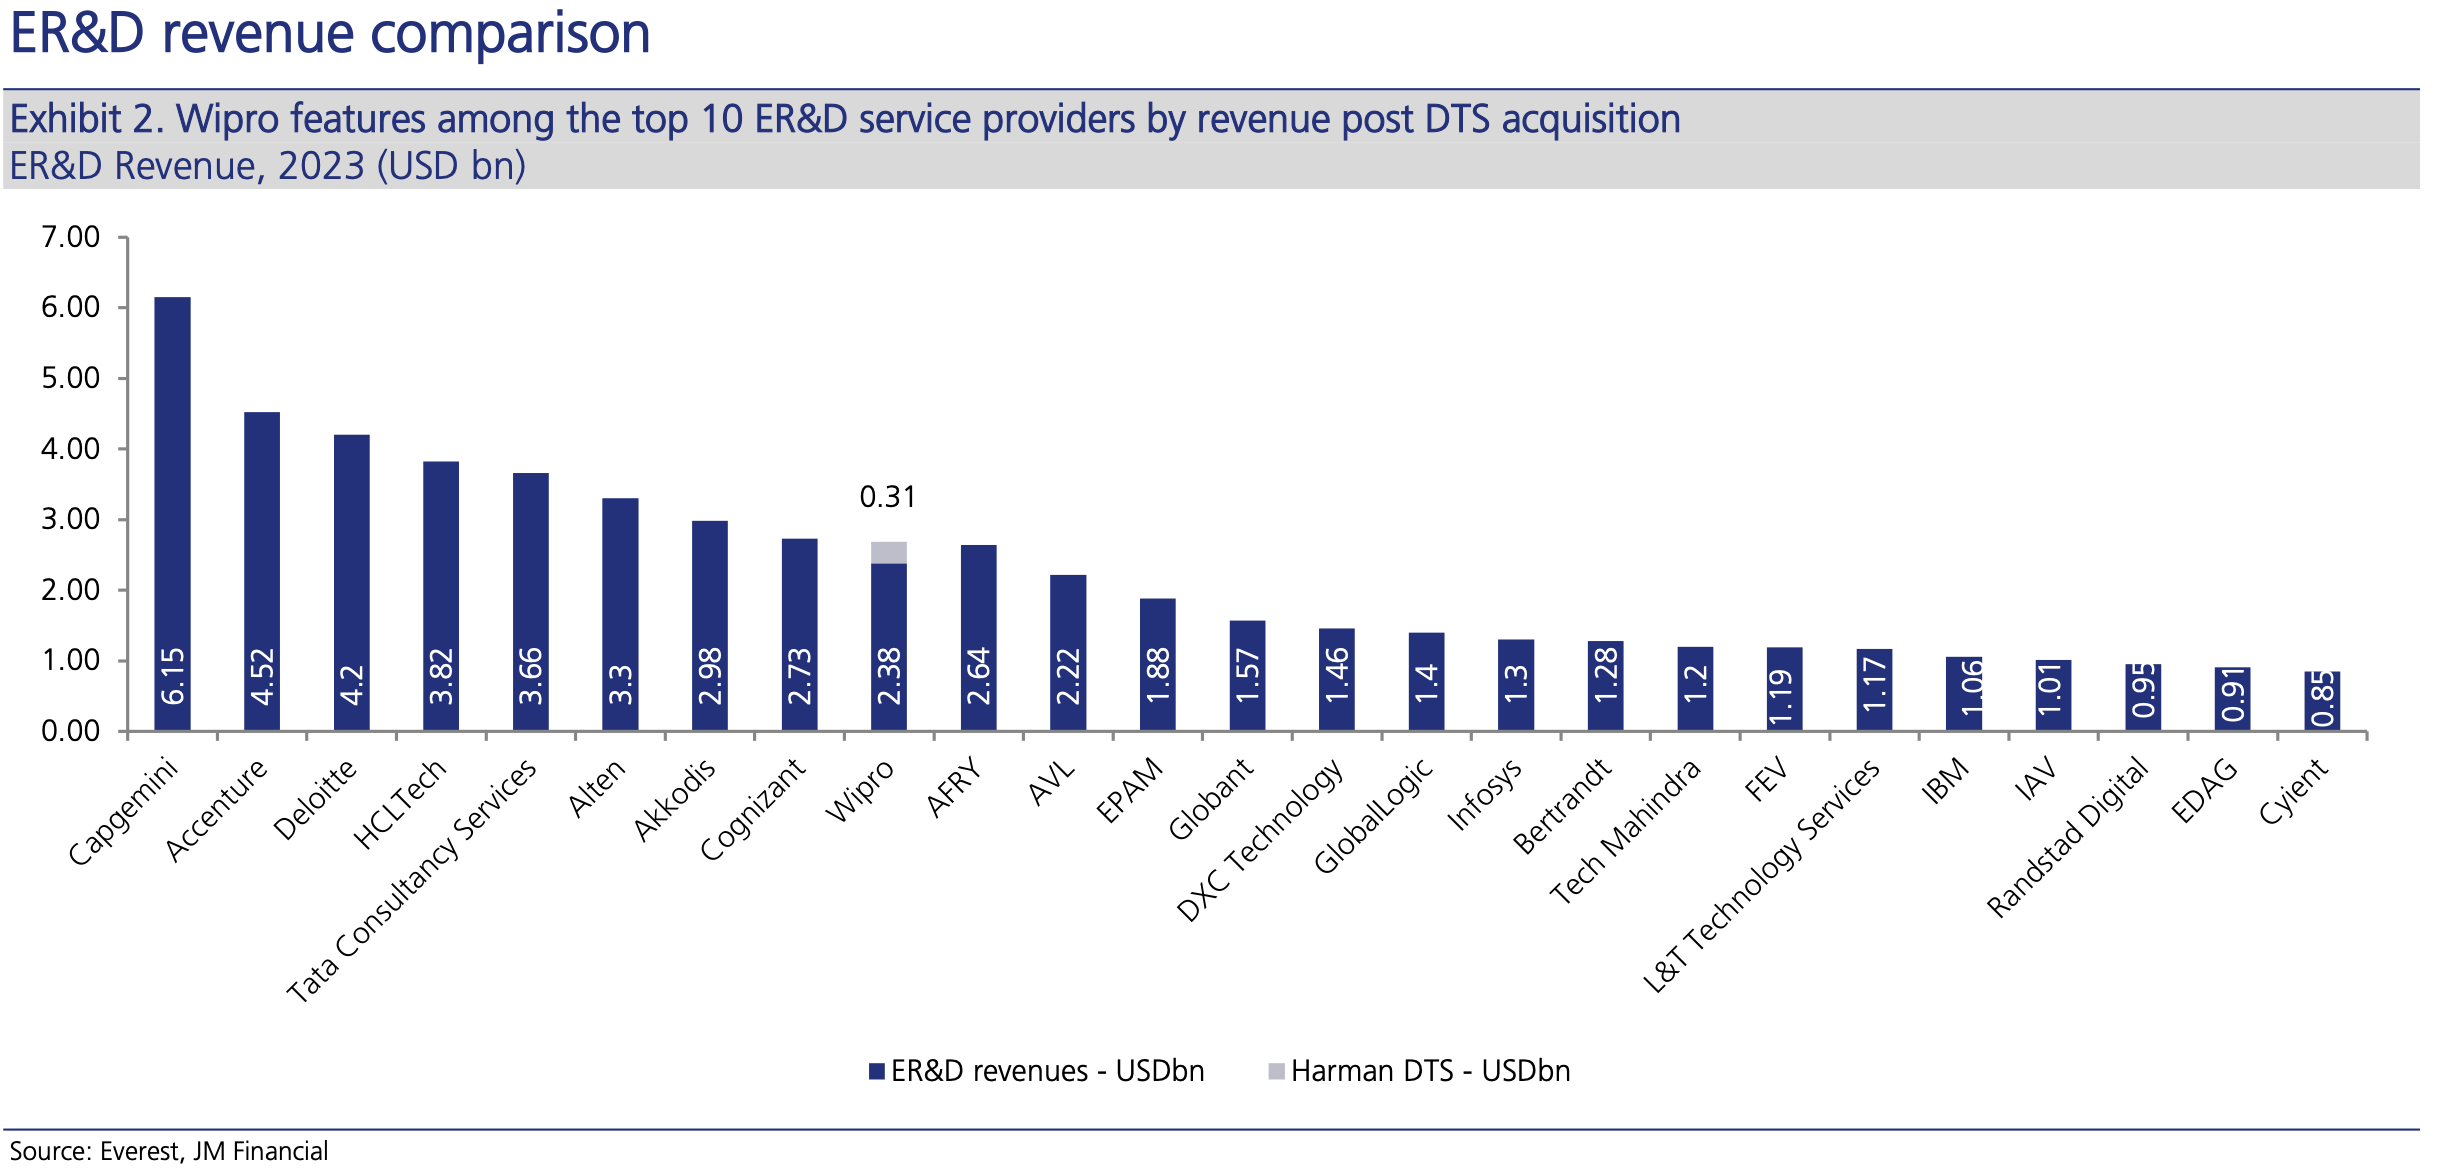
Another segment that is compeltely being ignored is the Engineering R&D department. Indian IT firms are split into IT services and Engineering R&D firms. For example LTI Mindtree is entirely IT service based but LTTS is a pure play E R&D firm. Amongst the big players, HCL, TCS, Wipro and Infy have sizeable E R&D department in this descending order as of 2023.

Considering what I know about E R&D, it involves physical and digital. You are talking about supporting firms to develop their patenta in medical, oil/gas, automation across the manufacturing space etc. You help them design, and verify at multiple stages. This segment is not going to be affected by AI in the literal sense as we are seeing right now. It will be augmented by AI, but not displaced by AI.
A key aspect to note is what acqusitions are IT firms doing at the moment:
Wirpo bought Harman DTS - a key E R&D player based in US.

HCL Tech acquired - ASAP group specialising in e-mobility

Infosys has purchased the most in the e R&D space ramping up their focus over here.
Kaleidoscope - firm specialising in medical devices and other highly specialsied industrial gadgets (worked with canon medical, P&G etc)
InSemi - contrary to the notion that no indian it firm acquires Indian startups - here is some change. InSemi is an indian semiconductor chip design firm.
InTech - A german firm sepcialising in software and electronics e r&d for Automotive, Railway and Smart Industries (e-mobility and autonomous driving)

Mr Pareekh Jain founder of EIIRTrend, provides insights into what’s happening in the IT industry, and I found this data to be useful.

Indian engineering services revenue growth

Reserve the right to be wrong :)
11 Likes

Moore’s law is a marketing gimmick, not a law of physics.

Apart from that, very good write up​:+1:

1 Like

I am also beginning to think the current capabilities of AI are grossly overstated. Domain expertise and private/proprietary data will be strong moats. And percolation of AI usage to enterprises will take time and the services industry’s involvement.

The video above explain how the math behind AI replacing white collar jobs doesn’t add up.

1 Like

Amazon operates a dual platform where it functions both as a retailer selling its own private-label products and as a marketplace for third-party sellers. This created an environment of intense competition where Amazon utilized supplier and seller data to identify high-demand products, subsequently launching its own competing versions at lower prices.

1 Like

Would also like to add with AI - coding gets cheaper, (AI in itself will get cheaper), the demand for these IT services should incrementally go up.
Just heard about Jevon’s paradox from Rajiv Thakker, and I think it hold its case historically.
Historically as efficiency has increased, the use of that resource has increased contrary to expectations that the resource use will be limited. In this case the resource is referring to Indian IT services, as they pass on the cost benefits from adopting AI in their own processes.

3 Likes

AI may not be actually getting cheaper due to huge capex and investments required and the investors will ask for some return such huge investments.

It may turnout that AI eventually comes out as an expensive utility and humans and cos who use it smartly and with token efficiency will make most of it.

Traditional businesses will require such an expertise from IT companies. The pie of IT companies may grow overall with AI being a compulsory element in the business on both cost side and delivery / revenue side.

4 Likes

So as it turns out of luck, this trade looks like starting to churn positively in my favour. Disclosure : I hold mid cap IT names around 8% weight in my portfolio and mostly after the current rise I am at breakeven to my investment amount.

I may have missed it but can you disclose your IT holdings please?

Looks like my call is utterly wrong. Market is supreme, the businesses may have really disrupted.

I also sold all the positions today at breakeven in total to my cost. Happy to correct my mistakes.

Although this selling may also turn out to be a mistake but be it, I am fine with what I have thought now from the disruption angle of IT.

1 Like

Either ways it is better to buy US listed companies. IT services at 10 PE. It is still expensive in India.

2 Likes

Yes. Does anyone know why Indian IT peers always trade at a premium to Accenture?

I was expecting a bigger fall today but it seems flows are managing the index well and preventing deeper corrections.

Not exactly peer in size. I have been tracking infobeans from some time but did not deep dive yet. Whats interesting is this small cap player has suddenly >doubled pat in fy26 and showing ~>30% sales growth from past three quarters. I listened to one of its concall and promoter clearly said they will not build any products but rather focus on AI led services only. Could be all smoke but worth taking a look?

Update: past few days makes me think IT is untouchable for some time. Market is such its rewarding expensive stocks while punishing cheap. IT looks lucrative but opportunity cost needs to be considered

1 Like

Due to indian market + other factors.

HUL PE 34 vs Unilever 20
LG Korea 39 vs LG India 66
Suzuki 8.4 vs Maruti S 28.7

Indian IT companies taking market share from outside IT companies which includes accenture, cognizent etc. Typical 10 years growth of infy, tcs and acn is like 11, 10 and 9, cogni is very low. Margin is also high of Indian IT, like 25 of tcs vs 15 of acn (appro).

3 Likes

Also, at Global level, there are lot of Tech Stocks available for investing. Accenture may have a small % in Global Indices.

Where as TCS, INFOSYS, HCL TECH are part of NIFTY and SENSEX, so many Index funds have to buy these stocks irrespective of their recent performance. Their cash flow is also generally consistent for long term, with high dividend yield.

Now, whether this scenario remains or change, is what every one is currently trying to understand.

1 Like

If one reads Accenture’s commentary - none of the slowdown is attributed to AI taking away jobs or work. It’s mostly a macro issue, some part of it owing to the ME crisis and US government related contracts.

Rather they’re quite optimistic on AI related revenues just like Indian IT firms. You could say that’s just company management avoiding a massive share price drop by stating oblivion. But if anything should supplement this information - they added to their head count → 2% growth!

Commentary from brokerages is also quite positive with a few expressing caution.

Most firms are currently delaying deals due to a slowdown - there is a slowdown everywhere except for the AI related investment space.

I do believe the sell-off was majorly fear driven, core value funds are adding Infosys significantly and right now we might be early in adding position - there may or may not be more downside but it is definitely undervalued today.

I don’t know of any single AI company that is profitable or Data centre project that is profitable yet. Plus the US 30Y hitting 5.2% highest since 2007 (19 years) is a major threat for all the funding that has gone for the datacentres.
Someday people will ask for their money back and that’s when everything may bite.

As you probably understood I’m biased, and invested.
Even accenture seems like a good buy at the moment.

8 Likes

A good read