Shivalik Bimetal Controls Ltd (SBCL)

So longevity of the designs are more than 15 years as a typical vehicle platform exists for 10-15 years. What changes are shapes and sizes of the shunt resistor based on battery pack design / power requirements / environmental factors etc.

ISA have 500-600 SKUs of shunt design. They used to patent this design at a discussion stage which became extremely inconvinient for the OEMs whenever they need to do slight modification or change the source. That is where new players like SBCL become extremely important from IP perspective.

Another thing to note is whenever a new shunt order or a design modification order comes, SBCL charges a tooling cost on that prototyping. Sometimes same OEM gives the order to multiple tier 1 and the tier 1 sends the same order to a few player. I came across an interesting instance where SBCL got the same prototyping order from 3 different Tier 1s.

The design, to approval to large volume delivery takes around 2-3 years as there are rigorous lifetime tests done on the components.

@Donald da, The module part is still unclear to me on whether they would become a full fleged module supplier. But it seems that the company is taking early steps towards becoming atleast a contract manufacturer for module components. Studying Tier 1s design freeze are a bit complicated at these stage as the SKUs would be even larger and there are no public information of it. These are custom tuned to the product’s requirment.

On the results with the US election and hopefully a significant policy push towards electrification, I feel that we will see good demand coming through in next 2-3 years.

Disc : I belong to this industry and significantly biased.

14 Likes

So, Metalor JV is off. Company will be dependent on just two products in the near future, atleast.

3 Likes

The company will still generate significant cash flows to go for some other venture in future. It’s good that they are weighing all possible options and not just jumping into the very first thing that they can lay hands on.
Though it may seem conservative, this cautious approach will be a saviour when economic slowdown patches are to be tackled.

I also don’t see any fault in going back on a decision that’s been taken just because an announcement had been made, as long as it benefits the company in the long run.

It may also have happened due to the change of management and their strategic vision for the company.

I specifically asked this so that they clarify to the entire community.

14 Likes

Q3 FY 25 Concall highlights:
•Bimetals saw growth in americas,while shunt showed degrowth.India saw good growth in shunt business owing to increased domestic manufacturing of relays.
•Looking for Forward integration in shunt business
1)Component to subassembly
2)Shunt strip to component
This will start contributing from next FY
•US customers are giving guidance on gradual recovery from Q4 in shunt business.
•Our customers wanted us to do Forward integration as subassembly is not their core business.
•Revenue from subassembly is 10x of that from shunt.Margins are similar to current ones in some category while in others they are higher.Due to this,we expect shunt revenue to more than double over next 2 years.
•There will also be newer customers who are willing to procure only as subassembly.
•Strip to component forward integration:
Expect revenue to be 2x(from 60 cr existing to 120 cr) with margins increasing by 4%.supply to start from April.
•Doing backward integration in some components to reduce cost and lead time.Not looking at forward integration in bimetals as it is commoditized.
•Almost 30% relays are now made in India ,rest are imported.Import should go down as more domestic capacity is coming up.we are sole supplier of shunts to domestic players.
•Even if EV 4W does not grow, we expect shunts to grow as even today majority of our shunts go into ICE,hybrid and 2W EV.Expect India 2W EV segment to show good growth .

My take:
1)Forward integration will create new chapter in company’s growth story.
But it will take time. They will not be able to convert all component sales to subassembly as currently component sales are 140 cr and if all were to get converted to subassembly,revenue guidance over next 2 years would have been 3-4x.but they have guided for 2x.so I feel forward integration will be limited
2) Smart meter have done really well and should continue this trajectory.
3)If they say that Indian 2W EV market should give good growth,even in past 3-4 years,2W EV have seen very good growth but shivalik did not have any growth in domestic shunt business apart from smart meter.why is it so?

Disclaimer:Invested at average price of 35.No transaction in past 30 days

14 Likes

Q3FY25 concall gave very interesting glimpses on the direction that the management wants to take with regards to shunts. I would highlight those as

  1. Backward Integration
  2. Forward Integration
  3. customer profiles

Backward Integration
It is good that the company has started to integrate backward to develop suppliers for metals and alloys for their specification. This is a long journey and can lead to many wonderful results. The most obvious is the Inventory days can reduce from 200 odd days to say less than 50 days ( This is my assumption). This allows the company to handle demand and supply shocks which puts them on a better footing via their Partners especially in a down cycle.

The second benefit of backward integration is the expertise in alloying which I believe is the heart of shunts. If they are able to make alloys and generate various material for different applications, they would be in a much stronger footing and this would also make them similar to issabellanhutte. Knowledge of alloy in this business is important as shunts are sensitive to temperatures and environment conditions. The more a shunt remains unaffected in the operating range ( i.e. the resistance does not change ) the accurate it becomes for current measurement.

But making alloys are tough but hopefully SBCL will be able to make some headway.

Forward Integration
This is what excites me the most, and I observed the excitement in the con-call participants as well. At present Shivalik buys alloys of a certain dimension, cuts them into strips, join the alloy with copper and then machines them.

Then they send this shunt to a Tier 2 or Tier 1 who would fit them in a module to make a current sensing module ( for larger batteries) or it can be directly put as a part of BMS ( usually in smaller batteries)

for more reading on this topic

What Shivalik said was that they will start to produce some of these modules which puts them in the league of the TIER - 2 s. Off course it is not clear if they will also buy the PCB or start to work on the PCB. I would go with the buying part as it seems that the management is taking small but focused steps towards value addition.

The obvious benefits of such forward integration is increase in Topline . A shunt sells for say 50 rupees and a module would sell for say 500. The margins of the shunt is 20% but the margin for modules probably would not be 20%, maybe close to 10% ( I am telling this from experience, but management thinks otherwise ). Also in case of very low volumes of say 5000 components, margins can be huge (25-30%) but that is materially insignificant to the company. I would put that as prototyping.

What interests me is that this gives them the opportunity to be a part of the product development cycle. Shivalik is already well known to work with Tier-1s to improve shunt designs and reduce cost ( 10 rupee reduction in cost for a volume of 1 Cr is 10 Cr in savings , In high volume business such small innovation can really impact the entire value chain ). I believe that as they give themselves more time towards the forward integration they will start to build more knowledge as a contract manufacturer and who knows at some point develop shunt modules themselves.

Now why would the customers want such capability from Shivalik. The obvious one is that it reduce their hassle of procuring parts from multiple vendors and then have quality assessments in every place. The activity from shunt to module will require at this stage only to do some soldering and fitment activities. Shivalik is probably very well placed to do so and is happy to do it. For quantities below 10000 it is probably a no brainer as the customer will most likely buy a out of the box BMS / Current sensing module.

My Concerns

  1. Solan as a location is not very convenient. Yes they might get cheap labor but in such a high margin and TAM business, should labor cost be your concern. I feel they should have facilities around Industrial hubs of South and North India.
  2. They should have their design centers in Bangalore / Hyderabad / Gurgaon . They must attract high quality talent if they want to do good in both metallurgy and EMS
  3. Hope they do not get distracted from the core objective of making shunts and start to build narrative about forward and backward integration.

Also my BIASED view of the Industry
At present the adoption of EVs has sort of plateaued ( and in some cases declining ) but this change is inevitable from a technological stand point. Imagine our Cars which are becoming technology rich with every passing day, these electronics needs power and the current source of power is the 12V Lead acid battery. The easiest way to increase power is to replace the lead acid battery by lithium ion batteries. Thus you need a BMS ad hence a shunt
The next part of the puzzle is the regulation and narrative around clean air and PM2.5 particles. Again, the hardest way is that you have a great exhaust system and filter the air out. This is expensive and beyond a point not effective
The easiest way is that you can simply improve the quality of emissions by the ICE engines by running it in the most optimum range. You can adjust the optimum range using battery as a source of power. When car is is idling you can charge your battery, when the car demands power you can discharge your battery . Thus you need a battery and motors and inverters → 6+ shunts

Finally 2W EV in domestic space has been quite popular and convenient, which would also keep a demand for shunts. As charging infra gets set up ( I am observing that as I am using an ev ) a lot of range related issues will go away. On top of that there is the battery as service ( BASS ) into play. I feel entrepreneurs can be really creative when it comes to EVs and there could be 2 and 3 W in different form factors suiting to customer needs. This segment will drive the usage of custom modules and I hope Shivalik will be able to capitalize on that oppurtunity

So my view still is that it is not gloom and doom and some regulations will start to kick in like CAFE Norms and CARB norms which will make it impossible to sell pure ICE cars.

49 Likes

Shivalik Bimetals: Forward and Backward Integration Strategy Overview

Key Points:

  • Forward Integration:

    • Shivalik is transitioning from supplying shunts to providing finished assemblies for battery management systems.
    • A $2 shunt component can be sold as a finished assembly for $20 to $30, indicating a potential tenfold increase in value.
    • Targeting 20-25% of business conversion in the first year could lead to more than double the current revenue from the shunt business within two years.
    • Contracts have been signed with two key customers for converting strip materials to components, with regular business expected to commence in April 2025.
  • Backward Integration:

    • The company is exploring in-house processing of raw materials (e.g., alloys, copper) instead of purchasing them in finished form.
    • This strategy aims to reduce costs and lead times, enhancing supply chain efficiency.
    • The required investments for this backward integration are not expected to be significant.

These strategic moves are designed to enhance profitability and operational efficiency, positioning Shivalik Bimetals for future growth.

4 Likes

Few questions for forward integration

  1. is it only assembly of parts in which case value addition will be only for assembling.
  2. what type of components go in subaasembly? What is the technical know how required to make it ?
  3. can they make it in existing location or require new factory?
2 Likes

I visited Shivalik’s stall at Elecrama, Greater Noida yesterday. I spoke to one of their Business Representative. On talking about what new your company is doing? He showed me some of assemblies which are forward integrated. So they are taking the work from their existing customers and offering them complete assembly rather than small connector / shunts. To me it was quite convincing from their customers point of view. However their quality and cost competitiveness will matter. But knowing Shivalik’s management, they should definitely be able to progress in this. I have also worked with a Car Manufacturing company and at supplier companies as well. This process of forward integration followed by many suppliers to grow big. And more than any thing… relationship, technical competency and quality wins.

24 Likes

With regards to your view on margins in forward integration being around 10%,mgmt has said in concall that bought out component cost would be 55-60%(in line with current RM cost).So if GM is 40%, they can easily do 20% at ebitda level.Or am I missing something ?

Secondly,mgmt is bullish on Indian 2W segment.But what I don’t understand is last year almost 19laks 2W EV’s were sold in India and still shivalik hardly has any revenue from it.why so?Could it be that like in case of relays for smart meter,in ev also entire BMS is getting imported and thus leaving very less space for shivalik?

7 Likes

Company came out with US tariff impact assessment note. Ghumman family trying to be more transparent with the investor community. This will help the company in the long run

15 Likes

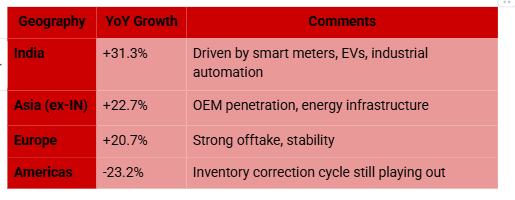
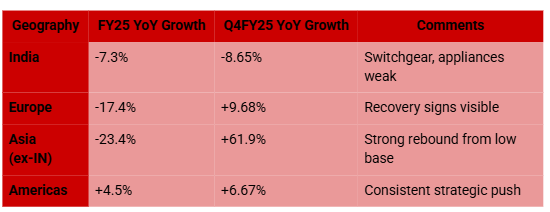
Shivalik Bimetal Controls Ltd (SBCL) – Q4FY25 & FY25 Earnings Review

Summary:

Solid margin-led recovery in Q4FY25, driven by Shunt Resistor outperformance, even as topline remained flat for the year. EBITDA margins held strong, cash flows healthy, and early signs of bimetal recovery suggest FY26 could turn the corner.


Volume growth: 6.16% | Value growth: 3.68%

Strong momentum with export diversification (Europe, Asia up), US stabilizing.


:wrench: Thermostatic Bimetals / Trimetals (51% of FY25 revenue)

Still soft overall but Q4 shows first signs of volume-led rebound — especially in Asia.

Commentary

FY25 was about profit preservation in a flat topline environment. Margins were protected through operational efficiency. Net cash, 24.6% ROCE, and disciplined working capital are highlights.

Regional divergence: India/Asia performing well; bimetals muted in Americas. Diversification strategy working — shunts now nearly 50% of revenue. Forward integration and product customization in focus.

:round_pushpin:Topic :key: Key Takeaway
Shunt Business Core growth engine; gaining volumes and export traction
Bimetal Business Drag in FY25, but green shoots visible in Q4
FY25 Performance Flat topline, strong margins, high cash conversion
FY26 Outlook Cautious optimism — growth led by shunt, product innovation, and regional normalization
Capital Allocation Disciplined opex, steady dividend, low debt — supports sustainable growth thesis
Strategic Levers Product innovation (smart sensors), forward integration, localization, lean execution
13 Likes

I never quite understood the premium that this company trades at considering the growth, management giving unrealistic guidance and being exposed to so many macro factors.

5 Likes

You’re not paying for what it earns today — you’re paying for the fact that it earns consistently, with control, and has the tools to scale TAM and margin without diluting capital or control.

1. Technology-Led Moat in Critical Components

  • SBCL is among the very few global players with proprietary Electron Beam Welding (EBW) and Diffusion Bonding tech — these are not easily replicable.
  • The company builds its own machines, halving capex costs and improving lead times — a rare edge in manufacturing.
  • This technical insulation, not sheer scale, earns it pricing power and sticky OEM relationships (20+ years in many cases).

2. Global Relevance with Asset-Light Scaling

  • Operates in mission-critical components for EV BMS, smart meters, and switchgear — all tied to global electrification.
  • Does not own massive plants overseas but supplies to 300+ OEMs across 38 countries, making it a “small giant” — light on assets, heavy on IP and process control.

3. Forward Integration = Margin & TAM Expansion

  • The ₹150 Cr forward-integration opportunity (PCBA, sensors, assemblies) moves them up the value chain — from component supplier to solution partner.
  • These products carry 40%+ margins, which the market is already partially pricing in — and rightly so.

4. Premium Is for Stability in a Volatile World

  • It’s not that SBCL is immune to macro factors — but it has historically managed to protect EBITDA margins and remain net cash, even when revenue declined.

Sorry but think of it as a long term stock and not a momentum stock where u rush in and out.

14 Likes

Shivalik has no exposure to rare earth magnets. You are once again storifying the stock!

The stock that has exposure is Permanent Magnets.

14 Likes

And even permanent magnets has clarified that they are dependent on Chinese govt. rules for rare earth magnets. I don’t think they are going to get any knowledge transfer from their Chinese JV and even they admit that things are in nascent stages.

The management of this company has been singing the same story since I first read their con call in 2023 with no growth in sales or margins. While other smart meter themed companies are posting superb numbers.

1 Like
2 Likes

In recent concall management has clarified that Shivalik’s sale has no direct correlation with smart meters orders but to the number of switching relays manufactured in the country for the smart meters. In the past, almost 80% of the relays were imported from outside (mainly China) and hence inspite of huge smart meter installations, Shivalik has not benefitted to that extent. Now things are changing. More and more companies are assembling relays in India and this means more Shivalik shunts are being used. Management expects exactly opposite picture (80% make in India, 20% imported) for switching relays in next 2-3 years time.

22 Likes

Anyone who attended the latest AGM. The BSE disclosure of AGM doesn’t cover the entire story what someone would have learnt being present there. Please share the notes.

1 Like

My Notes: FY2025 AGM held on 16 September 2025

FY25 was challenging year but that assisted company to prove its character to face adverse enviroment and manage business in difficult times. Despite difficult business environments, the company continue to generate positive cashflow and continue to pursue key development work in Research activity. The company is second best globally based on precision standards fulfilled by products it manufactured, while US based company being the best. The company is pursuing its efforts and expect to become the best company globally in meeting precision parameters.

The key industry which company serve is automobile and energy. Automobile industry, particularly in EV subsequent, accuracy and high precision has become theme. The company PCB project is shaping well. It has improved on customer trust and supply chain sourcing. The management expect PCB assembly to contribute major growth driver from Q4FY2026.

The consolidation of control in promoter holding and control since last AGM has shaped well. Shivalik 2.0 now attempting to move in new horizon with focus on R&D to develop new product addressing newer segment. Previous efforts in Shivalik research were mainly to improve quality of existing products and was not looking at developing new products. Shivalik is setting up new centre of excellence and Research centre is NCR.

The new research centre would attempt to develop new products depending on customer feedback. Also, the company would focus on to emerge electronic solution provider to its customer in Shivalik 2.0. Two-wheeler market development and increase EV penetration in passenger vehicle would be main driver for shunt in Auto segment in medium term India. In Smart meter, with increase indigenous relay manufacturing, Shivalik emerged as only Indian supplier to provide shunt. Currently, nearly 25-30% Smart meters use Indigenous relay while balance is imported mainly from China. As government develop BIS standards from meter and increased focus on Made in India, share of domestic relay manufacturing will increase and that shall result in higher demand for Shunt from Smart meter.

Shivalik operational efficiency improvement are focusing on various parameters like improving precision standard of products to focus on enhancing capability quick hyper scaling of production new design developed product once approved by customer. While phase 1 of Research centre would only focus on development of product with manufacturing operations carried in current manufacturing facilities, in medium term, phase 2 capex in research centre would also involve manufacturing facility pilot project in research centre. The day-to-day production efficiency efforts would be looked a separate group and second group focusing more on new segment development.

Shivalik 2.0 would change focus to system driven manufacturing while Shivalik 1.0 was driven mainly by availability skill set and internal manpower. In order to move to Shivalik 2.0, the company management is open to incur capex to build capability. Research centre is first step in that path.

The company has stopped outsource processing during FY25 which resulted in saving on Rs 5 cr saving. It instead focusses on developing internal capability. Also, many workmen which were on contract basis, were made permanent employee, which resulted in high employer attrition rate (almost 12% in FY25 as against 3% in FY24). Further, sale commission during FY25 also decline as company replaced outside agent and also changed contract which made commission based on sales linked replacing minimum threshold amount payable previously. Italy subsidiary set up was step in that direction to directly reach to customer.

China related development: Chinese customer can be divided in two segments. The Global MNC with manufacturing in China, Shivalik has well established due to their relationship in other geography and long record of superior quality. For the largest EV manufacturer, owned by Chinese public, the company has given sample which are under evaluation and company expect major gain once approval come.

Energy storage: Shivalik is focus to supply component that control power supply in battery. It does not intend to become battery solution provider. It may do some backward integration work to provide assemblies which directed used by Battey solution provider.

Developing local supply chain: Two major material used by Shivalik is Copper and nickel alloy. While copper requirement is of special grade given the high precision and performance requirement, copper is mainly imported from Asian counties. However, along with a vendor, Shivalik is attempting to source Nickle alloy from local supplier. The working is still at early stage. Once the output manufactured meet requirement of customer, it may replace nickel alloy imports.

CAN based shunt and Busbar solution are two new technical development. CAN based shunt provide online insight to Shivalik and its customer about performance of products. Busbar solution is mainly likely to address requirem8ent of electrical two-wheeler. Shivalik is already supply shunt for large EV passenger vehicle in India and expect to capture more share.

Shivalik recent capex are resulted in two new facilities. One which assist in assembly capabilities while second is for contact. The capacity is just started and expected to contribute meaningless fully after 9-18 months.

The key competitive advantage of Shivalik is its ability to internally design, process and Manufacuting with in-house tooling. These capabilities result in lower lead time and superior cost structure for the company. The management feel that they would continue to benefit from these in medium term and constant endeavour, it can become sustain competitive advantage for Shivalik.

In short term, Indian demand would be higher due to smart meter and increased EV penetration specially in two-wheeler, in long term, is expect Export to account for 70%.

Disclosure: Shivalik Bimetal is among my Top 3 equity investment holdings. My view may be biased due to my investment. I am not recommending any investment action to reader. I am not SEBI registered advisor. I may increase/decline/exit from my investment in the company without informing forum. No change in my holding in last 12 months

52 Likes

Busbar Connectors are becoming mainstream in 2wh EV. Traditional wiring arrangements are being replaced with modern busbar systems, which offer improved performance, reliability, and space efficiency. These advanced busbars are pivotal for next-generation EVs, providing a streamlined solution that supports higher voltages and power densities while reducing the overall vehicle weight.
Aug 2024 Sponsored piece from ISBH
Busbar construction for nextgen EVs

It may be instructive for us to familiarise ourselves with Busbar connectors as SBCL busbar connectors validation is on/through (?) with one of the top 3 EV vehicle manufacturers in India.

Relevant Excerpt from Aug 2025 Concall

Busbars & Battery Connectors
it’s completely new vertically. It does use our existing electron beam welding technology,
where it’s a set of different sizes and shapes of busbars that all combine into one unit, which is thenconnected to a cell pack, which would go into various types of two-wheeler, three wheeler applications.

What makes it also unique is being electron beam welded and having the flexibility of using different materials, electron beam welded together. You can then play around with various properties and parameters of a bus bar, which is otherwise not possible using a single, conventional type of busbars. These are, you know, they’ve gone through over the last, you know, months, it’s gone through various cycles of iterations and different types of variations have been made to the design, and it has now reached a stage where the finished facts have been sent to the customer.

They are under testing. We are now going for a small production lot, which we expect to complete within September, which will then go into further testing. So, it’s a little early to go into further details on this topic, but it is a brand new vertical. We are very aggressively working on it. And obviously, potentials are quite strong.

Initial addressable market size estimated at ₹2,000–2,500 crore, with SBCL targeting 10–15% (₹200–300 crore) in the first wave. Commercialisation is expected to begin in the next 1–2 years, with a dedicated R&D team and Centre of Excellence being set up to accelerate this vertical.

Specific mention of Busbars & Interconnects in Ola 2Wh battery pack teardown
@GourabPaul you may like to dig up more relevant pieces/educate us more.
Other domain experts please pitch in

29 Likes