
Stock is beaten left & Right even with 50% growth, seems Market did not like the margin drop or commentary from AC makers about the worst sales since 2008,m which us multi decade down tuen in Ac sector and Stallion is dependent on AC growth for after market growth..Looks good to buy at this price.
4 Likes
correct me if I am wrong, but my reading shows that Stallions clients include more than just AC. Hydrofluorocarbons (HFCs) and Hydrofluoroolefins (HFOs). These products are essential in various industries, including semiconductors, automotive, electronics, pharmaceuticals, fire suppression systems, and aerosol production.
1 Like
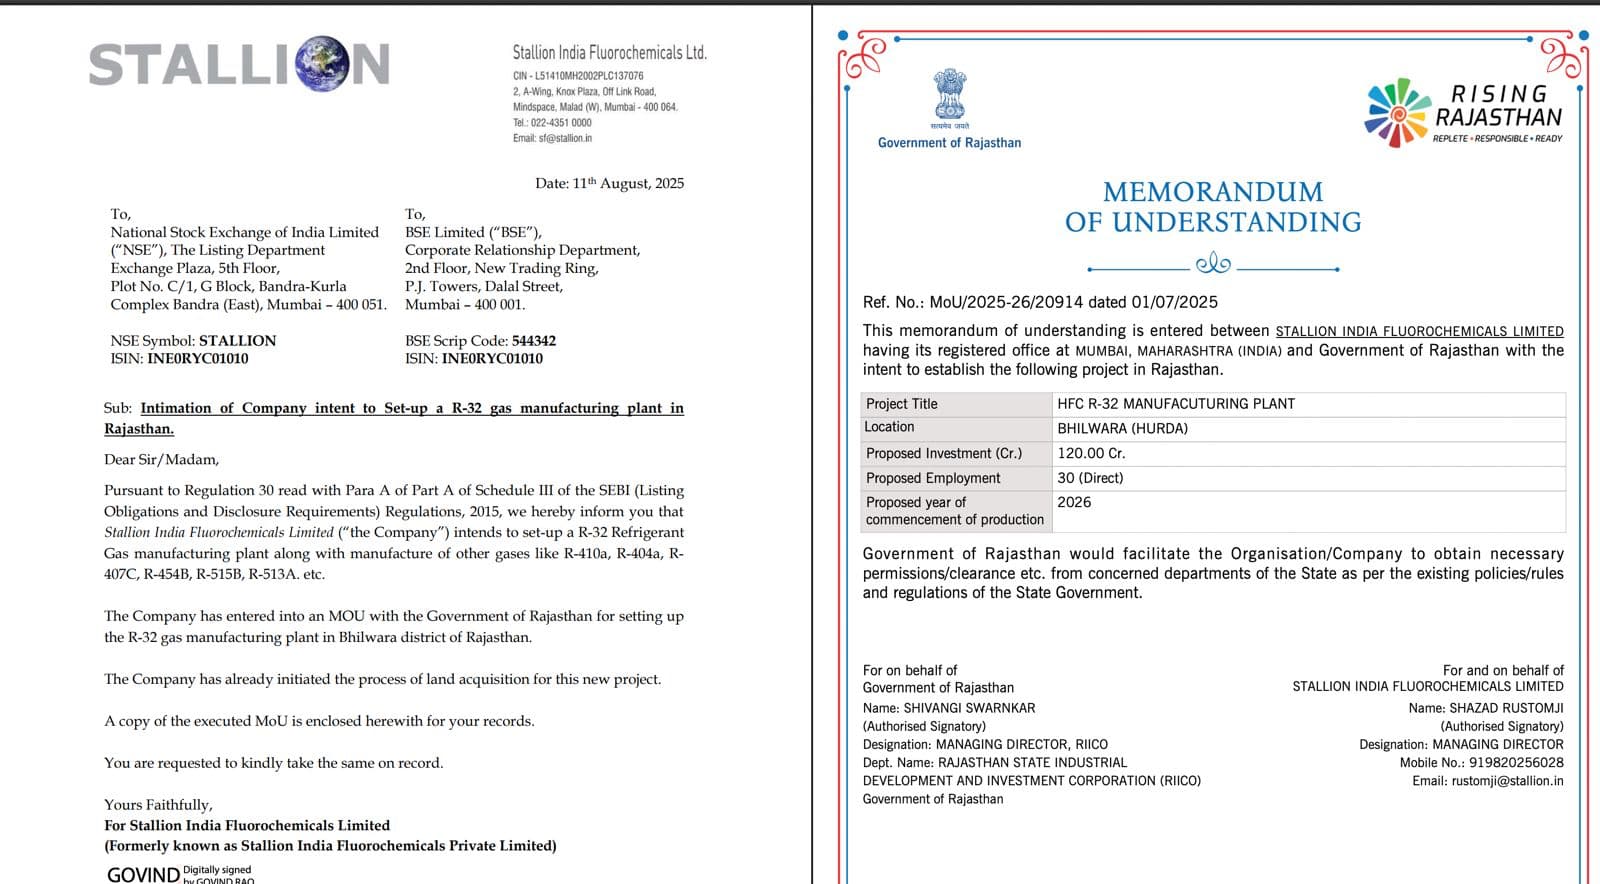
Good to see stallion progressing towards manufacturing more.
For now its just MOU which is not binding, need to monitor how this progresses.
9 Likes
Stallion India FY26 Q1 con-call highlights:
Business is seasonal and Q1 and Q2 are usually lower and q3 and q4 are the highest in revenue generation.
Bhilwara Plant for R32: Mou Signed for 120 Cr , but over 200 crores needed including land and Working capital. will produce 410A,404A,454B,513A . Will be operational from mid 2026 . Land is already acquired .
Current operations give around 10% Pat levels . Manufacturing PAT levels would be at 24% . Average we can see 17-18% overall when the plant if fully functional by fy27.
This is the first plant from the company .
Plant will be operational is phases, 5000 tonnes phase 1 , 270 cr turnover possible, 5000 tonnes phase 2 so total 540 cr possible from this plant.
This is for internal consumption all be manufacturing molecules and then blending . Right now molecules are imported and only gelding is done .
100% track record of supplying without disruptions for last 30 yrs in India .
Company moved from 200 bar industry standard to 300 bar which will improve the margins are gas transported will be 50% higher .
Plan of growth :
Plan for adding more manufacturing plants as the plants setup completes .
Fy 29/30 : 2500 cr target , pat for manufacturing will be 24% pat.
First plant will be equity dilution based capex .
Possible that Big oems will be giving amount for capex and amortise it for 10 yrs .
Guided for 35% growth for next few years. Company plans to build bigger plants after the first plant is completed.
Note : This is not a transcript of the full call, please refer to the call for full details.
19 Likes
The company has set an ambitious goal, and I hope they can deliver on it while creating value for all stakeholders.
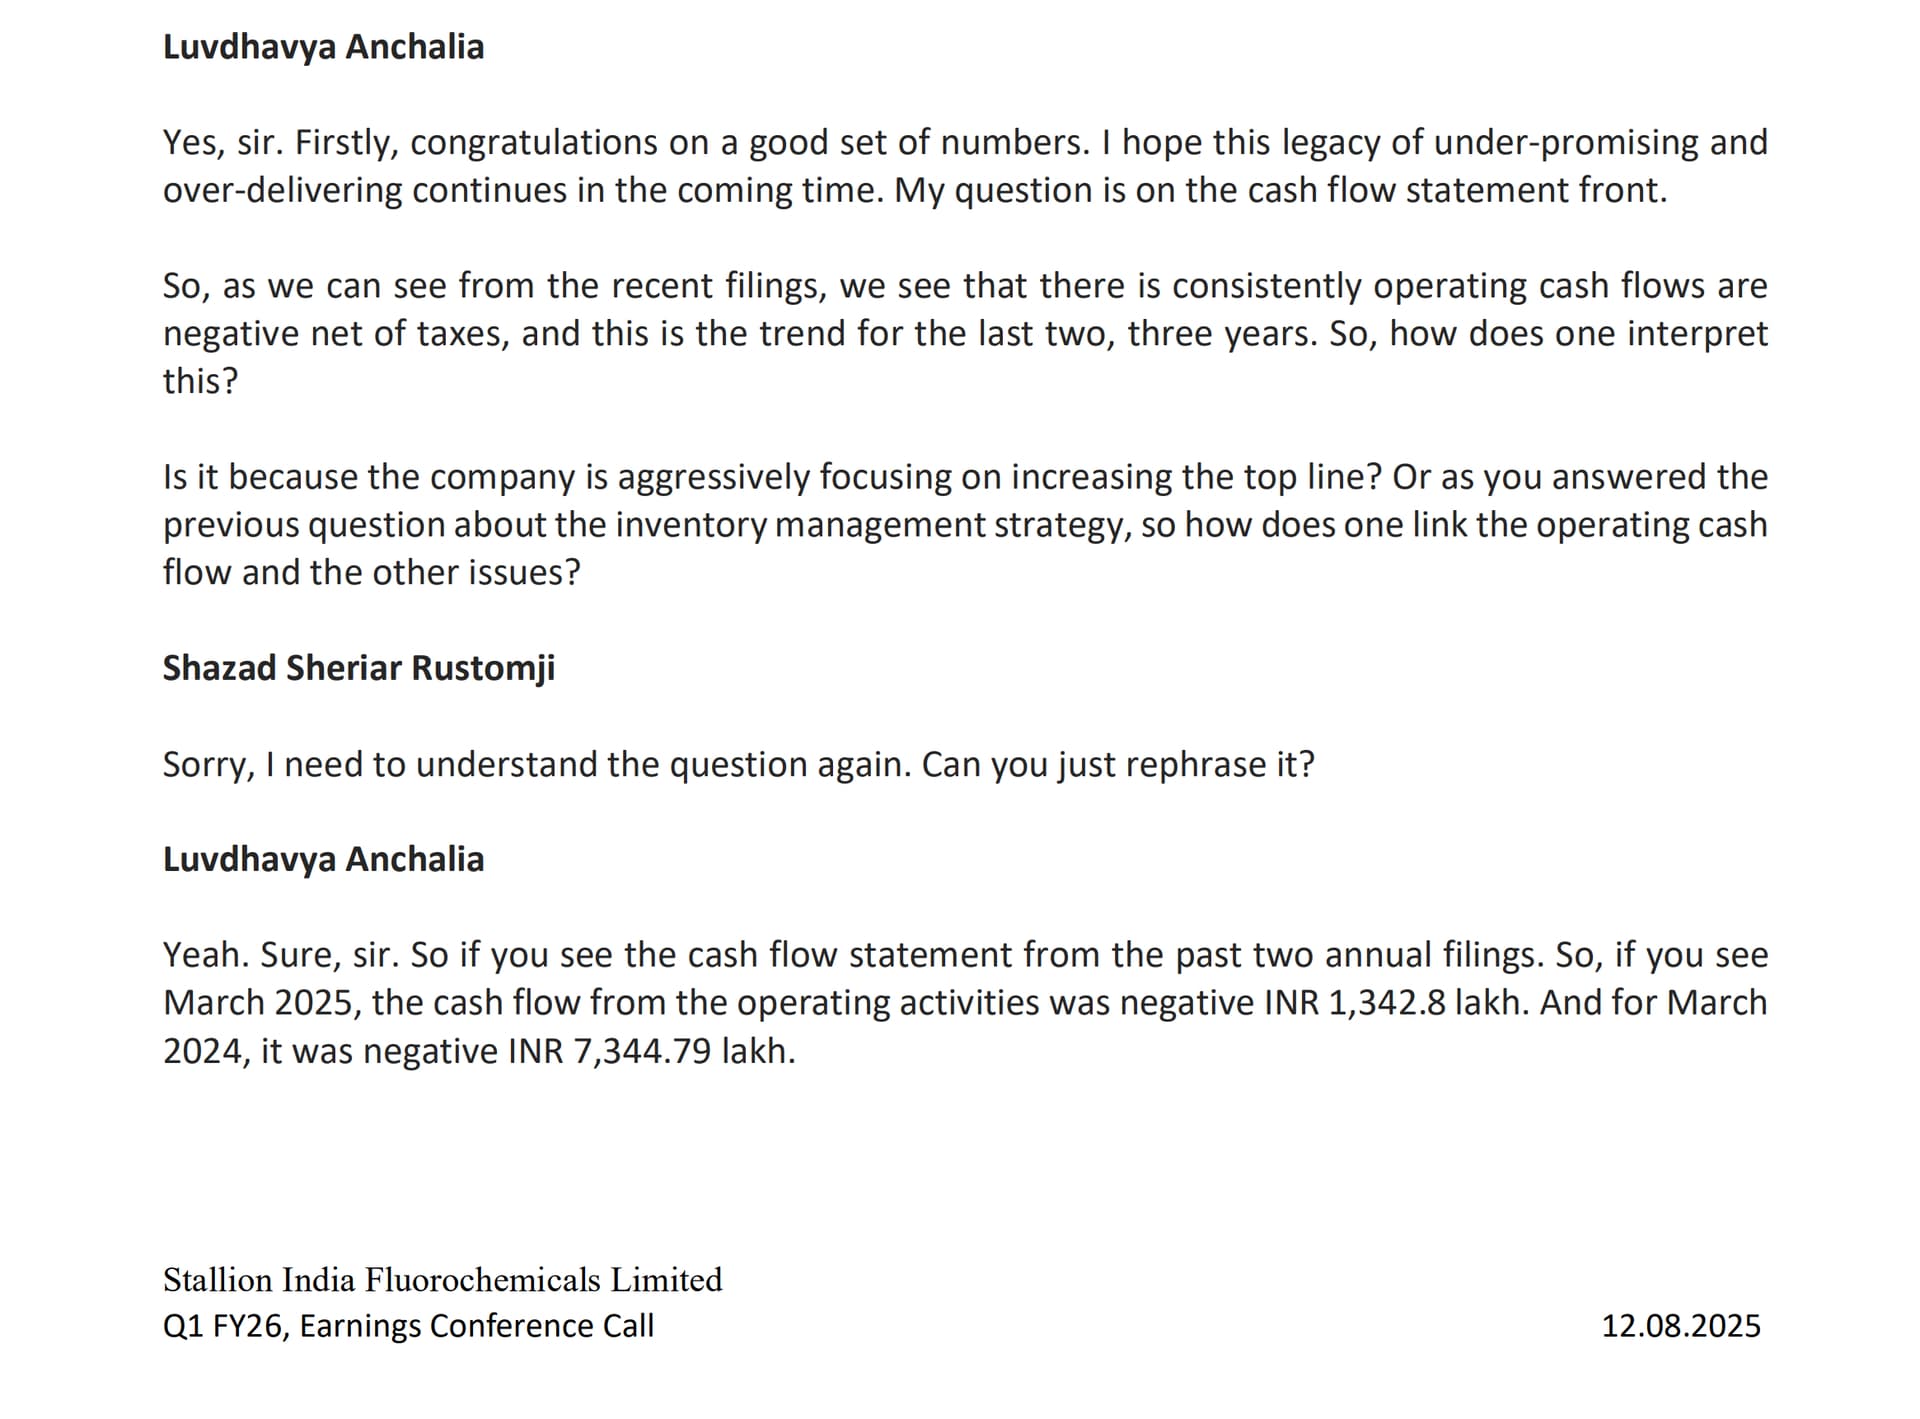
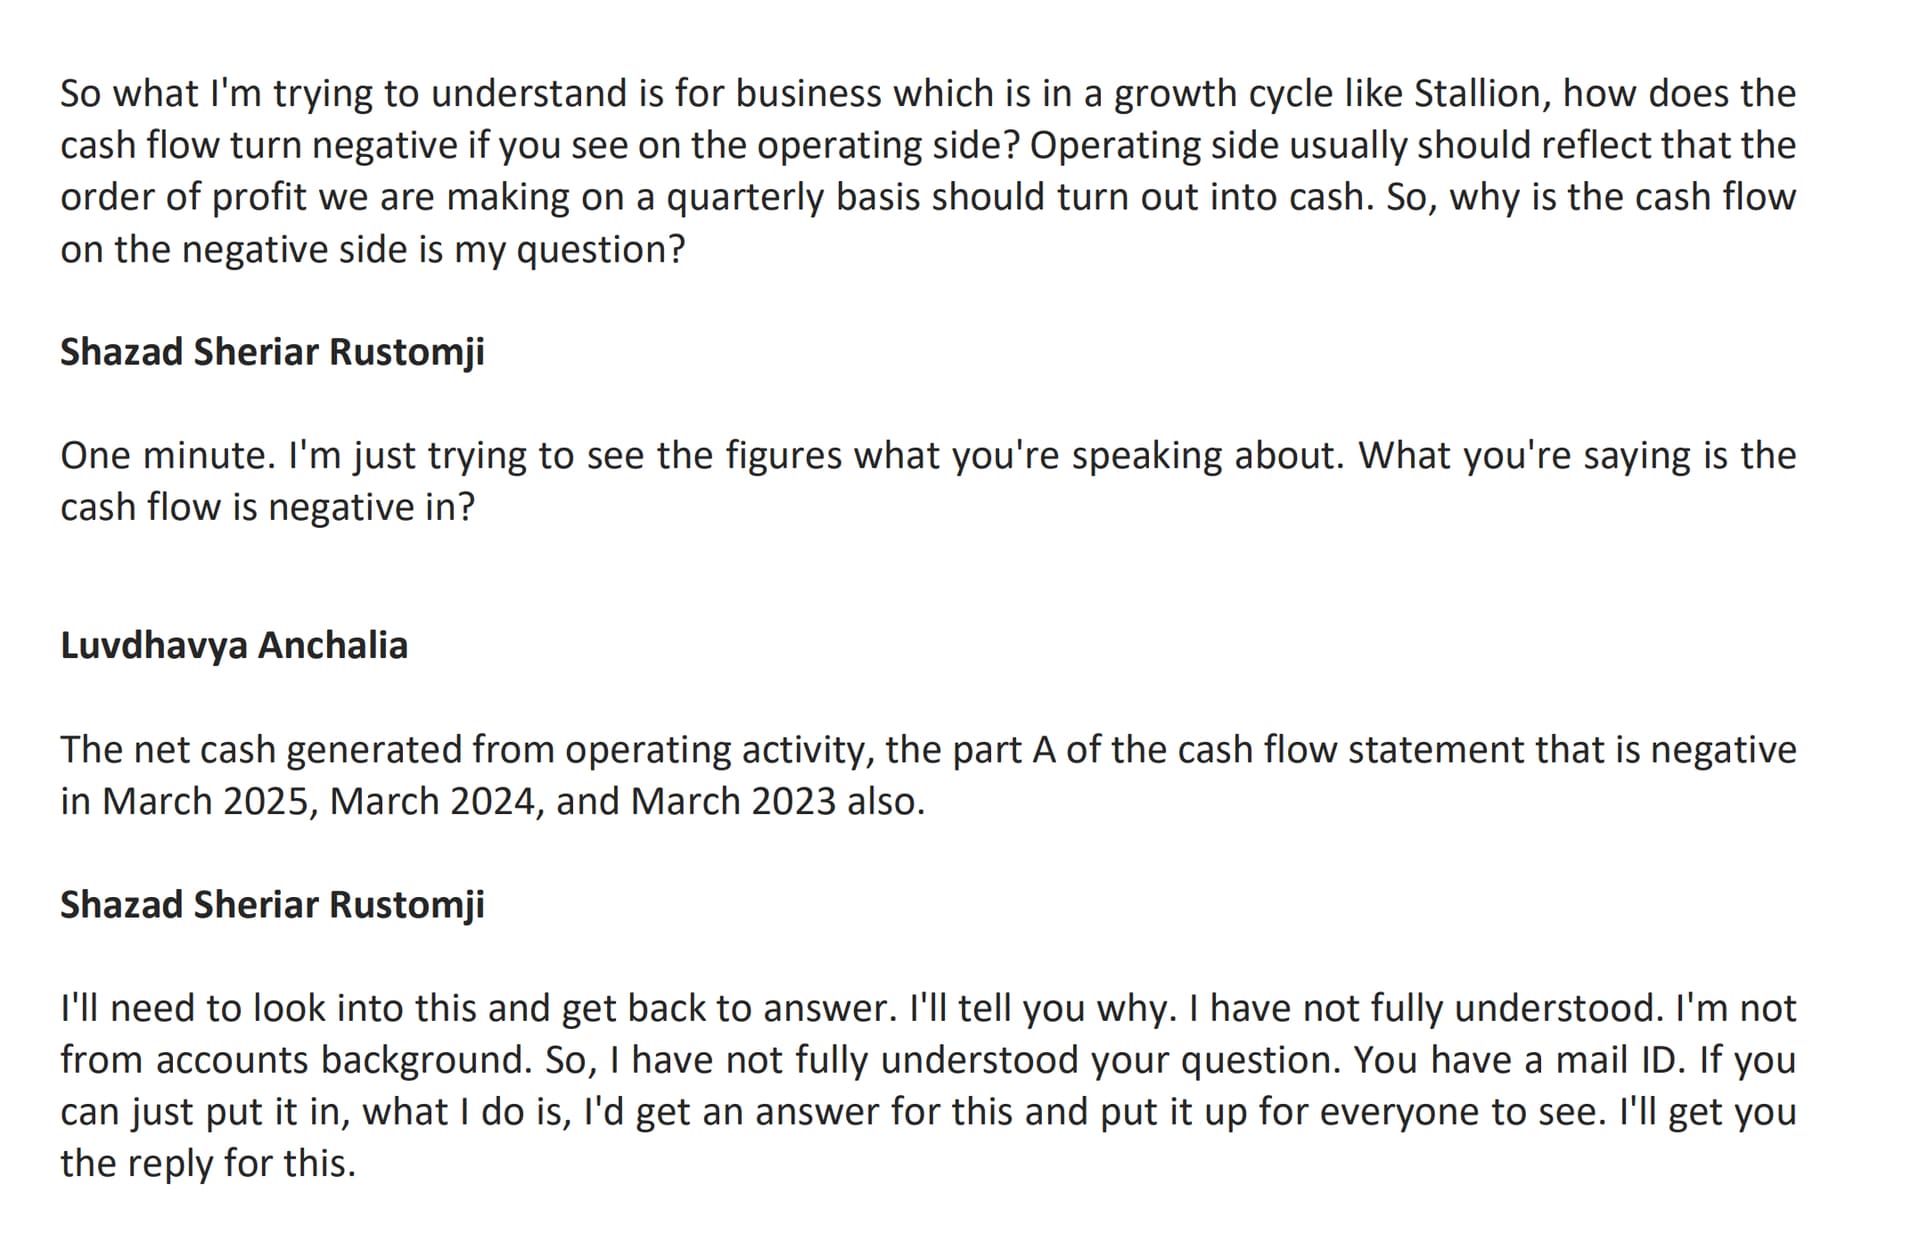
That said, I need some clarity on one point. In the last two conference calls, the CFO was absent. When asked about the negative cash flow over the past three years, the response given was that the matter was “too technical” for him to understand.
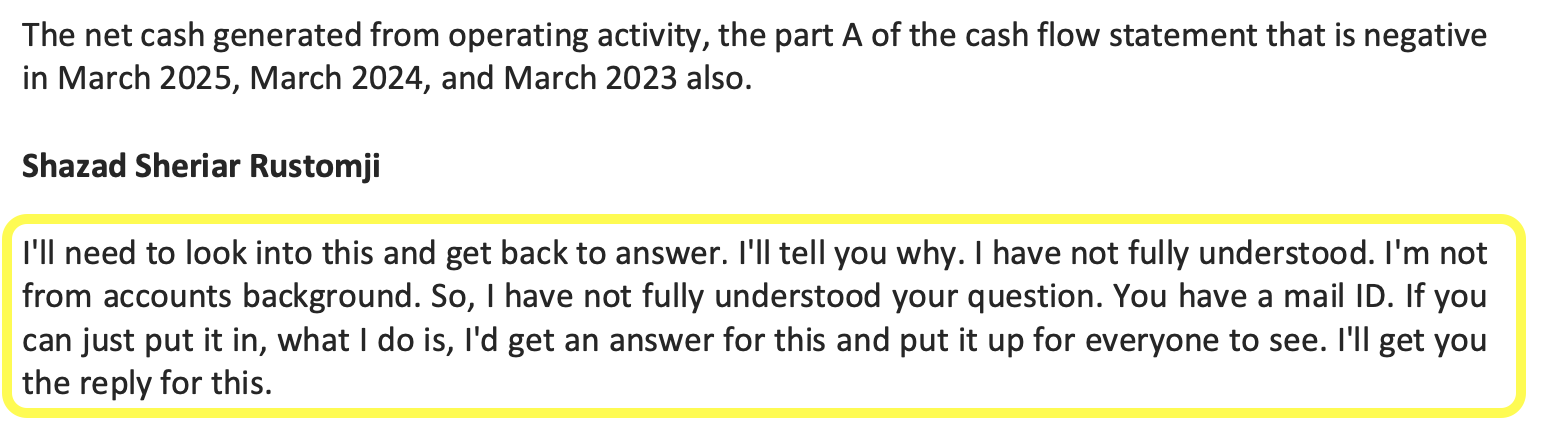
Currently, a significant portion of the company’s funds is tied up in inventory and receivables. In the recent past, they have taken on debt and diluted equity through the IPO. This level of expansion seems risky without a strong CFO in place.
Please let me know if my understanding has any gaps.
3 Likes
I agree to your findings on -ve CF which is mostly due the WC needs, for a high growth business this might be a pattern especially if you Cash conversion cycle is longer , for stallion this is around 6 months. For inventory the management mentioned its intentional to have 100 cr worth of inventory to ensure they are able to navigate the RM fluctuations. Would be good to watch out on this aspect for next 6 months as they progress on scaling up. I am not the best person on accounting deep dives, would be good if anyone else good at this can shed more light.
5 Likes
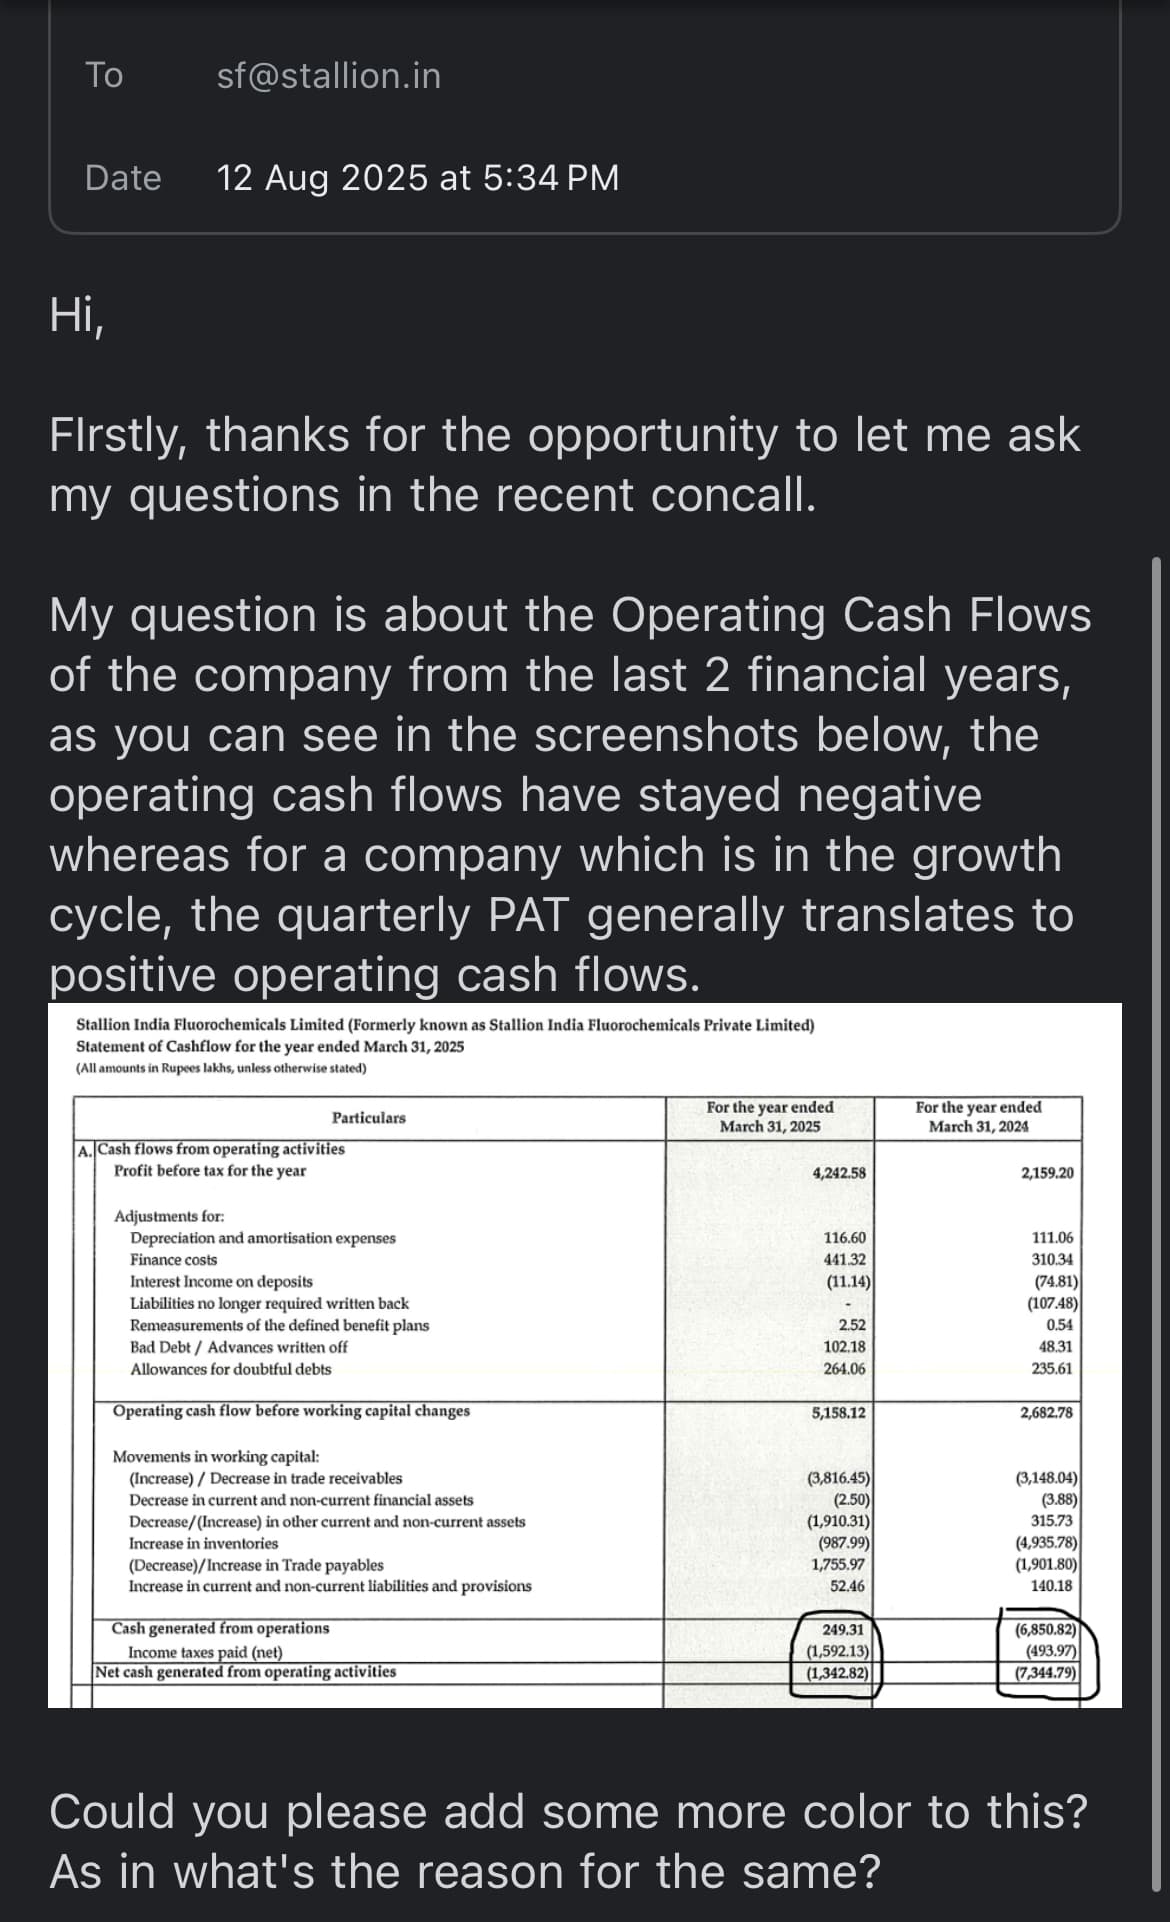
I had asked that question in the call, happened to send them a mail regarding the same too, waiting to hear from them.
10 Likes
I was also surprised to hear the “too technical” comment. Generally founder led company do know finance also. Need to wait and watch how the company evolves. Growth aspirations are very high. Few things like how China dominates supply chain were explained very well.
2 Likes
Hallo. Why are you posting it in this thread?
As regards Stallion, I think negative cash flow is a big negative, unless some legitimate reasons are given. In my opinion, receivables is one of the most important reasons for many companies going from boom to bust. Any start up or SME must keep a close watch on receivables and cash flow. As they are generally short of fund, they must move cautiously. It is easy to fall prey to some grandiose plan, which invariably leads to disasters.
1 Like
Neetu Yoshi Limited : First Con-call post FY25 Earnings
History : Founded by Mr. Himanshu Lohia & Mr. Subodh Lohia holding 68% stake post ipo. Incorporated in 2020 as a scrap trader and now transformed into RDSO Class A certified manufacturer of critical railway components under its life span of 5 yrs. Accredited with ISO 9001:2015, ISO 14001:2015, and ISO 45001:2018. Promoters have no prior family background of business or railways.
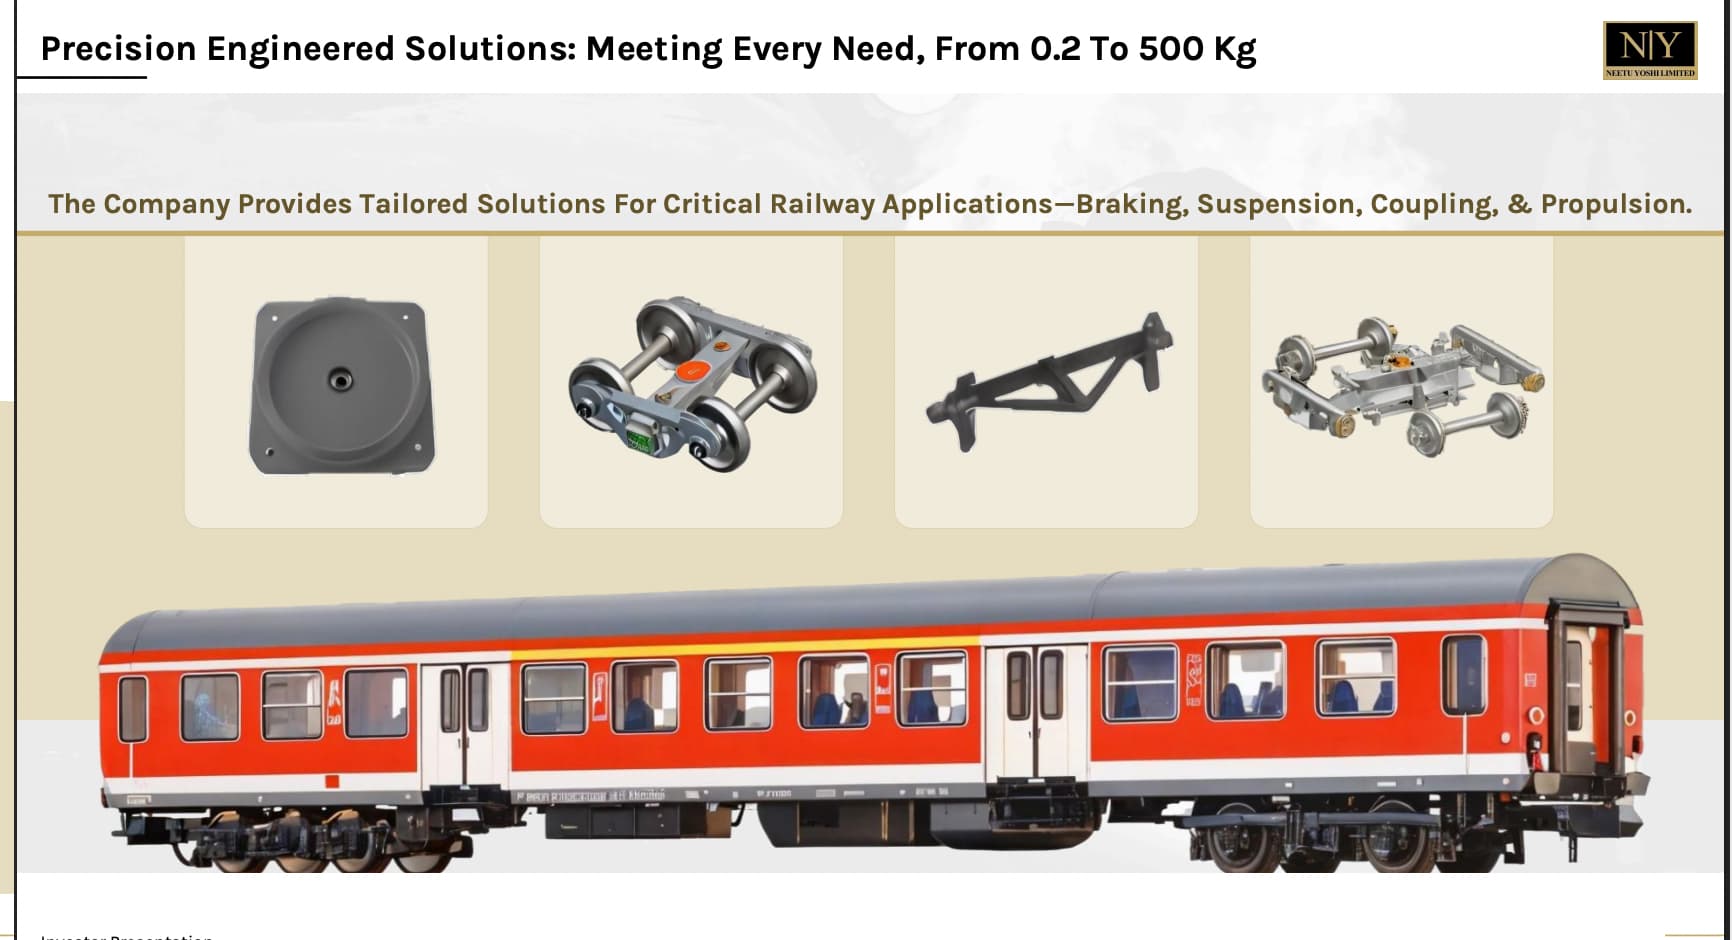
Recent IPO they raised ₹77 Cr, for a new bogie manufacturing plant in Kanpur. Company manufactures 25 essential railway components – including braking system parts, suspension components, propulsion aids, and couplers.
Company has fully equipped foundry integrated with CNC machine shop which enables them to cast the raw metal parts and also machine-finish them in-house to precise specifications without any external dependencies. This helps them in faster turnaround and have better control at quality for the customised orders.
Company is currently debt free with 3 cr. outstanding term loans. customers include Railways directly and private wagon makers like Jupiter wagons, Texmaco. Company has around 100 Employees with 15 engineers. Company procures RM from Railway scrap (high quality alloy) from the Jagadhri Railway Workshop.
Industry prospects:
Currently 2 DFCs are operational and 6 more to come up and this is expected to reduce the goods movement cots to inr 1.5/kg boosting wagons demand significantly. Company prospects depend on railway capex.
Management Guidance :
FY 26 : 120 crores top-line with 25% net profit margins. This is mostly from the existing facilities.
fy 27 : 250 cr. top-line with 150 cr from new bogie plant and 100 cr. from coaches and track products.
Management is confident Margin guidance as they cater to higher value components.
Fy 30 : Full fledged wagon manufacturing.
Order book :
115 cr. and steady inflow of 10 cr. per month. Also they have L1 tenders of 25 cr expected to be converted in OB in 3 months.
Expansion plans :
Kanpur bogie plant : 50 cr. from ipo to be used. Capacity of 500 bogies/month with a revenue potential of 200 cr. annually , expected to have peak revenues by fy 27 end.
Spring plant : 15 cr. capex from internal accruals , by fy27 peak revenues from this would be 35 cr.
Track and Bridges expansion : Current facility is around 7000 sq. mts and additional 3000 sq. mts shed is built next to it with marginal costs of 1 cr. for land conversion, additonal revenues for 30 crore possible from this expansion.
Product info:
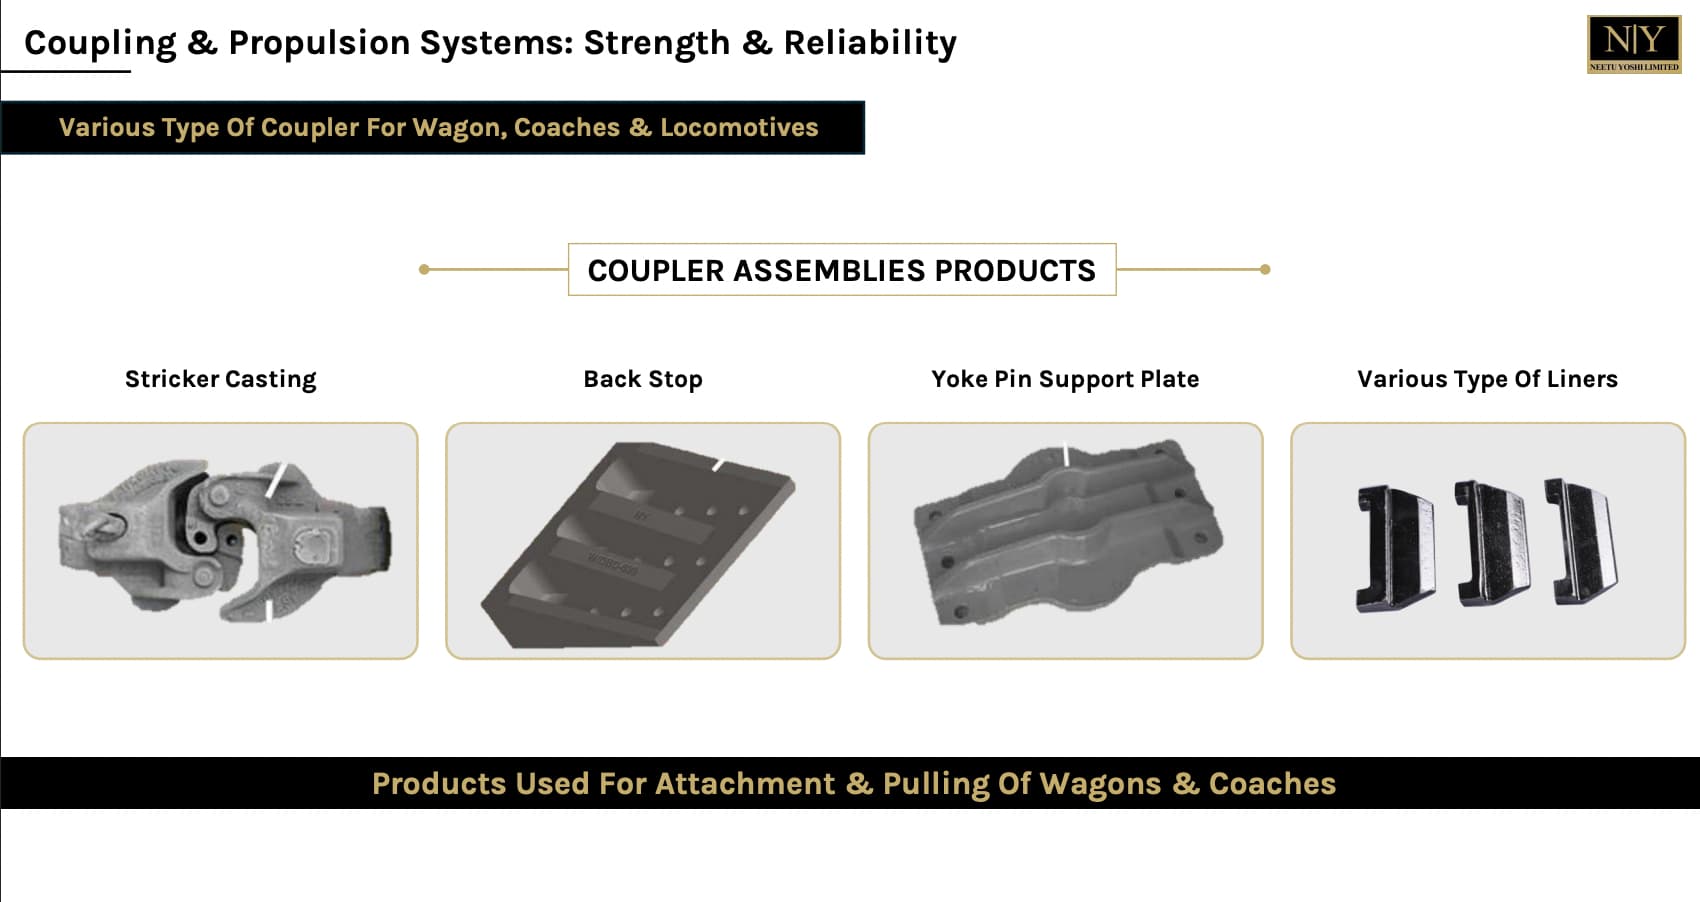
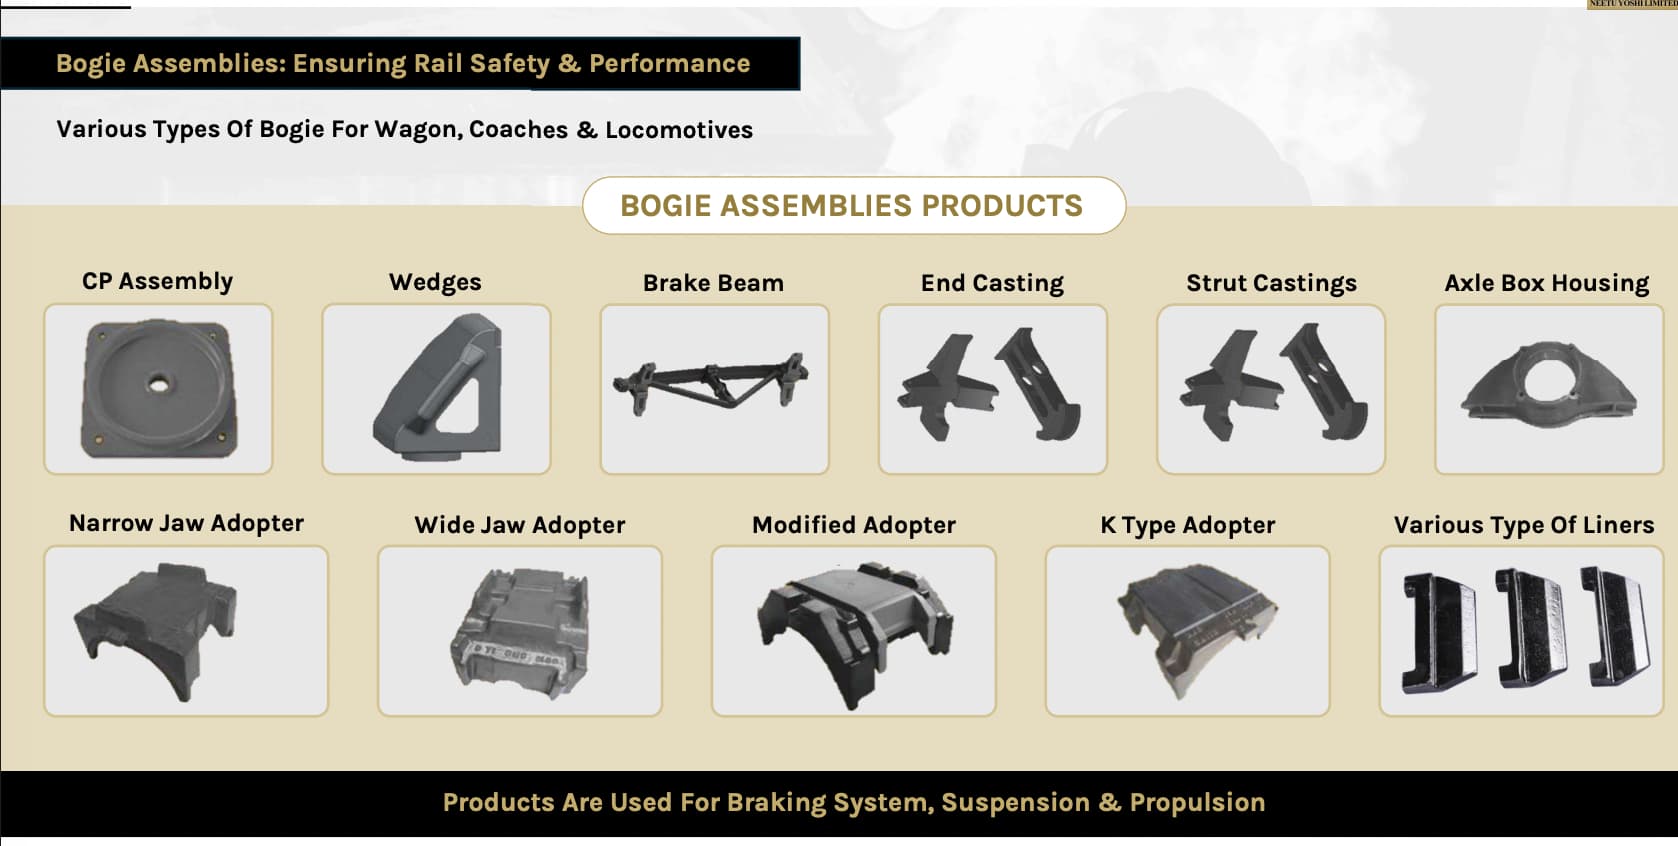
Dscl: Have tracking position. Planning to add more as I understand the Company/business better.
I got interested in this Company due to its aggressive rise from scrap dealer to RDSO class A approved Vendor in no time. And Promoter with no business background was able to ramp up the business. Almost like a rags to Riches story. Wish such Companies continue to perform and surprise us positively.
19 Likes
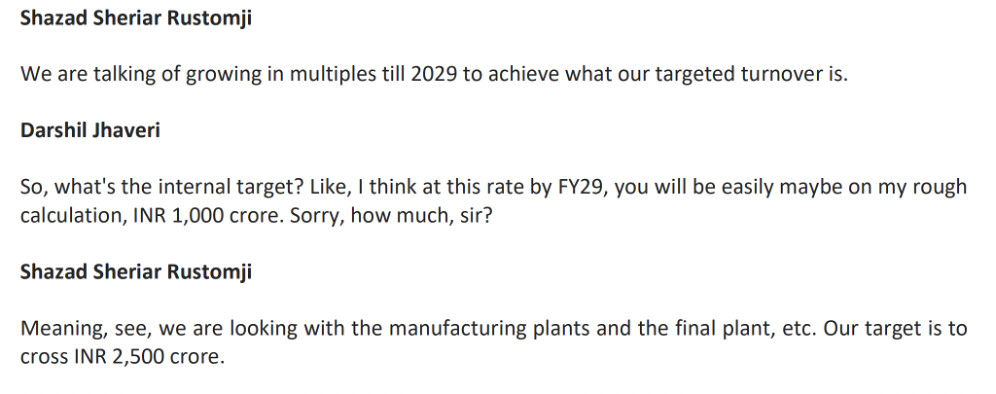
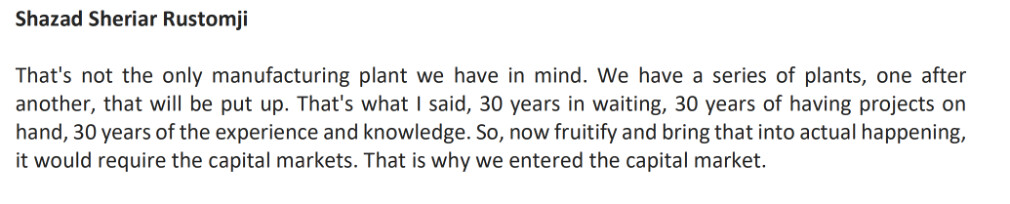
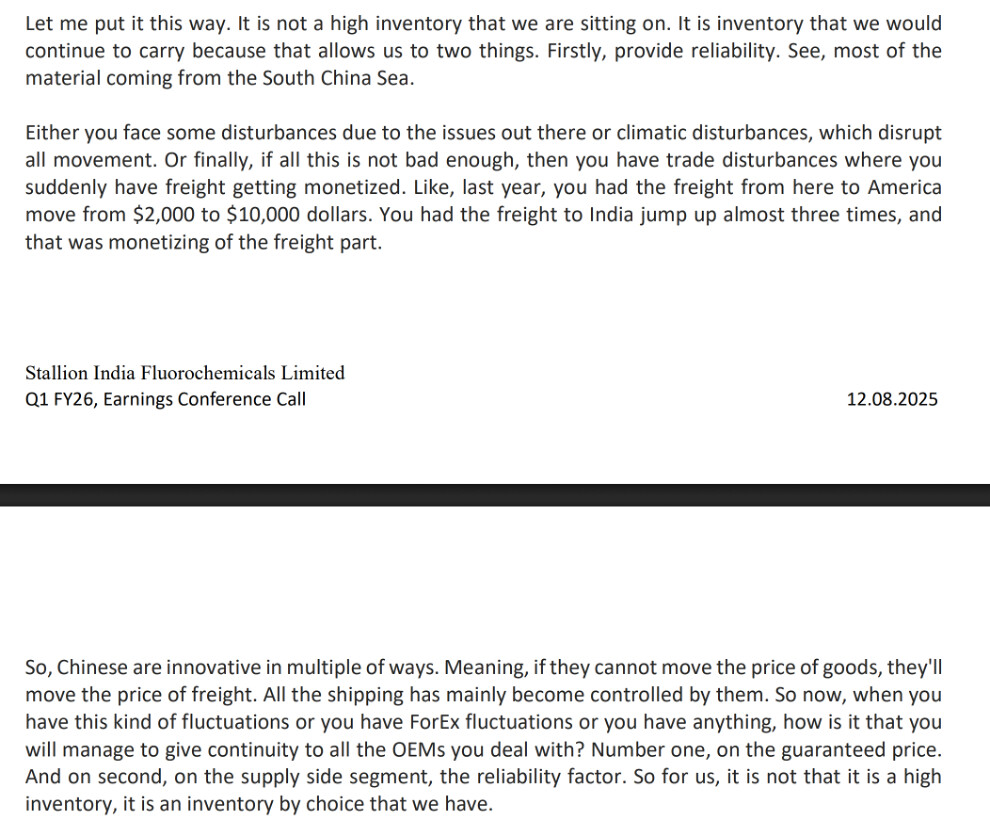
Stallion India Fluorochemicals Limited Q1 FY26, Earnings Conference Call highlights/Snippets
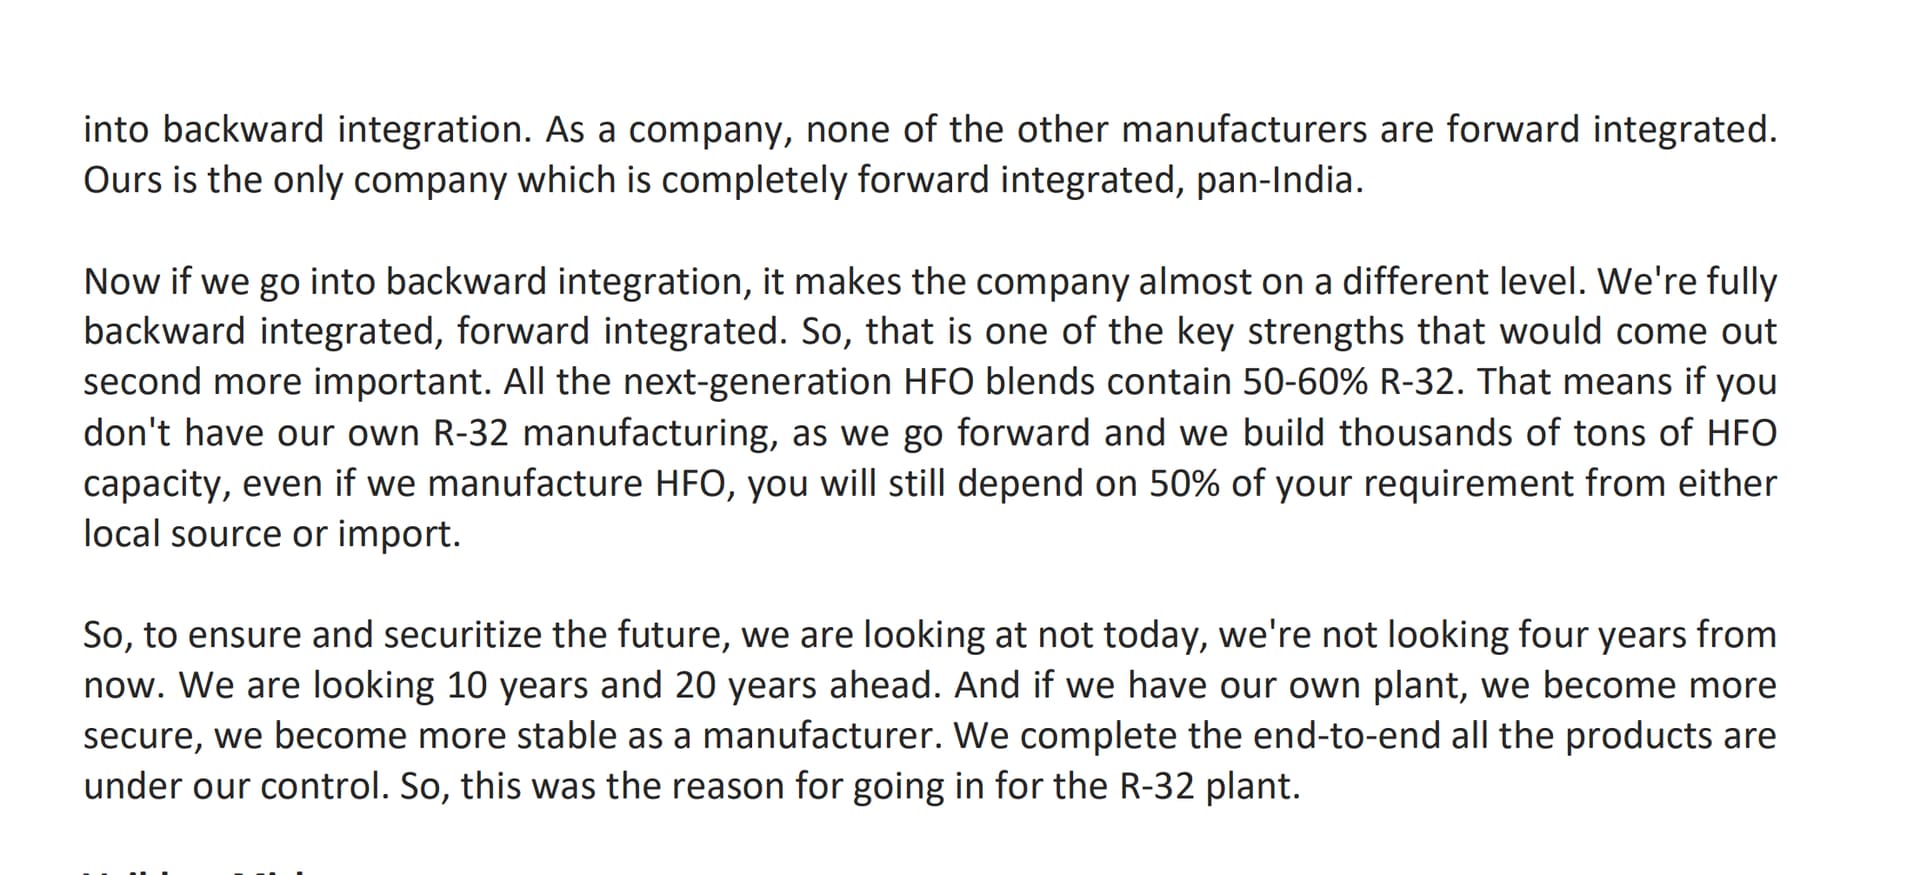
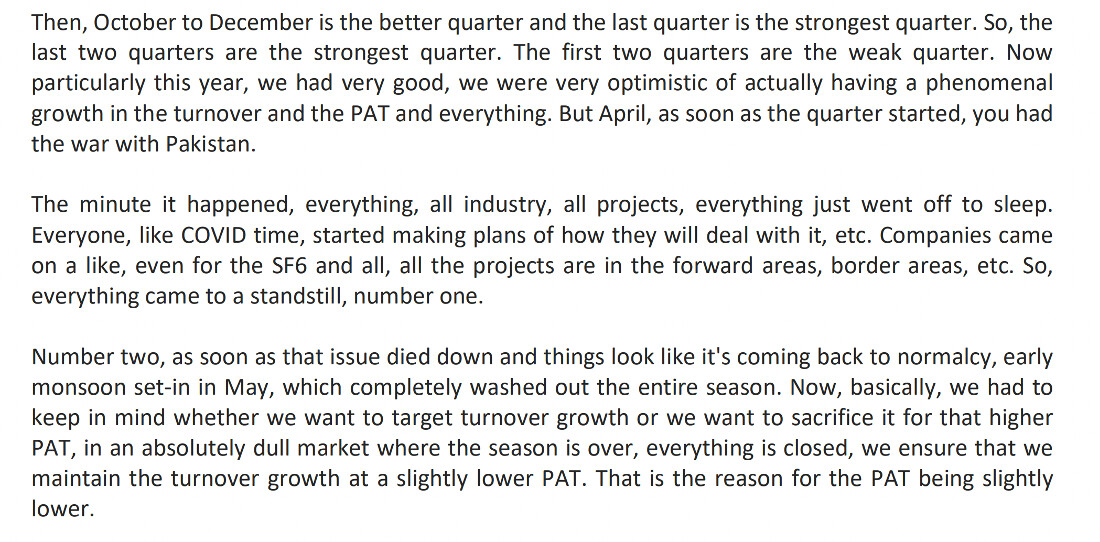
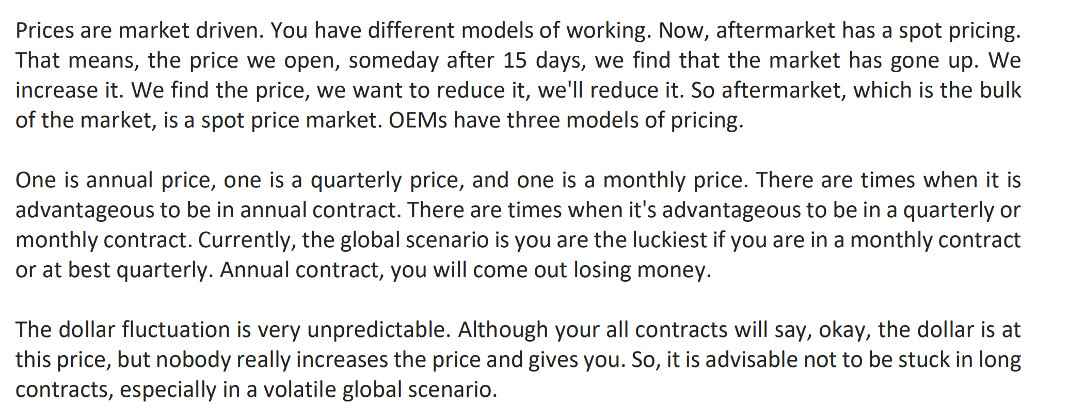
Adding to my earlier concall notes as we have clear transcript to refer to..Below are some key explanations from the MD. I hope everything he says comes true and company can scale higher, Except the part where he said none of us would be around by 2050. 
I Wish everyone a longer and fruitful life!
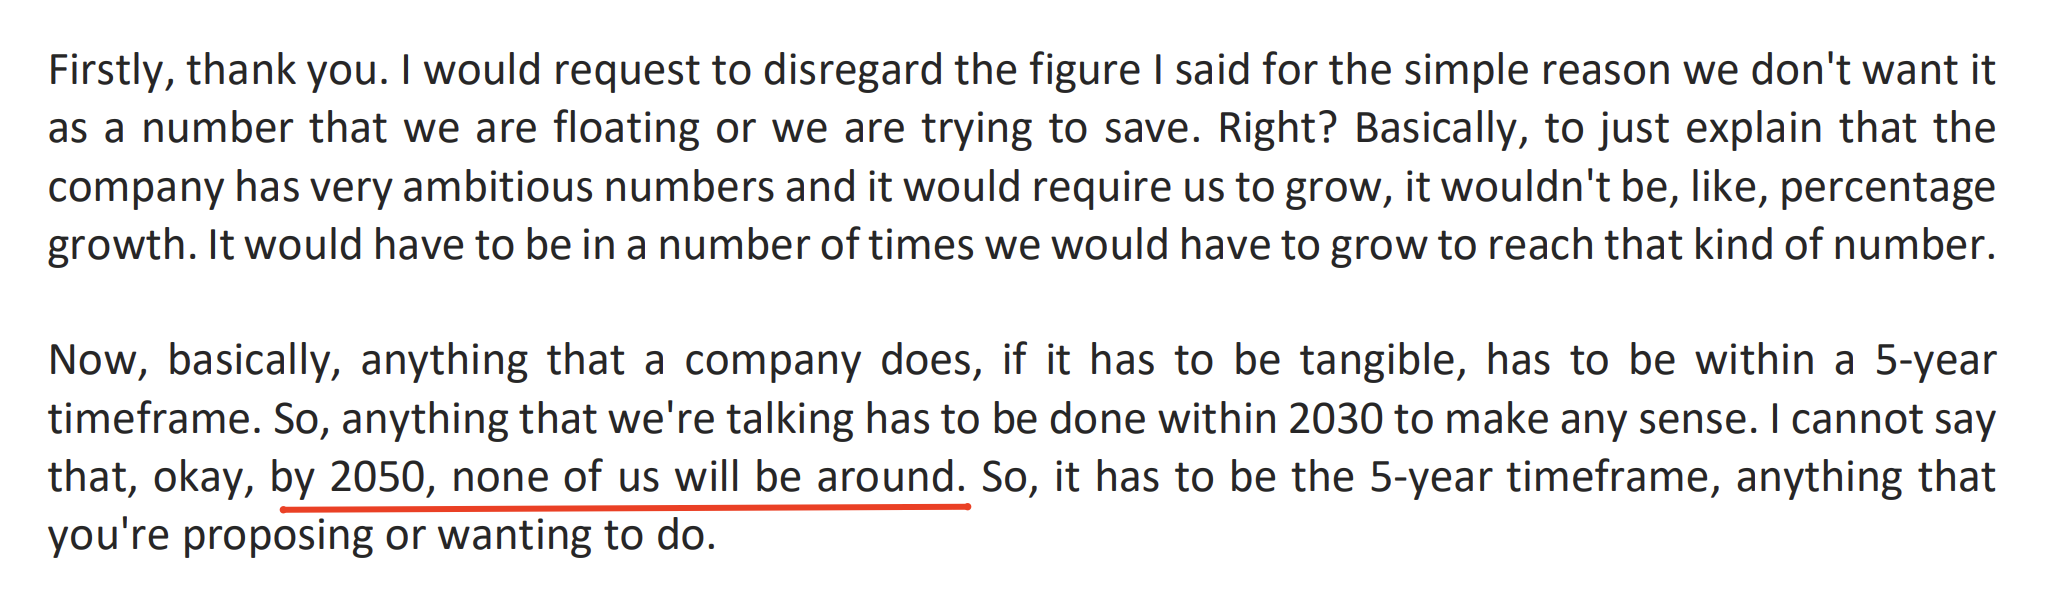
Mr. Shazad Sheriar Rustomji - Managing Director and CEO
On why new plant is being setup ,
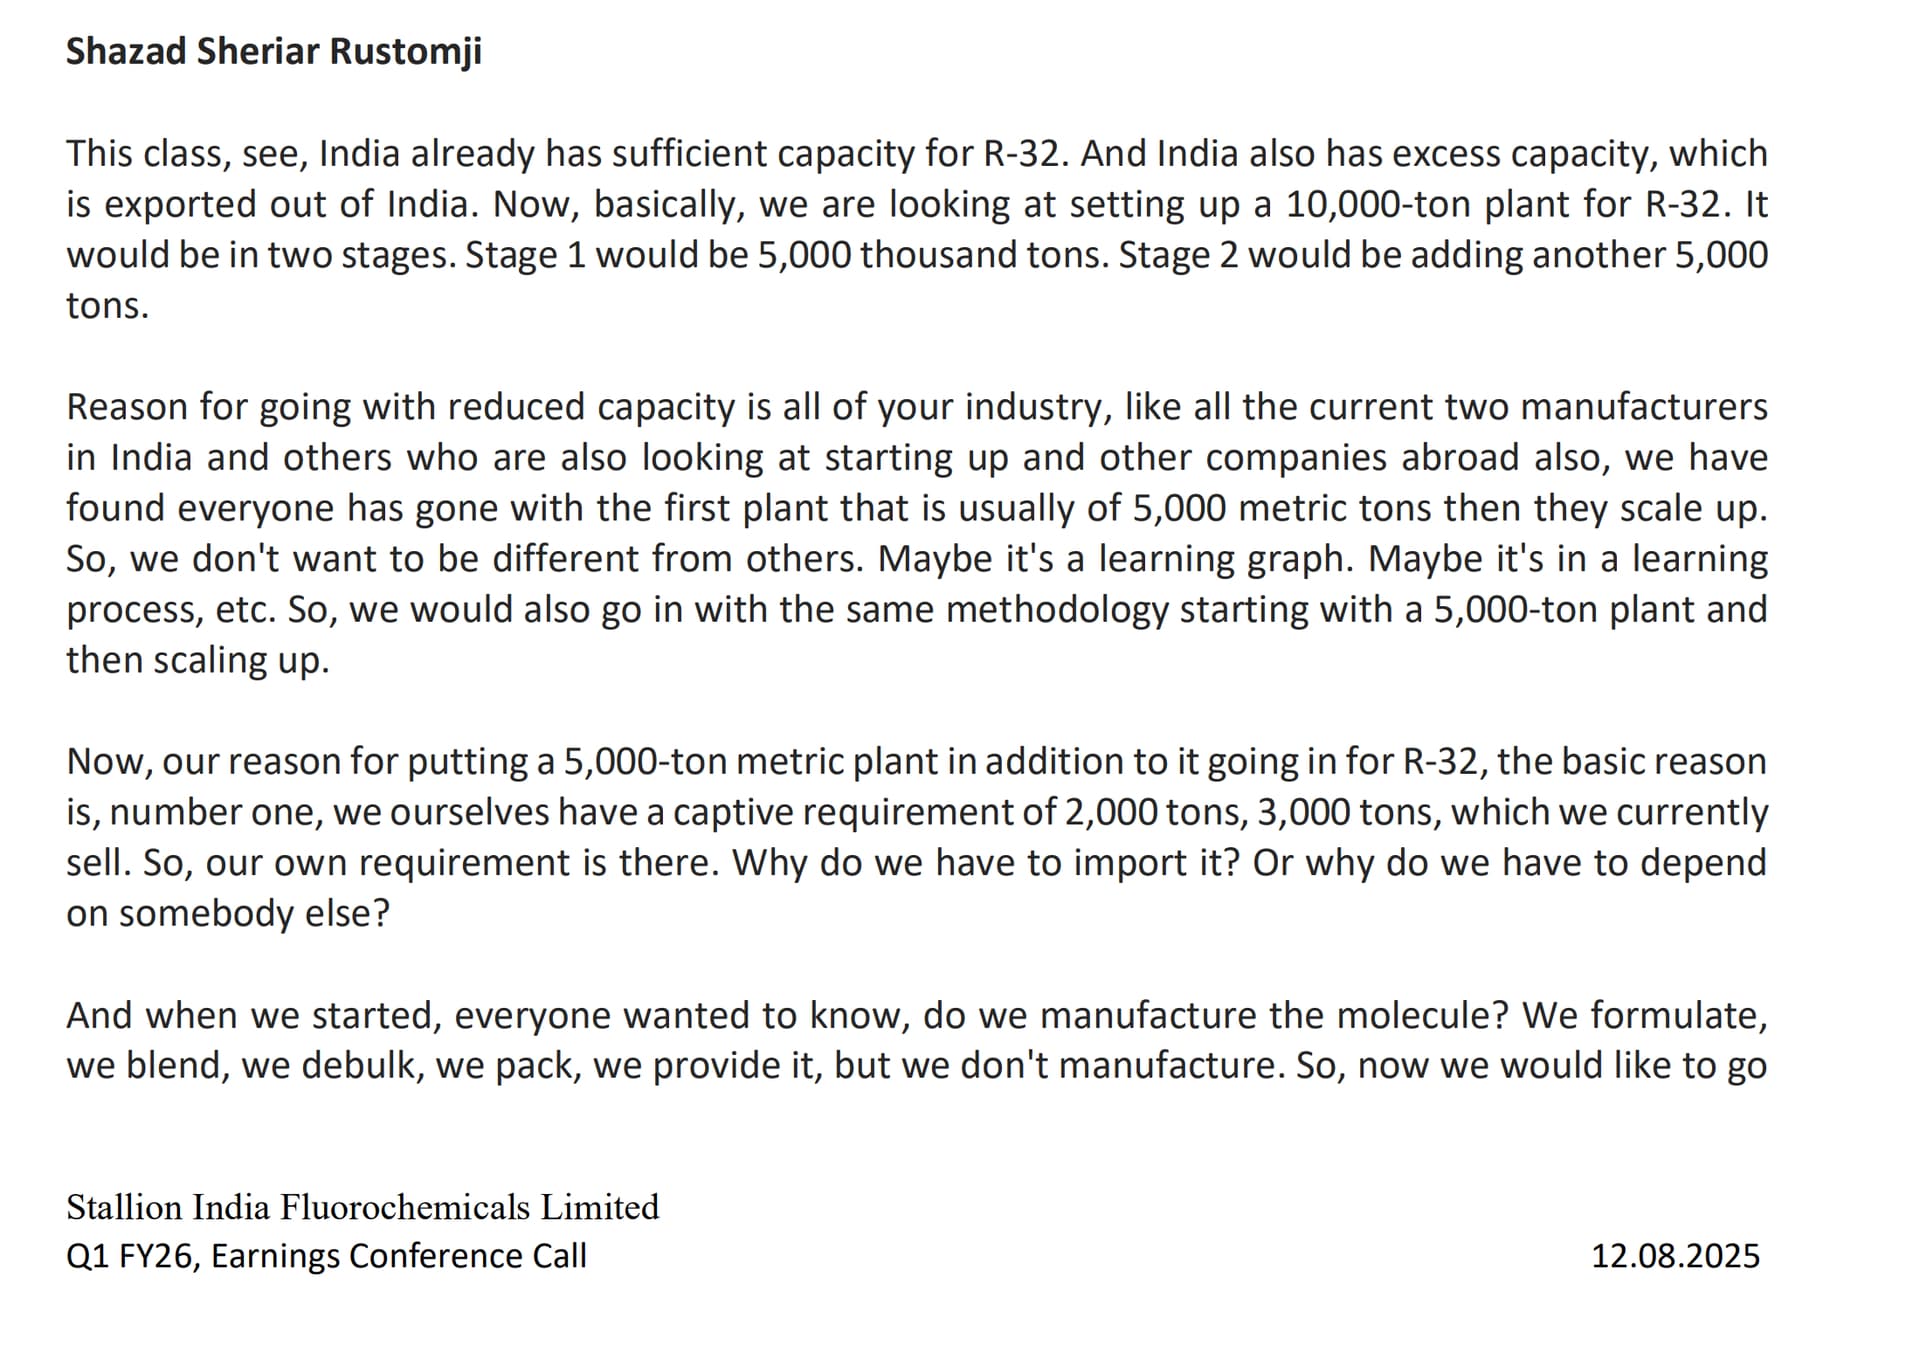
On lower Pat Margins for q1,
On product pricing,
30 years planning before the manufacturing was taken up,
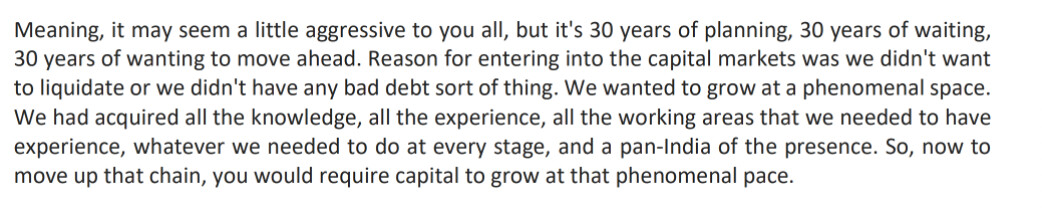
Long term internal target,
On higher inventory as a strategy,
Cashflows not explained clearly, need to see what is the management response on this.
@luvdhavya Let us know here when ever you get a response from the management.
Key Triggers:
1. * 6 facilities operational by end-2025; pan-India coverage to cut logistics cost & improve delivery cycles.
2. * ₹200+ Cr Bhilwara R32 plant (10,000 MT) – Phase 1 start mid-2026; backward integration to reduce imports & serve exports.
3. * Khalapur expansion (Liquid Helium & Specialty Gases, 1,200 MTPA, 300 bar) – Nov 2025 operational.
4. * Mambattu AP facility expansion (7,200 MTPA, 5 sheds) – Nov 2025 operational.
5. * EBITDA margin up from 11.37% to 13.11%; PAT margin target 17–18% in 3 years.
6. * Management guides for 30–35% CAGR revenue growth; turnover target ₹2,500 Cr by 2030.
10 Likes
Neetu Yoshi:
Is it already RDSO certified ? Or is it going to be certified in March 2026 ? Also, whats your take on their dependency of 54% sales to a single client ?
1 Like
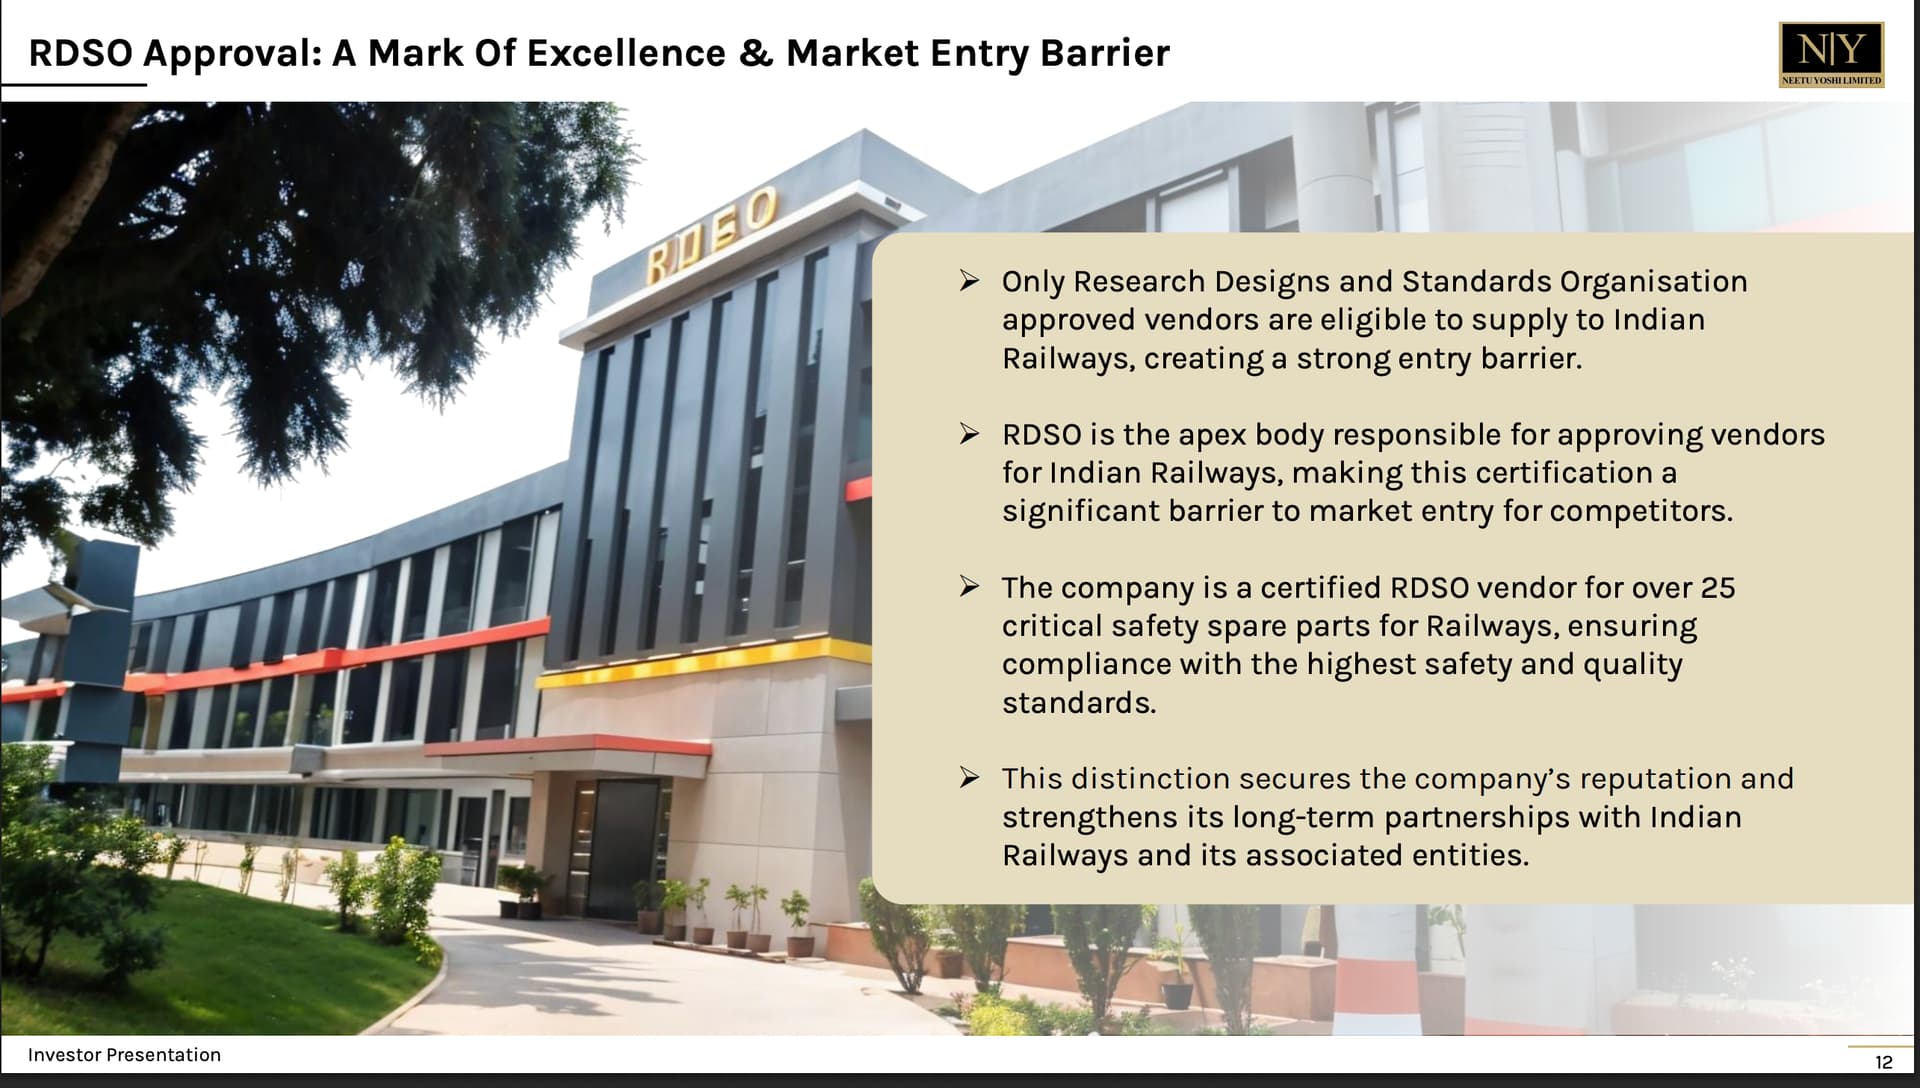
Unfortunately this question didnt come up in the call on customer concentration risk. Have asked the CS same and waiting for their reply.
8 Likes
Neetu Yoshi:
The things that caught my eye are the following:-
- Average age of promoters is 28-29 years.
- The education profile is average.
- How they got approvals in such a short span of time and delivered huge orders (47 Cr in 24 and 70 Cr in 25). Note the Bhagwanpur plant was started in 23-24.
- Why promoters have so many companies with significant influence?
- What is the right to win for the company for the revenue projections?
- Source of capital for initial setup of manufacturing plant?
- Also in RPT, some transactions are skeptical:-
a. Professional fees of 34 lacs
b. Facility service charges of 51 lacs
c. Advance hire charges of 30 lacs
All these charges are provided to promoters/ companies having significant promoter influence.
Dis. - studying not invested
8 Likes
Stallion :
The reply from Shazad sir was baffling to be honest. Being in managing a company for 30 years and one has no idea about 'what is CFO? ’ is ridiculous to me. Either there business model is/was too good to look or understand what the CFO/FCF the business is/was generating or it was luck till now.
Dis. - Studying and not invested.
3 Likes
Stallion :
I too found the response to the query on CFO very surprising. How come a founder manager does not know/understand cash flow. Also his commentary on the growth was way too bullish. Remembered Warren Buffet’s (or Charlie Munger’s) words, “if something sounds too good to be true, its very likely to be the case”.
3 Likes
@Satishwe Multiple companies are discussed in the same thread. The comment posted for which company is very difficult to link to. Could you please do something about it? Thanks.
When ever I reply, I usually mention the stock name. Suggest everyone to do the same and avoid confusion.
4 Likes
Hi Satish,
what your view on Sudarshan Pharma?
Fundamentally I see strong, but would be great to hear your views
Hi Arjeet,
Not tracking Sudarshan pharma as of now.