I would like to throw some light on construction linked payment plan. I have visited a lot of under-construction residential project in Pune. Maharashtra has something called MahaRERA to regulate RE projects so same applies to Mumbai as well. Below is an actual construction linked payment plan of one of the project I visited (total 25 floor building):
Schedule of Payment
%
Booking Amt
10%
After the Execution of Agreement
15%
Completion of Plinth
20%
Completion of 1st Slab
2%
Completion of 3rd Slab
2%
Completion of 5th Slab
2%
Completion of 7th Slab
2%
Completion of 9th Slab
2%
Completion of 11th Slab
2%
Completion of 13th Slab
2%
Completion of 15th Slab
2%
Completion of 17th Slab
2%
Completion of 19th Slab
2%
Completion of 21st Slab
2%
Completion of 23rd Slab
2%
Completion of 25th Slab
1%
On completion of the walls, internal plaster, floorings, doors and windows of the said Apartment
5%
On completion of Sanitary fittings, Staircases, lift, wells, Lobbies up to the floor level of the said Apartment
5%
On completion of external plumbing and external plaster, elevation terraces with waterproofing
5%
Completion of lifts, electrical Fittings & Lobby
10%
Possession
5%
Total
100%
If one notice carefully almost all such plans have ~50% cash collected at plinth level (above plan is generous as it asks 45% which is rare). Lets say you are the first person to book a flat and that tower construction has not started. You will pay 10% booking amount and more after the agreement is done. This is before the builder is yet to dig the ground. To reach the plinth level it takes 6 months or maybe few more months in some cases. Overall completion and handover takes 3-4 years if there are no delays. So essentially you are paying almost 50% of the total cost just at the plinth level which is <15% of the work. Building the slabs is quick after that but the internal work like plastering, flooring, electricals, plumbing etc are most time consuming. Such plans are designed to fund land acquisition costs, marketing and initial construction costs.
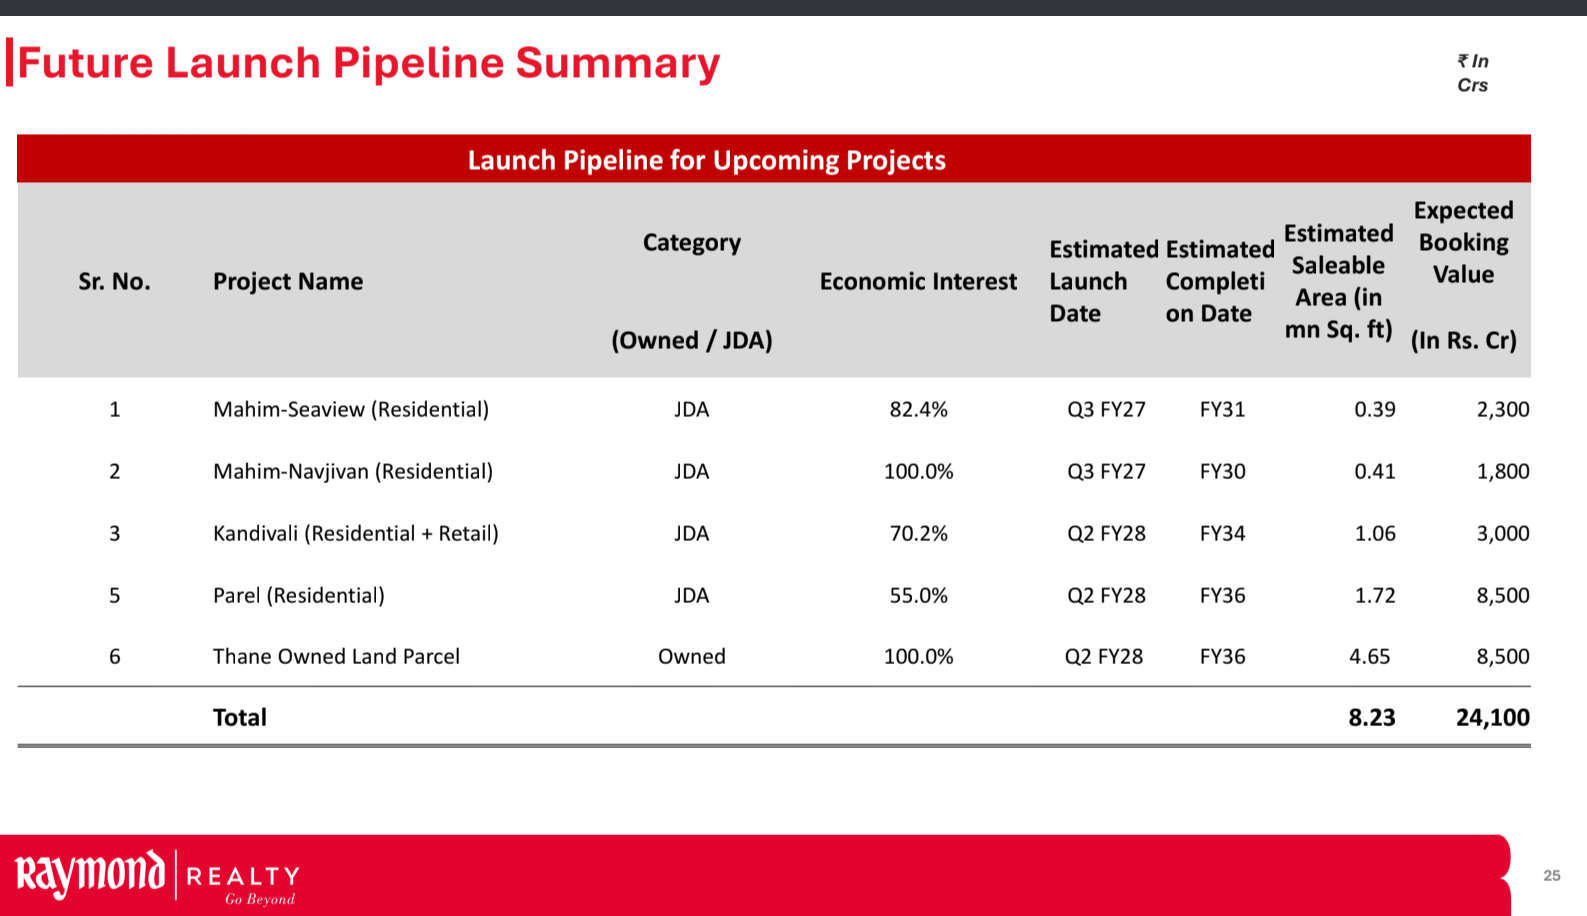
But asset light JDA undertaken by RR requires no funds for land acquisition. This can be very beneficial if projects are executed correctly while maintaining healthy balance sheet. You sacrifice some margin for lower initial cost but you get fewer blowups as land acquisition is biggest headache for anyone.
Considering season in Mumbai, Pre-sales and collections momentum is quite healthy.
I think momentum will continue, since last 12-18months company has built supply.
Concall commentary and out look for the remaining part of the FY was positive.
Collections should pickup as it gets close to close of the year since 2-3 new projects that were launched are in a good stage.
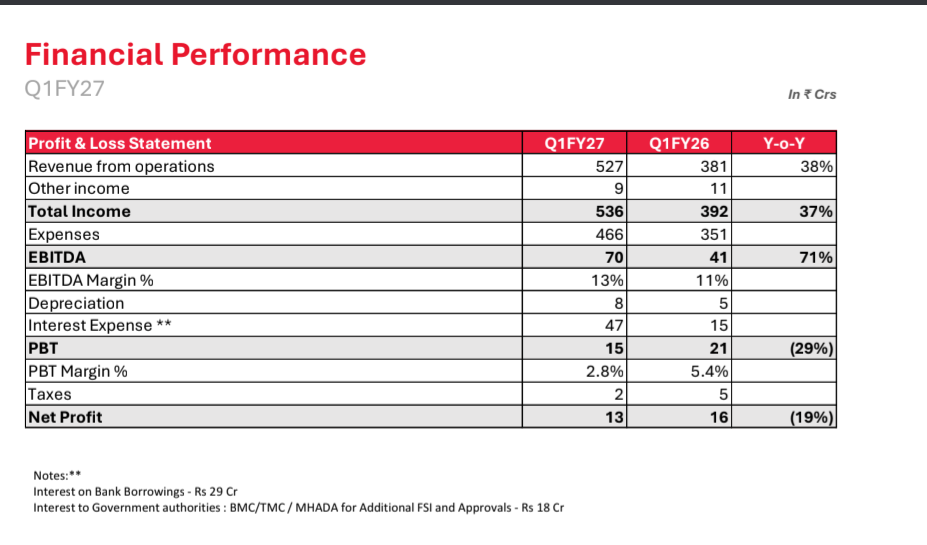
Someone raised good question on interest cost in Q127 not matching the proportion of Gross Debt and Rate of interest, and asked for clarification on the composition of the cost (though they have some disclosure in the AR-2026, it was never disclosed in any of the earnings call or presentations), the management was caught off-guard and agreed to disclose that outstanding amount that company owes it to govt bodies for Development fees/statutory fees.
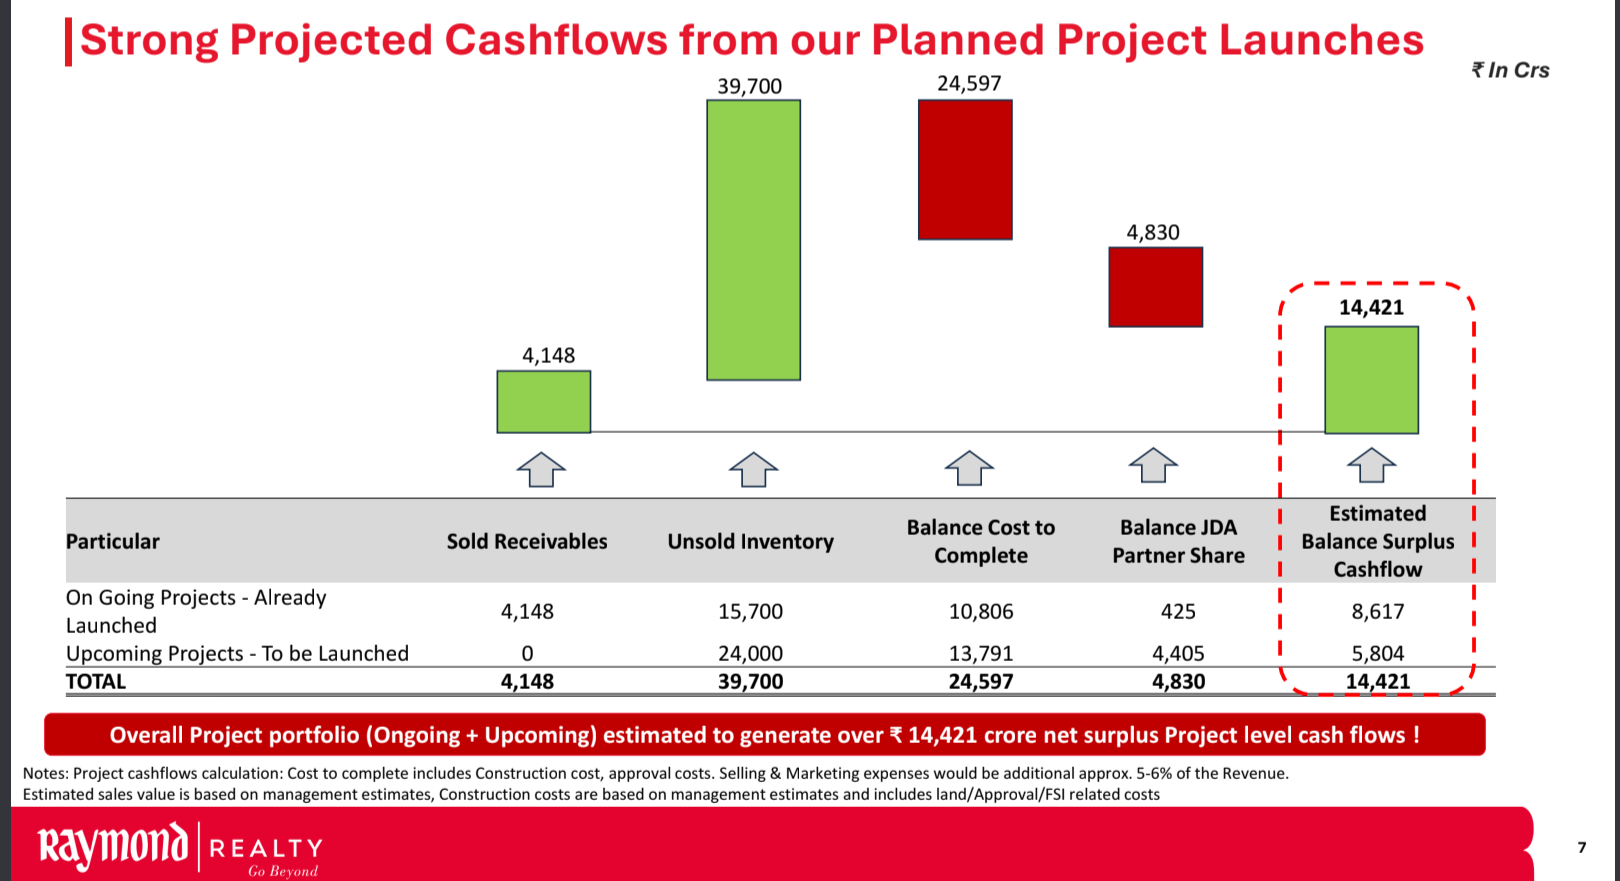
Estimated surplus cashflow slide is now updated, total surplus now at at more than 14000 crores. There will be selling and advertising costs of 5-6% revenue from this. So, maybe another 2000 crores would go in S&A (5% of unsold inventory of ~40k crores).
Also the repeatedly asked question on concall regarding interest cost bifurcation, that has been disclosed out of 47 crores interest expense in Q1, 29 is interest on bank deposits and 18 crores is interest on dues to govt. bodies for approval costs etc.
Has anyone established reason for the fall in raymond realty? I get the negative news on real estate (sales slowdown) but this is any way undervalued to begin with. I get spooked when such sustained fall happens after delivering good results.
Maybe it is because of weak markets or people who bought on MTF selling.
Mostly its retail ownership who don’t understand realty sector well. Hoping for some FII/DII entry as these are very attractive valuations.
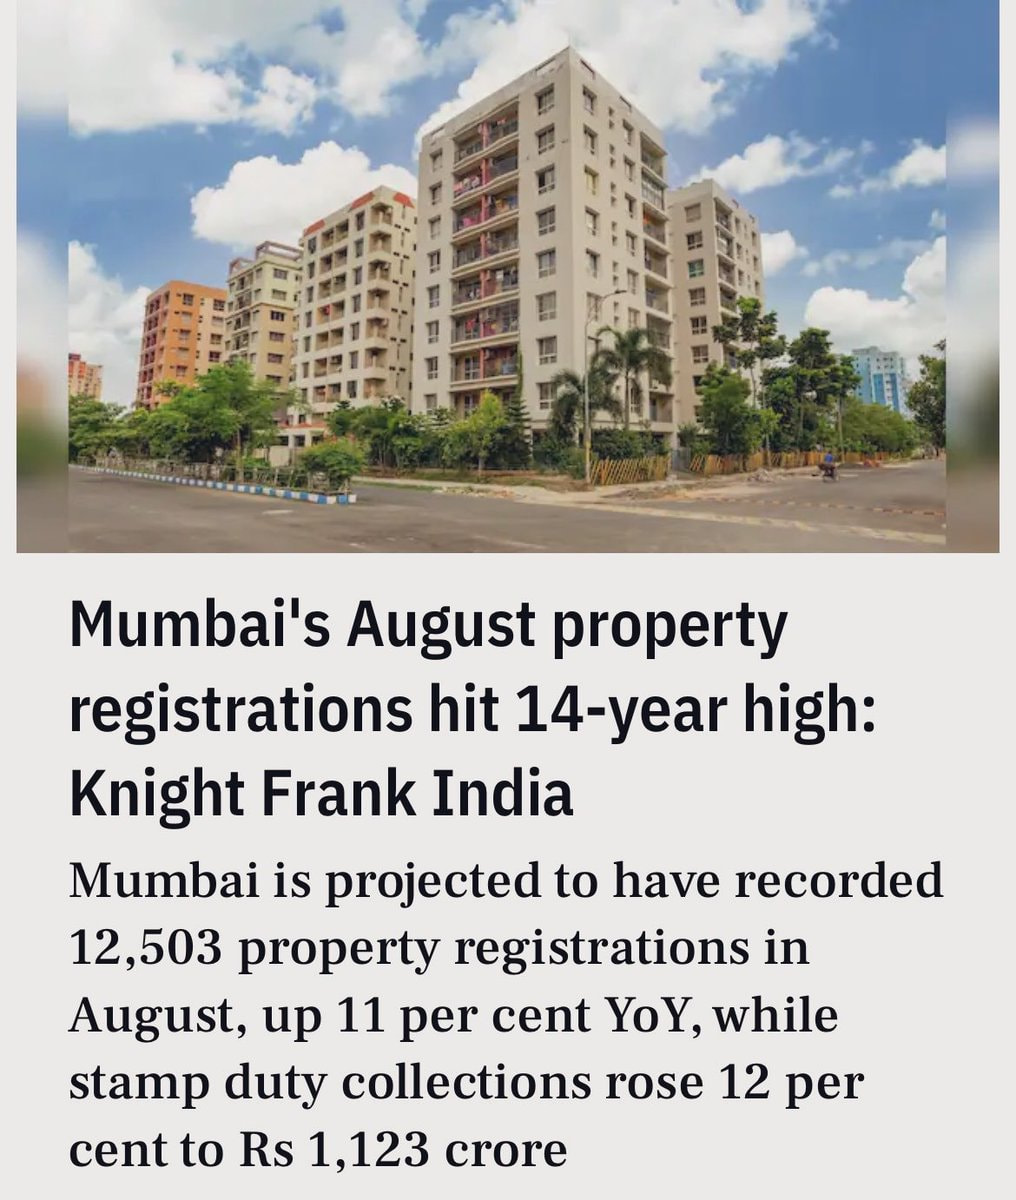
As far as news and sentiments are concerned August sales look healthy and Raymond realty looks on track to deliver good results in FY 27.
Mumbai real estate market looks pretty stable to me.
Also recently company had one one one investor meets with
ICICI securities, Jefferies India, Motilal Oswal and other institutions.
Things are looking Good found no reason to panic probably this happens with retail heavy stocks.
I think property registration is not a very good measure to gauge the situation of the real estate cycle.
Reason is very simple property registrations are happening because sales took place long ago.
Pre sales is much better metric to understand what’s happening in the sector. If pre sales stops increasing or start decreasing after considering seasonal and festivals dips and spikes then it’s a worrisome situation.
There’s some impact of launches on pre sales also. People say if yoy prices are increasing that means things are going good in the sector.
It’s very difficult to understand when real estate cycle will peak and what’s the current situation of the cycle.
When we clearly comes to know that cycle is bust I think by then there would have significant price decline in real estate companies’s shares.
So right now I am not much interested in cyclical mumbo jumbo because for me it’s very difficult to understand and that might not be the case with you.
Accounting Lag: P&L reflects business done 3–4 years ago due to project completion (handover) accounting.
Distorted Screening: Screener P/E and EBITDA margins are misleading. Interest capitalisation and customer advances can make healthy balance sheets look risky.
Economic PAT over Reported PAT: Evaluating stocks using Current Pre-Sales × Embedded Net Margins reveals developers growing pre-sales at 25%+ trading at single-digit multiples.
In the Mumbai Metropolitan Region (MMR), the primary property registration for an under-construction home happens at the time of pre-sales (booking), not at delivery.