“when the state is your client, your regulator, and your tender-master, the moat is a permission — and permissions get withdrawn." - AI generated
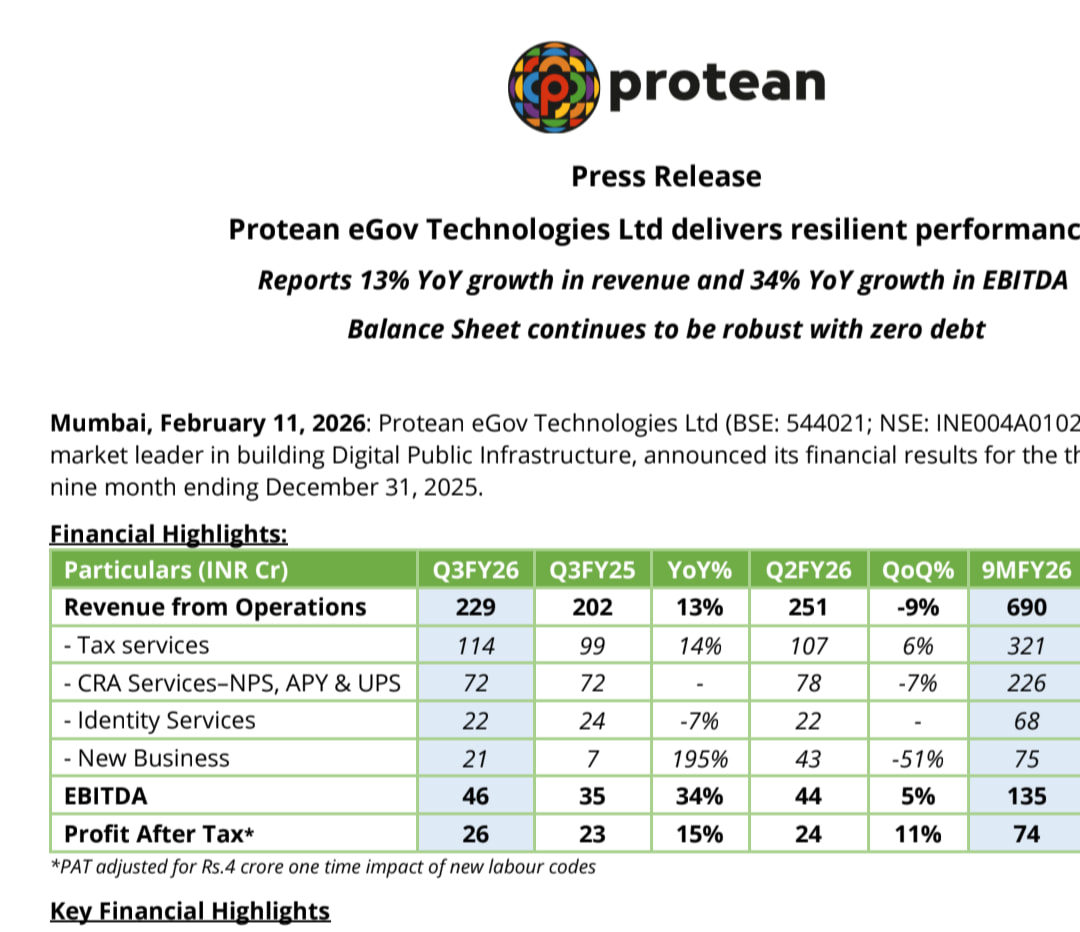
Overall, I get a feeling that the business is fraught with regulatory risk, as most of its dealings and revenue come from government or government agencies. Its largest business today which is PAN services, is at existential risk. Its sustainable, scalable, and toll-road CRA business is growing slowly and under a pricing reset. Future optionalities are currently margin-dilutive because of the initial build-out expenses, and margin accretion from those future optionalities seems to be a few years down the line, if at all it happens.
Company’s operating profit margin before the IPO was in the range of 16% to 23%, but it has now fallen to 12% as of FY26, and it is on a declining trend.
Thus, overall, I am negative on the business prospects and business model of the company for now.
Now talking about some positives of the company. It is a quasi-monopoly in the CRA segment. There are significant barriers to entry in most of its segments because of regulatory reasons and government protection and policy reasons. Also, there are high switching costs and very rare chances of switching in its CRA segment to pension schemes. Their past track record of execution of national-level digital public infrastructure projects makes them an ideal candidate for such future projects, and there could be new businesses that could emerge because of it. Also, the company is net debt-free and holds cash and cash equivalents of 850 crores.
The stock is currently trading at around ₹560 as of August 2026. The market cap of the company is 2,300 crore as of August 2026. Deducting the cash of 850 crs, the company is trading at an EV of 1,450 crs.
The valuation seems very attractive, but the business model does not. Thus, I will avoid this company for a long-term investment. I am buying a very tiny position to track the company. Having a small position helps me to track the company, and until clarity on the business model emerges, I would not want to buy a significant position in this company because it could turn out to be a value trap.