Your hypothesis totally sidetracks the issue. We are comparing the growth of company vis a vis that of peer groups. The point is why it failed in comparison to other players in the sector. That points to a big let down and unless backed by sound reasoning/explanation, it should be avoided with respect to others showing scorching growth.
1 Like
Well my understanding is that Carat lane is a very different business which heavily relies on diamond and studded Jewelry , Saaya is the only comparable parr of business that also higher ticket, correct me if i am wrong.
Also other players like png Jewelers (other gold players) will also get benefitted from 20%+gold price increase in same period, unlike gargi who sells at mrp mark down and not really per gram metal?
I would wait for management commentary to understand this better.
Clearly more people are disappointed with the update which is reflecting in stock price.
3 Likes
-
The results were announced on Friday evening, company grew sales by 11% with improved gross margins YoY, while PAT fell by 5%. So, higher employee cost reduced the margins. Hiring more employees is a good sign in my opinion as they are looking for growth and opening new stores (9 in Q1)
-
Qoq gross margins have fallen from 46.1% → 42.2%. –> most likely due to the drop in silver price since they sell their product on MRP and not on actual silver value
-
Despite opening 9 new stores (mostly FOCO) where the sales is front loaded, their sales has not grown substantially and its very disappointing when the management was targeting 35% growth. Their sales growth has always been lumpy due to seasonality of the business, but one thing is certain they are facing challenges in growth.
-
Adhik maas has impacted the growth across many companies not only PNGS. It’s just that the gold prices have increased YoY which is hiding the volume growth across many companies.
-
Q2 of the company is expected to be slower as well due to higher base last year and shifting of Navratri to Q3. This is seasonal and one should look at normalised growth.
-
They have clearly stated that the demand is weakening due to West Asia war in their q1 results document and may have to revisit the growth guidance. Mostly, they will not achieve the 35% growth guidance for FY27. In their q1 results update they mentioned that the demand is strong is expected to pick up in 2nd half. In their PPT as well they have mentioned to grow at 35% for FY27 Aand beyond. So there is clear descripancy in their disclosure.
-
Their EBO don’t generate that much revenue as compared to PNGS SIS. EBO sales are up 186% which means that non EBO sales is -6.3% YoY. Since they are planning to grow more EBOs and their SIS stores are not growing as much, their sales will be impacted for some quaters to come.
Any views and thoughts?
3 Likes
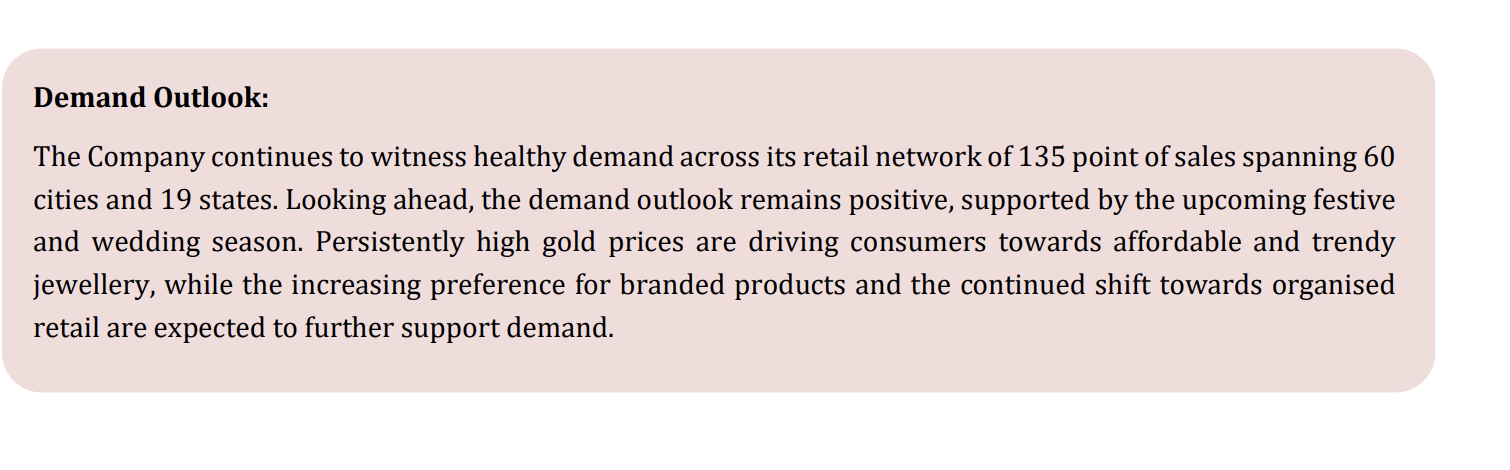
One confusing thing to note is that the same management in their Q1Fy27 business update mentioned that “the company continues to witness healthy demand across the network and demand outlook remains positive”
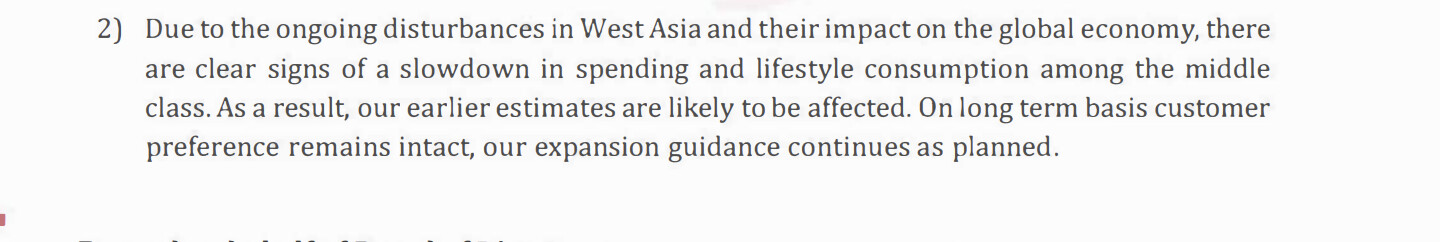
Same management in their official Q1 results mentioned, “Due to west asia disturbance, there are clear signs of slowdown in spending and their earlier estimates may be affected” .
So net net, the company is saying that they won’t be able to achieve the 35% guidance that they had given at the start of the year. But why share these 2 contrasting remarks within just 22 days? why not conduct a concall and clear the doubts and apprehension of the investors?
5 Likes
For SMEs, mgmt is everything.
Mgmt skipped earnings call this time. This coupled with poor Q1 performance itself is a red alert for me.
4 Likes
Surely a red flag and mgmt character comes out in tough times only
Hoping for a delayed con-call and waiting for any Development on mainboard listing
As of now giving mgmt benifit of doubt that they are new to public market and IR 
5 Likes
Also they don’t have export business. Not sure how west asia situation would impact their demand, if at all. I suspect it is more due to competition and lack of brand recall/irrelevance of brand for the product segment they operate in.
Certainly not doing concall when things dont go well is not a good sign.
3 Likes
The stock price has seen quite a violent beatdown over the last several months. I’m invested as well and want to mention that outright. Thoughts and open questions across three parameters i consider important:
(1) Change in distribution
The earlier growth this company enjoyed was on the shoulders of its parent company through the SIS network. That growth had an organic ceiling, and the company had to move to other pathways to increase reach. This is what they are doing by continuing SIS, opening EBOs, and building online.
Current mix is roughly 78% SIS / 22% non-SIS, with a stated goal of taking PNGS SIS dependency down to 65% by FY28.
Opinion:
-
EBOs grew 186% YoY in Q1 FY27 and now over 22% of revenue from under 9%. This is the way ahead for obvious reasons.
-
On margins across channels, management’s position is that EBOs capture the full gross margin but also carry rent, advertising and electricity, so profitability stays broadly stable rather than expanding. They said the same in June 2025 that “margins are almost matching to each other, not 45% versus 30%.” So nobody should expect the channel shift alone to lift margins.
-
EBO unit economics stated is that breakeven 15–18 months outside Maharashtra and 6–9 months inside. Most of the EBO stores are still inside its gestation window, which icould be a part of the answer for the Q1 drag.
-
Management guided SSSG at PNGS SIS of ~30–32% in May 2026 and “not less than 25%” in February. Q1 FY27 SIS degrew 5%. That is a swing of roughly 35 points on the same store base in one quarter. Either same-store performance has collapsed, or SSSG is being measured on sell-out while reported revenue is sell-in and the gap is destocking. This is my biggest open question.?? (Any thoughts are appreciated or perhaps 35% SSSG should be looked at annually as the business has good and bad quarters).
-
On Reva: Gargi sells HI colour diamonds, Reva sells EF colour which are pocket-friendly versus premium. But they have also said 9KT gold is deliberately kept out of the 33 PNGS SIS locations “due to conflict of interest.” So channel conflict inside the parent’s stores is real enough to exclude one product line. The question is why 9KT is excluded and 14KT diamond is not. (There is a reason premium cars are sold in different showrooms from mass ones — Maruti and Nexa, Toyota and Lexus. Specially as it leads to less confusion on what to push to consumer inside the showroom)
Questions for management: (1) sell-out versus sell-in growth for Q1 FY27 (2) how SSSG of 30% in May sits with SIS degrowth of 5% in June (3) how the FY26 EBO stores track against the 15–18 month breakeven.
2. Change in product mix
Three lines: (i) sterling silver 925 (ii) 14KT natural diamond (iii) 9KT plain gold. Mix moved from roughly 56:34:03 in FY26 to 67:22:06 in Q1 FY27 which means more silver and less diamond. (REVAs story is indicating consumer demand for diamonds on quite the opposite spectrum)
Opinion:
-
The mix shift is not what caused the margin fall. Management disclosed gross margins that silver around 55%, diamond 45–47%. Diamond is lower because the gold component carries thin margin. So a shift from diamond to silver should have added to blended gross margin.
-
But gross margin fell anyway. That means the mix was a tailwind and something else destroyed it. This is the part I find most concerning in the quarter.
-
The likeliest reason is silver prices jump, MRPs are already labelled at older rates, subsequent purchases come in at higher cost.
-
Separately, management guided in February to 45% diamond / 55% silver by H1 FY27. Diamond has gone 38% (9M FY26) to ~35% (FY26) to 22% (Q1 FY27), against a 45% target. That is a large miss on a specific number they volunteered, and it has not been explained.
-
Reported PAT degre by 5% including the one time seperate income. Management guides PAT marging 20–22%. Q1 sits outside their own band.
Questions for management: (1) if silver is the higher gross margin line, why did gross margin fall as silver mix rose (2) is the MRP labelling lag repeating (3) where does the 45% diamond target now stand.
3. Marketing and branding
Gargi is building a brand off the parent name and uses a brand ambassador. Online was 4.5% of sales as of June 2025, with a target of 10% and management explicitly resetting the timeline to a minimum of 2.5 years. An app was planned and there is a Blinkit tie-up for sub iNR 1,000 Procut lines. No updated online number has been given since.
Opinion:
-
GIVA spent ₹135 cr on marketing in FY25 against ₹518 cr of revenue and lost ₹72.3 cr to reach a 50/50 online split. Gargi is declining to run that playbook but it caps online at their own stated 10% ceiling over a 2.5 year horizon.
-
Which means digital is not a swing factor for FY27 either way. The weight sits on EBO maturation and on whether the SIS book stabilises.
-
One observation from my own checking is that discounting on Gargi’s Amazon listings appears to have deepened. Thing to confirm is whether the same discounting is running on the website and in EBOs. iF the discount is across all channels then it is potentially a consumer demand signal, and it would mark a shift from management’s stated position in June 2025 that abnormal discounting and marketplace terms were not something they would pursue.
Summary
The past growth was SIS-led. The future depends on how the branding–distribution–productmix triad evolves.
What is reassuring is that the management guides conservatively in “not less than” and has delivered above its store guidance, is debt free with ₹78 cr of cash, funds expansion from internal accruals, and has a coherent explanation for why channel mix will not lift margins. The EBO unit economics are disclosed.
What is not good is that the gross margin fell in a quarter when mix should have helped it, the SIS book swung from +30% SSSG guidance to -5% reported, diamond mix went to 22% against a 45% target, and Q1 landed outside the company’s own PAT margin band. None of that has been explained, and there is no concall due!!!
Things I am watching (1) whether gross margin recovers or falls again (2) whether diamond mix moves back toward the 35–45% range (3) receivable days, since PNGS pays within 2–3 weeks and Shoppers Stop monthly on sell-through, so days outstanding should be low (4) marketing holding at 4–5% of revenue rather than spiking to defend revenue.
Also worth tracking: main board migration was targeted for around September 2026.
P.S. I contacted investor relations about a concall. The answer was that the company does not schedule one after every quarter. Given the Q1 numbers, a call would be welcome. If anyone has management responses on the SSSG-versus-SIS gap or on the gross margin decline, please share.
5 Likes
Arihant Capital Investor call notes:
Drop in Q1 FY27 top line due to change in procurement policy of parent company, they want the inventory just in time i.e. 7 days.
SIS retail increased from 16 Crores in Q1 FY26 to 27 Crores in Q1 FY27
PAT margins expected to be 17%-18% due to EBO expansion
Takeaway: FY27 PAT estimate = 1.25*149*0.18 = 33.525 Crores (FY26 PAT: 31 Crores)
Revenue growth guidance reduced to 25%
Disclosure: Invested & considering to exit the position
2 Likes
I think company has become extremely conservative post Q1 FY 27 results (as they used to beat their guidance comfortably in the past and this is the first time they encountered a rough patch so its natural reaction)
So I expect actual results to be better than what you estimated above. I am ready to give them bit longer rope due to their honesty while answering the questions.
2 Likes
Revenue hit because of JIT inventory from parent is a big relief, for a growing company, revenue/demand being intact is the biggest thing, margin is a function of investment in expansion so not so high profit growth for the year is okay as long as revenue growth is intact
PS: Invested and Biased
2 Likes
Anyone have transcript or recording of call?
Thoughts on mediocre results posted?
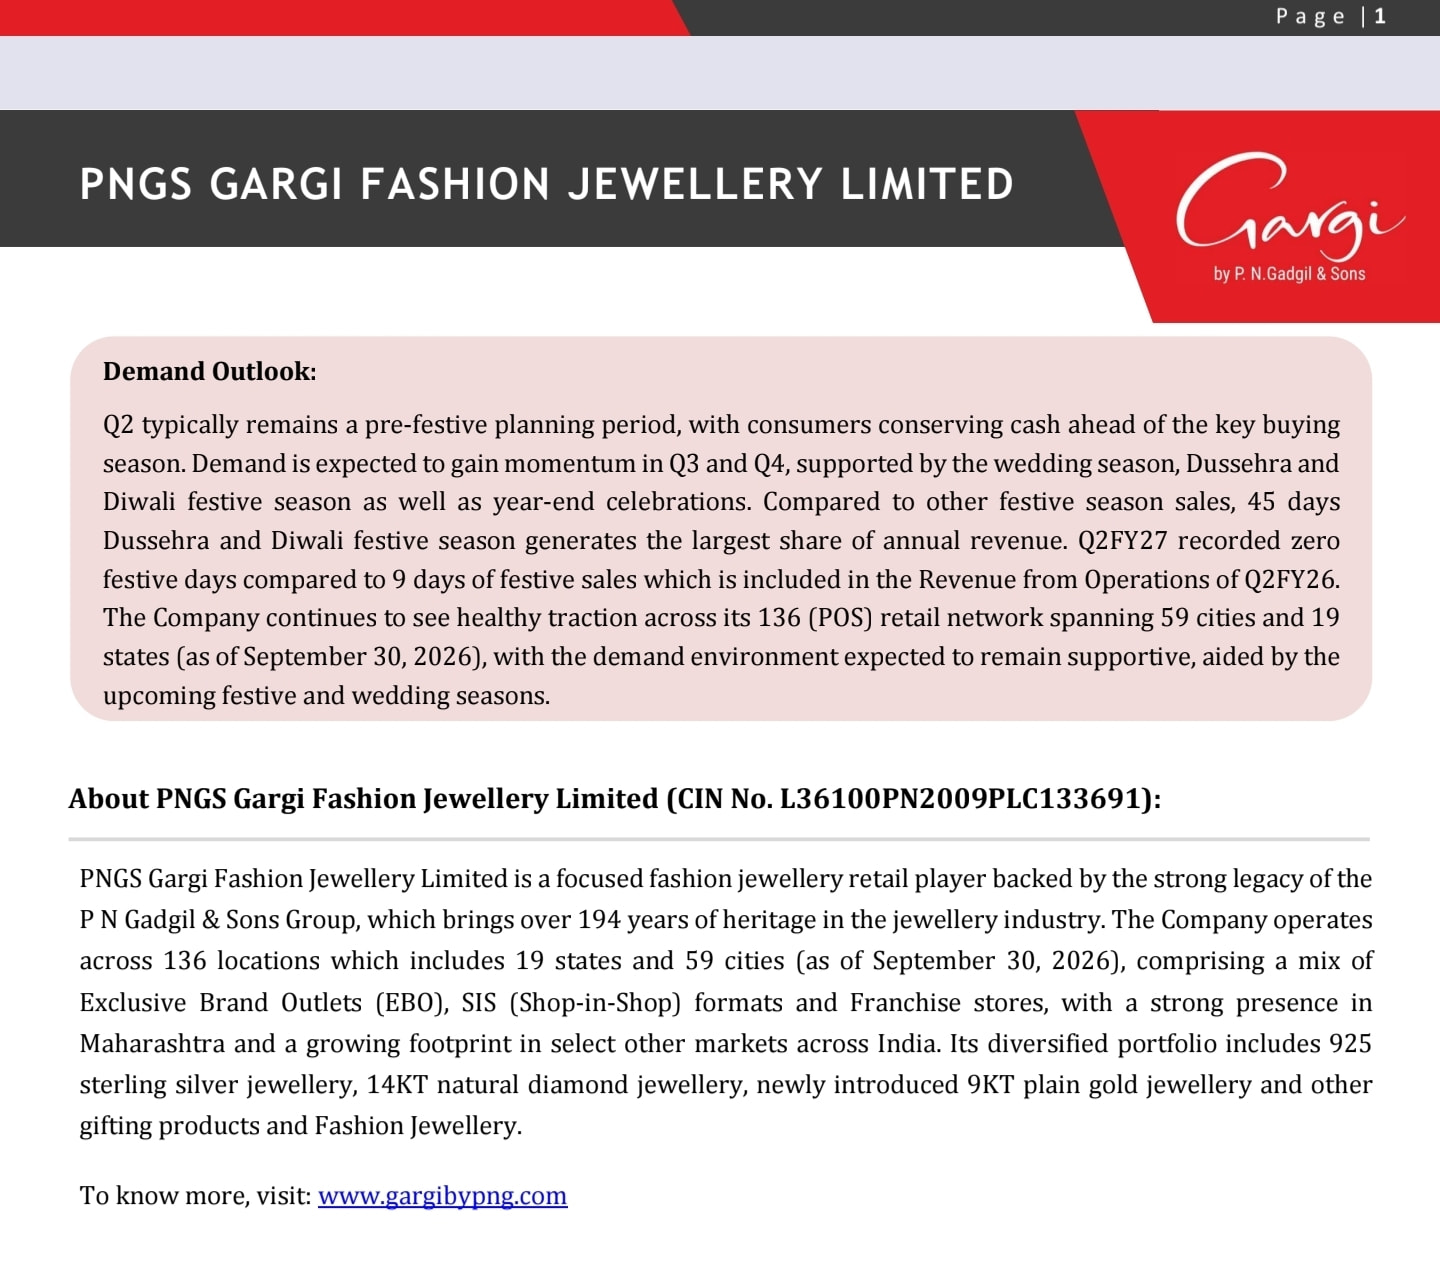
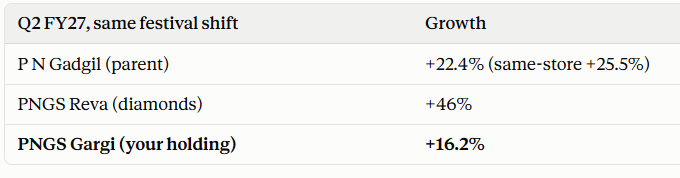
Management says consumers are conserving cash for festive season xD, similar logic could also been applied to Reva which on the other hand posted good results. It is becoming reasonably clear that they are finding it hard to scale in category they operate it.
2 Likes
Not sure if this is a bad update. 16% YoY growth when last year Q2 had 9 days of festive sales included (which is clear from flat QoQ last year between Q2 and Q3)
if there was no festive days last year in Q2, the sales would not have been more than 40-42cr, if i consider 42cr as base this means 28%+ YoY growth
Frankly this quarterly update is quite a relief after Q1 update. I expect them to post 40%+ YoY growth in Q3 which, if happens will make 9M YoY growth at about 25%, which in my view is healthy.
PS: Invested and Biased
7 Likes
I am jotting down some points. Some connected to my earlier post and others as answers to some questions raised on this thread. Mostly, i am doing this to maintain a thought process and could have done it privately but do think it may add value to others and some questions/critique may add value back to my thought process.
Businesses do grow in ‘spurts and falls’. Such is the nature of the untameable and unpredictable beast!
The management had earlier given a guidance of 35% Rev growth for FY27 and beyond (3 years hence). This guidance was then reduced to ‘Not less than’ 20-25% for FY27 and beyond during the bharat connect call. I concur with Priyank on his conclusion that 25% is a health growth but it also depends on what was the base rate earlier. Needless to point, Gargi is facing the fate of the high flyer who once-in-a-while comes too close to the ground and not necessarily crashes. The scare exacerbates; reputation and perception falls much faster than the actual business.
The Bharat connect call answered one of the crucial questions which had bothered me earlier:
- The SSSG Gap in Q1FY27 result was a result of de-stocking as the parent PNG stores (SIS) have asked Gargi to transfer inventory on Just-in-time basis. Basically sell-in reduced in Q1 as a summary. (Sell-in is what is now reported by Gargi in its quarterly disclosures). For reference, in Q1 the sell-out growth for SIS was 68%!!! In summary, a lot of inventory was lying with SIS which was now sold off to the end customer.
Also, this reinforces the point that the SIS growth in Q2 and beyond might also be reflective of the end customer sales as the sell-out should now closely track the sell-in. - Furthermore, the management stated that during the EBO build out phase PAT margins would be 17-18% and then revert to 20-22% when the stores mature. Logical and now must be tracked.
Open Questions still and trackables:
- What is the total sell-out growth in Q2 FY 27. (the end customer sale growth). What are the inventory stocking guidelines for EBOs. The latter would help us all understand the total sell-in and sell-out going forward. For reference again, in Q1 the sell-out growth for SIS was 68%!!!
- What led to the Gross margin dent in Q1. Was it the MRP labelling issue or something else? (Since gross margins should have improved in Q1 on account of accelerated silver component of sales vs. diamond and former is higher margin)
- Have the marketing spends accelerated in Q1 and Q2 or are at 4-5% of the revenue? I reckon atleast in Q2 the marketing spends have increased substantially. (basis some other data i track and will be revealed once the results are out).
- PAT Margins in Q2 and beyond. Are they contained at 17%+ or dented further? (As per the management SIS Margins are fixed; so the margin expansion if it comes will either reflect EBOs doing well or product mix changing and must be tracked accordingly)
- 136 POS as of end of Sept 2026. Does this number touch ~150 By March 2027?
- EBO contribution to total revenue reduced from 22% in Q1 to 18% in Q2. Partly, as the SIS sell-in was contained in Q1 and then must have normalised in Q2. Anything else to read in here except the fact that SIS sell-in has normalised in Q2 FY27.
P.S: We should brace ourselves for a slight PAT de-growth in Q2FY27 as well.
4 Likes
@amrit would you have any update or signal on their mainboard migration? Was this touched upon during bharat connect?
1 Like
Not discussed but it should be during the con call this time around.
The entire discussion from the Bharat connect is readily available on concall.in.
3 Likes
Read the complete bharat connect con call, It might sound optimistic at this point but i feel management is being conservative with the slowdown they witnessed in Apr and May. If Macro do not get very adverse, there is always a possibility for them to witness stronger Q3 & Q4 (> 40% YoY or > 20% QoQ in Q3) which might take annual top line > 30%.
Its new for the management to deal with public money/investors and they take huge pride in their 195 year legacy and has always played conservative historically. Infosys for years have followed underpromising with their guidance and outperforming. Most good management, i would say, in India follow this
Q3 should offer much better clarity on demand outlook
4 Likes
This year bottom line may remain flattish as margins are also dropping as per commentary.. FY 28 will see the real growth..
2 Likes
Hi Sumit, the parent company you have mentioned is a separate listed entity with different management and promoters. It is not the parent company of gargi and reva. The parent company of reva and gargi is an unlisted entity.
1 Like