USL also ? I believe Godawan is from USL.
That could be a good promotion for Godawan. All indian single marts already been exported to these markets including Indri. Post operations start of Portavadie plant in UK, Indri will be locally produced. Anyone any idea when will this plant will start selling?
1 Like
No…Indri can not be produced in Scotland.
By definition, a single malt can only be produced in a single distillery…
But the Scotish distillery will be used to sell locally in UK n to sell in India as Scotch single malt/ blended whiskies with different brand names.
2 Likes
Indri is also being sold through Amazon UK along with other channels.
3 Likes
This isn’t conclusive at all. All the shares could have been issued at 10k / piece
No sir - premium is part of equity & not reserves and surplus. Your paid up equity capital as reported to MCA includes face value + share premium
In a way it is good if the co is holding these non-core assets that have monetizable value in future. Especially because these are legacy and its not that Piccadilly is investing additional sums in it in the last 4-5 years.
So focus of present management is clear.
4 Likes
The assumption of Rs 6000 Cr + valuation for Piccadily Hotels is based on a wrong calculation.
Just to clarify the arithmetic. If a private company has issued a total of 62,600 equity shares issued at Rs 100 face value + premium of Rs 9900 i.e. Rs 10,000 per share then the “valuation” of the company is 62,600 x 10,000 = Rs 626,000,000 i.e. Rs 62.60 cr. Hope this helps.
2 Likes
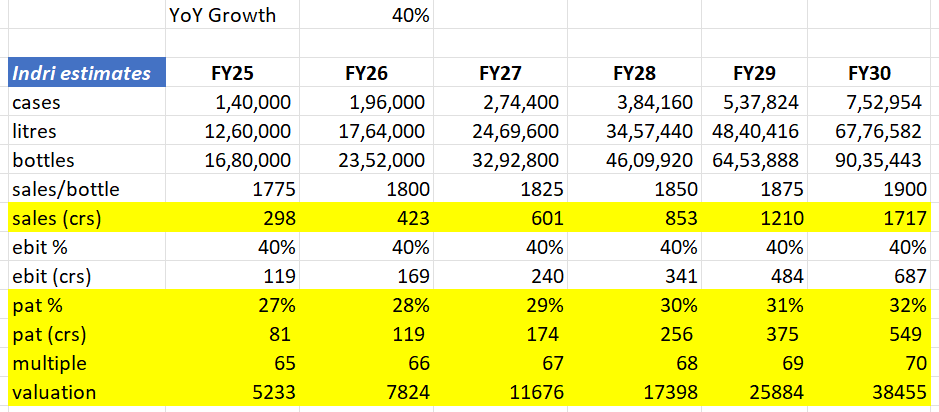
Tried doing some math for Indri… I feel my FY26 numbers are very conservative. In likelihood (if overall consumer sentiment picks up), FY26 numbers for Indri can be around 220k.
What’s interesting is valuation of Indri alone is going to exceed current mcap in 1 year
3 Likes
What supports your assumption of taking 27% as net profit margin for Indri?
27% PAT margin translates to 36% PBT margin assuming a 25% effective tax rate
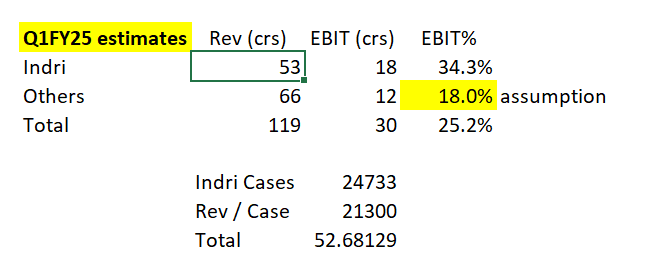
Q4FY24 which had higher proportion of Indri sales in the overall distillery segment had a 31% EBIT margin. Even if you allocate all of interest & other cost to distillery segment, the PBT % would have come up as 29% for the distillery segment.
Now this 29% is composed of low margin country liquor and ethanol sales and high-margin Indri sales. It’s anyone’s guess as to what margin Indri would have given that country liquor would be mid-teens at best.
I tried to do the above math for Q1FY25 and here’s the estimate:-
Another way to look at this is 70%+ gross margins. Take another 25% for SG&A and all other kinds of opex. That gives you 45% EBITDA. Interest & Depreciation - take another 10% worst case. 35% PBT and you have 27% PAT after assuming 25% tax rate.
In my practical view though, gross margins would also inch up as special editions of Indri gain traction. They sell at nearly 2x price point, which means gross margins may be substantially higher for them.
7 Likes
Alchemy Capital Management Private Limited, which had consented to subscribe to up to 2,68,817 CCDs, has not been allotted any CCDs by the Company due to their PAN is reflecting equity trades, as per the queries raised by BSE.
Ms. Deepa Sondhi has declined the offer to subscribe to CCDs made by the Company. Therefore, the Company will not be allotting any CCDs to Ms. Deepa Sondhi."
This caught my attention. I wonder what the part about Alchemy Capital means. It’s not very clear.
1 Like
If my understanding is right, if you have prior holding, then preferential gets cancelled. Saying on the basis of experience (not sure if its across the board) of having participated in a preferential issue recently.
In any case, another fund of Alchemy has subscribed, so seems like a technical error rather than anything else
3 Likes
It is about the allotment for Rekha Jhunjunwala via Alchemy that company filed disclosure for.
The outlook just keeps getting better.
Indian whisky brand Indri makes retail debut in Tesco | The Grocer
(Tesco is the largest grocery retail chain in the UK)
10 Likes
Curious if export realisations in general in this space are higher? Indri is being retailed at GBP45 for 700ml bottles, which is far higher compared to Indian retail prices.
This is big deal to get to costco stores.
https://www.mensjournal.com/news/costco-2024-whiskey-advent-calendar
9 Likes
4 Likes
- Company to come up with ESOP policy. Honestly, if they demerge the sugar business out, from a corp governance standpoint, the management is making all the right noises
4 Likes
I have been proved wrong in the past, my growth estimates were too conservative and the company have surpassed them. Going forward, I think the investors expect 50% annual compounded growth in Indri alone, so 10X in 5-6 years making it a millionaire brand. By the way, if this has to happen the bulk of the growth will have to come from the international market, not just domestic market. Also note that this is just Indri’s growth expectations, not including Camikara rum or any other new brands which will be launched.
If the company meets the growth expectations then the stock price growth should be front loaded, say 5X in 2-3 years. On the other hand if there is any slightest slip up in growth, then the scrip will be punished.
6 Likes