Pi Industries: From Agchem CSM Giant to Industrial Giant

Executive summary:
The current headline is one molecule is ~43% of revenue, its patents have expired, generics have landed in the US, and the partner has guided its own sales down ~11%. All true albeit partially but it describes PI as it was, not as it is being rebuilt. A read through the environmental filings, SEZ approvals the Technology Absorption annexures of the annual reports, the media briefs, interviews — and a different company appears: one converting a single-molecule dominated contract-manufacturing franchise into a multi-vertical fine-chemicals industrial platform, where agrochemical CSM is the cash engine rather than the whole business.

A brief history: PI began in 1946 in Udaipur as Mewar Oil & General Mills — an oil mill, not a chemicals company. It moved into agrochemicals through the 1960s–70s, then made the decision that defines it today: rather than compete as a generic molecule producer, it built a custom synthesis & manufacturing (CSM) business serving global innovators from the 1990s. That traded volume for chemistry depth, and it compounded — the Kumiai relationship alone drove ~19% CSM revenue CAGR over a decade, and PI now works with 20+ innovators (Kumiai, FMC, Syngenta, ADAMA, Sumitomo, Bayer, BASF, Kureha, Nissan Chemical, Corteva).

The asset base grew : Udaipur (1946 origin; today the R&D nerve centre — 4 R&D centres, 700+ scientists, 200+ PhDs, and a fully automated 1 MT/day flow pilot plant) → Panoli, GIDC Ankleshwar (technical + formulation; materially expanded by the Isagro Asia acquisition completed Dec 2019, which added a site plus 18 domestic and 91 export registrations) → Jambusar, in the Sterling SEZ, Bharuch — the growth engine, built from an original 7,000 MTPA environmental clearance in 2011 and now home to the Flow MPP (commissioned FY26) and a phosgene MPP under construction. The July 2020 QIP placement document disclosed 17,362 MT of technical capacity. The current environmental clearances are far larger: the two Jambusar units are cleared at 43,240 and 44,240 MTPA respectively. FY26 AR describes 16 multi-product plants across 150+ acres add to these the three overseas legs added since 2023 — Lodi (Italy, EU-GMP API), St. Louis / Seattle (PI AgSciences biologicals) and **Hyderabad / Alabama (pharma discovery).
**
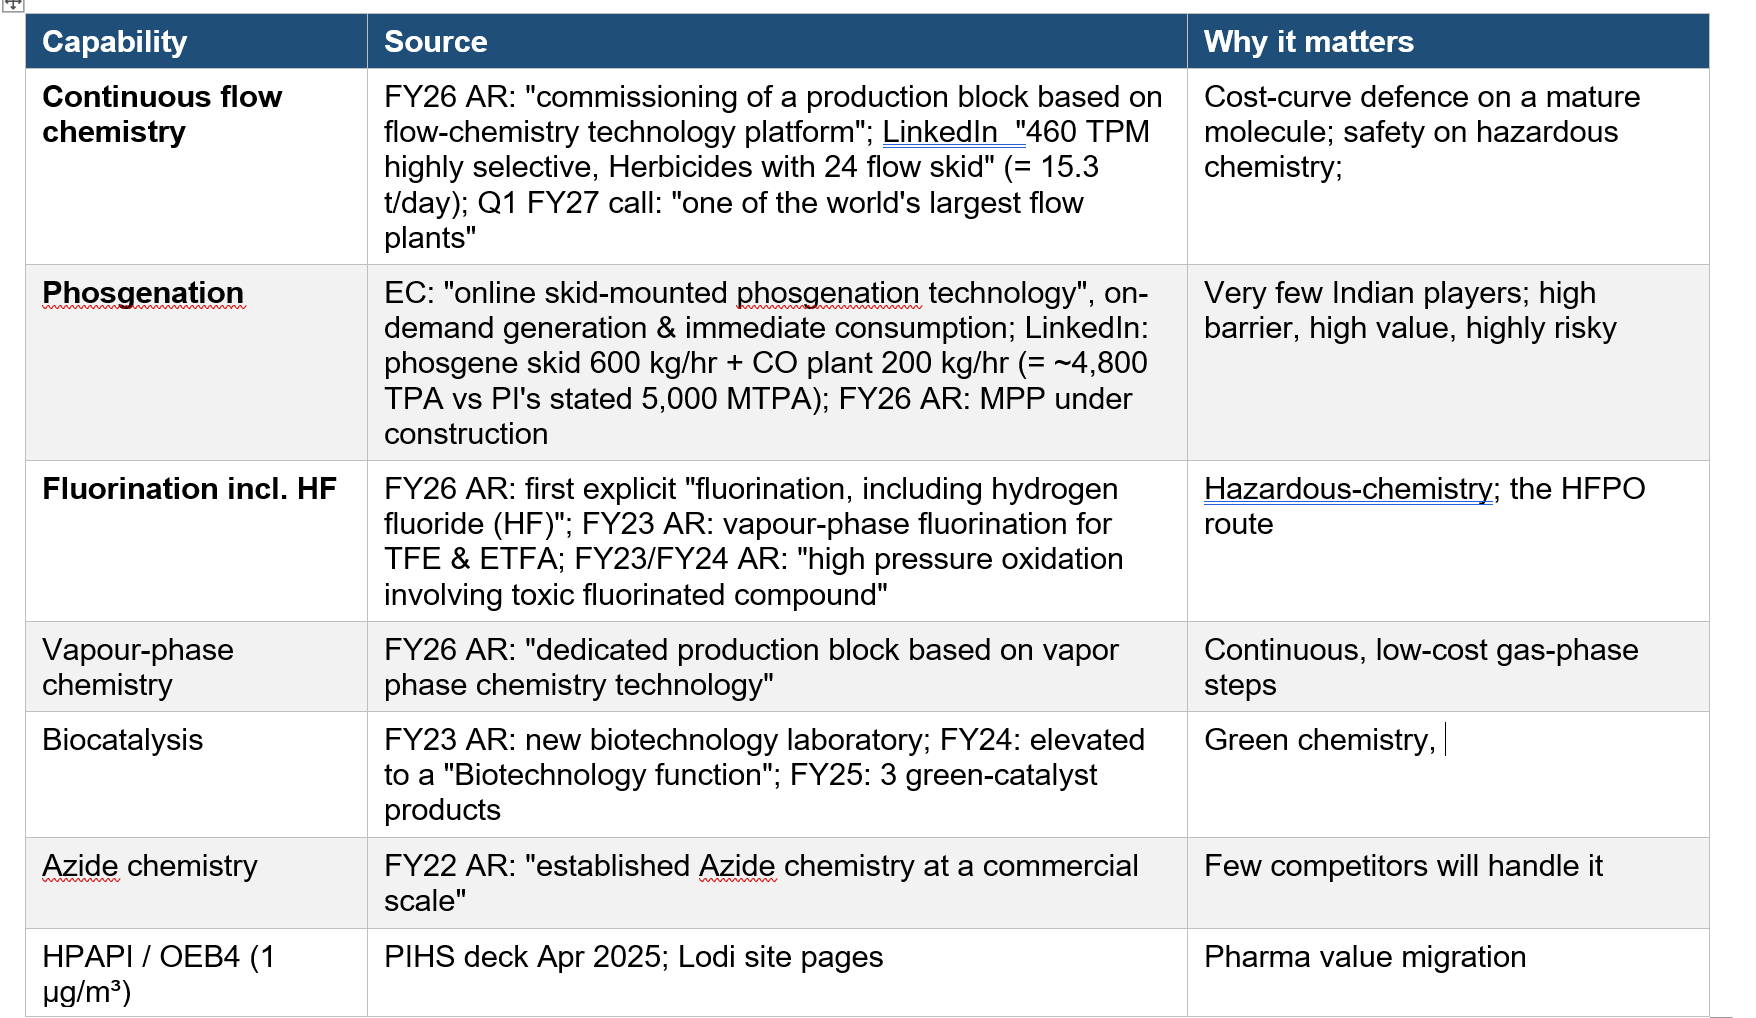
The capability stack:
Six businesses

Agchem CSM — the cash engine (~80% of revenue), still pyroxa-heavy but with 15–20+ new molecules commercialised in three years

Agchem domestic — brand-led, now getting genuinely novel chemistry (dicloromezotiaz)

Biologicals (PI AgSciences) — peptide/protein plant-immunity platform; small, differentiated, very high EBITDA, loss-making

Agchem NCE (Pioxaniliprole) — India’s first indigenously discovered insecticide; own IP to ~2039

Pharma (PI Health Sciences) — CRDMO across India + EU-GMP Italy; mid-turnaround

Electronic & performance chemicals — a brand-new 1,000 MTPA cleared group, commercial plant running, >50% of new CSM enquiries as per company.

Before we jump into each segment the these in one line: The thesis in one line

PI spent FY22–FY26 converting pyroxasulfone cash into optionality across five new verticals, and is now at the point where those verticals must start showing revenue while the core molecule decays. FY26–FY27 is the proving window and the management has guided for growth this year. Balance sheet buys the time: debt-free, net cash ~₹35bn, FY26 capex ₹11,508mn falling to guided ₹500–600 cr in FY27 — the heavy build is largely done.

Sources
PI Integrated Annual Report FY2025-26 (Manufactured Capital, Intellectual Capital, Annexure ‘F’ Technology Absorption)

PI Integrated Annual Report FY2024-25

PI Annual Report FY2021-22 (Annexure ‘E’ — azide chemistry, electronic chemicals foray)

PI QIP Preliminary Placement Document, July 2020 — last certified installed-capacity table (17,362 MT)

Environmental Clearance, Jambusar SPM-29/2, granted 17 Sep 2025 (IA/GJ/IND3/539466/2025)

Environmental Clearance, Jambusar SPM-28 + SPM-29/1, granted 30 Jan 2026 (IA/GJ/IND3/539236/2025)

Q1 FY27 earnings call transcript, 12 Aug 2026

Saumendu Mandal, VP & Design and Engineering Head, PI Industries — LinkedIn profile
Isagro Asia merger scheme / completion (Dec 2019)

22 Likes

AgChem CSM: The Engine

The elephant in the room Pyroxasulfone: PI never says “pyroxasulfone” on a call — management refers only to “our largest molecule” and declines product detail citing the confidentiality agreement. But a Government of India document breaks the confidentiality for them. The 97th SEZ Board of Approval agenda (Ministry of Commerce & Industry, 20 March 2020), on PI’s application to procure chlorodifluoromethane (a restricted item), records: *“…they are utilizing this raw material for manufacturing activity of their product named Octopussy/ Pyroxasulfone Technical…”
*

The partner side: The pyroxa based product is Axeev and the partners are Kuimai (innovator) and BASF + FMC (formulator and US distributor). From Kumiai Chemical’s own IR (FY ends 31 Oct): FY2025 Axeev sales came in at ¥75.4bn, a record high, +¥4.4bn YoY and a ~14% beat on the ¥66.1bn plan. FY2026 guidance is ¥67.3bn, −10.7%. H1 FY26 Axeev ≈ ¥38.7bn with US ¥32.5bn (+¥5.6bn) but Kumiai’s own note reads “generic distribution is confirmed; we expect price pressure to intensify in H2”, and Australia shipped zero (−¥4.9bn). Kumiai raised H1 guidance on 9 Jun 2026 explicitly citing “shipments being brought forward… ahead of the entry of generic versions of our main product, AXEEV, into the U.S. market” — the FY26 decline is being front-loaded, and channel fill is borrowing from H2. The mid-term target of ¥84.2bn is conceded as “difficult”. Customer concentration (FY25): FMC ¥24.4bn (+45%) and BASF ¥21.8bn (−2.6%) — together ~61% of Axeev.

What happens to Pyroxa: The moat shifted from molecule patent to process and formulation patents. Generic entry timeline at a molecule stage for various countries are: Australia 2022 · Argentina 2024 · US FY2026 · Brazil ~2031.

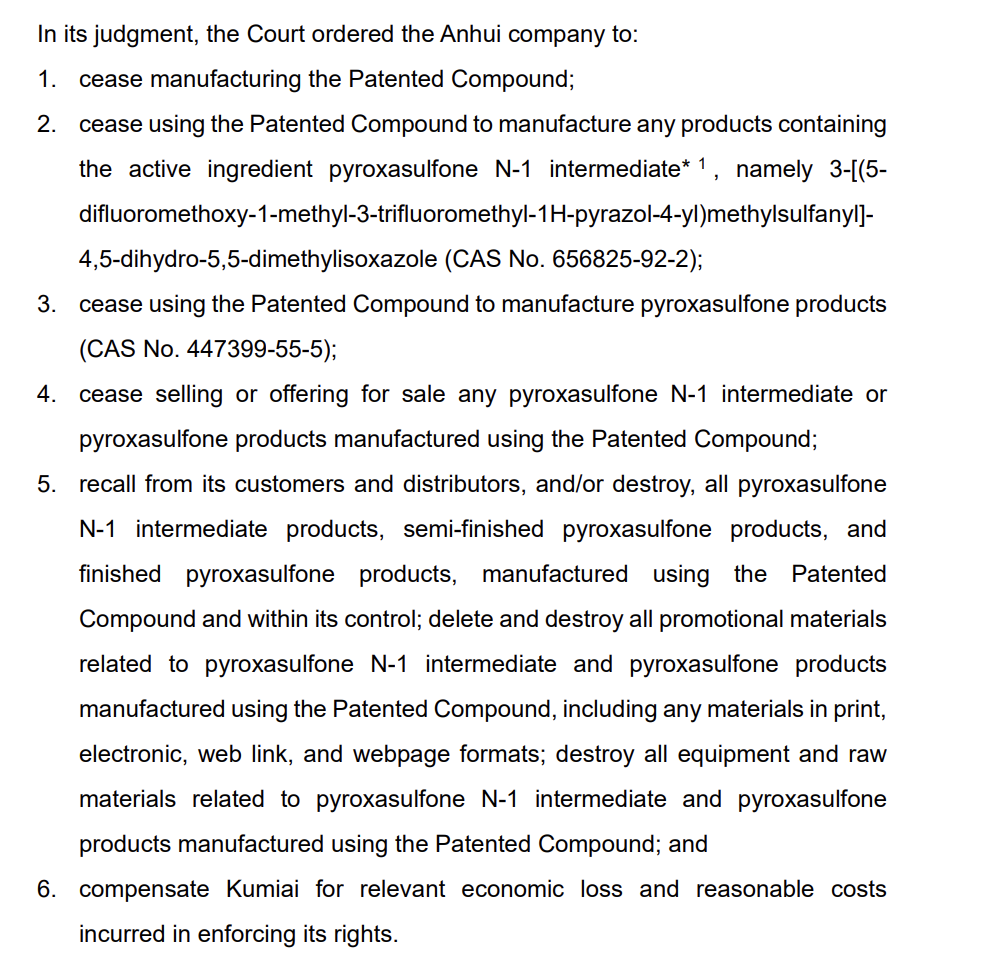
Kuimai has over the last few years filed multiple patent suits in China and Australia for process patent infringements. The Kuimai process gives better yields and the Chinese courts in their orders not only asked the 8 Chinese competitors from stopping to manufacture, destroy stocks but they also asked them to destroy their plants.
8 Jan 2026 — Australian process patent AU 2020300922 GRANTED, valid to 30 October 2040 (after Kumiai defeated ADAMA Agan’s opposition on 28 Nov 2025). The most consequential IP event of the cycle.

9 Feb 2026 — win at Hefei Intermediate People’s Court vs Anhui Jiuyi: permanent injunction, damages, and orders to recall and destroy all N-1 intermediate, semi-finished and finished pyroxasulfone, plus equipment and raw materials.

22 Jul 2026 — win at Ningbo Intermediate People’s Court (RMB 2.18mn damages); 21 Aug 2026 — further settlement. Earlier settlements vs ADAMA Australia (Jul 2024) and 4 Farmers Australia (Sep 2025).

30 Mar 2026 — Kumiai published its US/Canada patent portfolio, stating “From 2024, Kumiai has actively enforced its patent rights internationally” — a pre-emptive shot at US entrants.

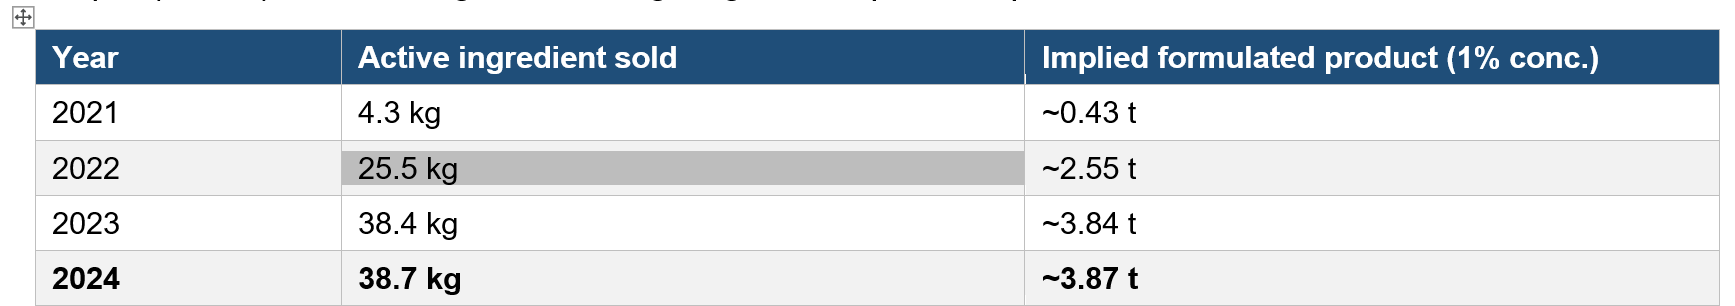
Lowest costs and the flow plant: Kumiai states in its 2026 AR: the company is “establishing an innovative technical-manufacturing method aimed at further production efficiency… by realising cheaper production we will improve Axeev’s profitability”, with the goal of being the world’s lowest-cost producer of the technical. From LinkedIn “Commissioning and stabilization of 460 TPM highly selective Herbicides with 24 flow skid.”, which comes to around 5500 tons. The FY26 AR confirms this “commissioning of a production block based on flow-chemistry technology platform”, with Annexure F stating “continuous Flow: One molecule successfully completed”.
In Q1 FY27 call mgmt confimed attaching flow chemistry to “our largest molecule today”.

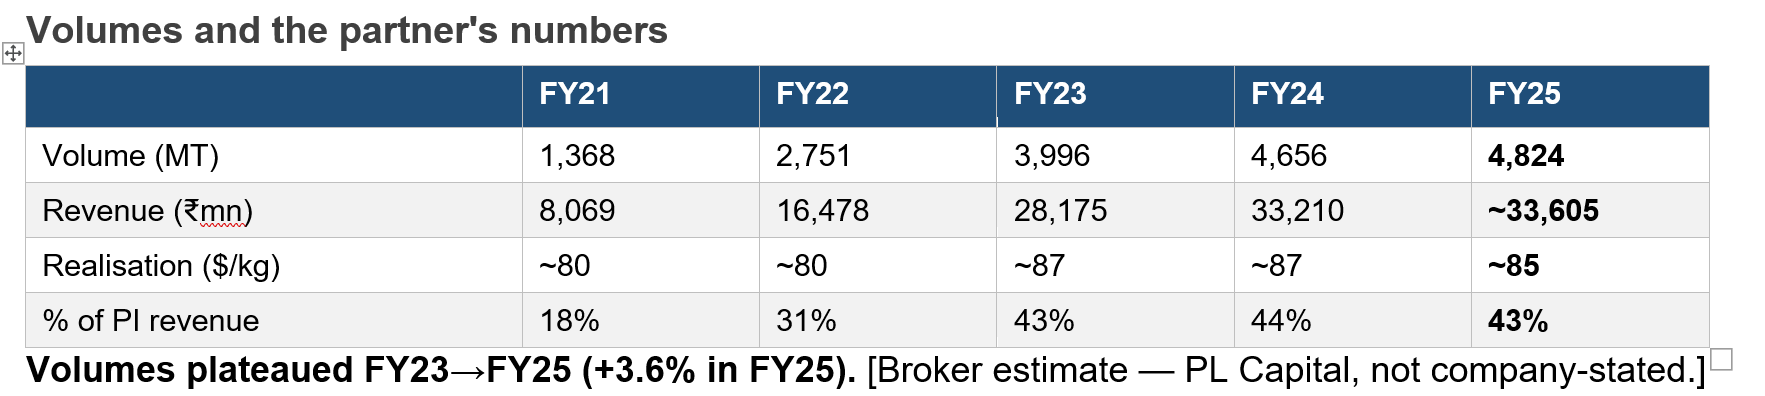
So what next for Pyroxa: Despite the patent wins by the innovator and the lowest cost mfg claims, the prices will keep falling as indicated by Kumiai. An example is CTPR where post genericisation the prices crashed but with interestingly the volumes went up over 10x in a period of 2/3 years. Pi + Kumiai have the most efficient process and hence the mass Chiense copying and with flow Chemistry this gets significantly better. The key question is can Pi arrest the fall by volume increase? Do understand that Pi adopts a cost+ model in its CSM business.

Newer molecules — the de-risking
20+ molecules commercialised in three years, now ~15–18% of CSM revenue.

FY27 plan: 8–10 new molecules, 5 already commercialised (Q1 FY27 call).

The interesting one: dicloromezotiaz

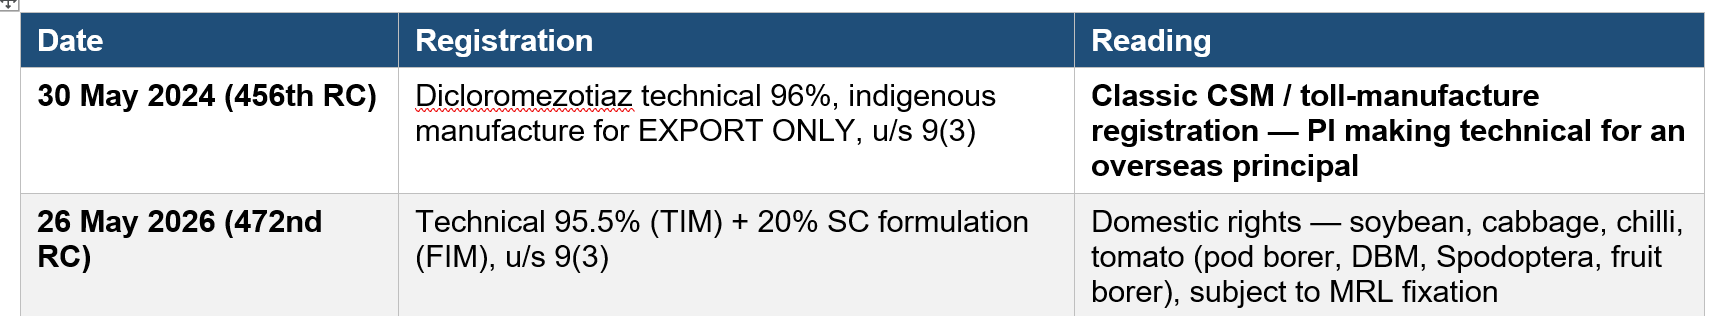
An insecticide , discovered by DuPont; the sister molecule to triflumezopyrim. The CIB&RC record shows PI’s classic playbook — CSM first, domestic brand second:

Who owns it? Not FMC or Corteva today. ZEN-NOH (Japan) acquired the development rights from FMC (ZEN-NOH press release, 4 Mar 2024), Japan registration as Field Mast Flowable (4 Mar 2024), sold from through Kumiai Chemical and Nihon Nohyaku. PI’s India SC is **20% — the same strength as ZMCP’s crop formulation.

Sources:
97th SEZ Board of Approval agenda, 20 Mar 2020 — “Octopussy/ Pyroxasulfone Technical”, Plot SPM-29/2

Jambusar Unit-II Annexure-I code→IUPAC legend, Jan 2017

Jambusar Unit-II Pre-Feasibility Report, Jan 2017 (44,240 MTPA product list)

Environmental Clearance SPM-29/2, 17 Sep 2025 (Pyrazoles 5,500 → 7,000 MTPA)

Kumiai FY2025 results briefing, 25 Dec 2025 — Axeev ¥75.4bn record; geography split

Kumiai H1 FY2026 results briefing, 26 Jun 2026

Kumiai upward revision, 9 Jun 2026 — “shipments brought forward… ahead of generic entry into the U.S.”

Kumiai FY2025 有価証券報告書, 27 Jan 2026 — FMC / BASF customer table

Kumiai Integrated Report 2026 — “innovative technical-manufacturing method”; ¥84.2bn target “difficult”

Kumiai — AU process patent '922 granted to 2040, 9 Jan 2026

Kumiai — Hefei court win, 9 Feb 2026

Kumiai — Ningbo court win, 22 Jul 2026

Kumiai — US/Canada patent portfolio publication, 30 Mar 2026

PI FY2025-26 Integrated Annual Report — Manufactured Capital & Annexure ‘F’ (“One molecule successfully completed”)

PI FY2023-24 Integrated Annual Report — Natural Capital (Jambusar SEZ insolvency litigation)

PI Q4 FY26 earnings call transcript, May 2026 — Flow MPP capex on agrochemical side

PI Q1 FY27 earnings call transcript, 12 Aug 2026 — “one of world’s largest flow plants”

PI Health Sciences corporate deck, Apr 2025 — “NCE, 15 tons/day, 8 step process, Gujarat”

PI Health Sciences flow chemistry brochure, Oct 2025 — JMB flow timeline

Saumendu Mandal (VP & Design and Engineering Head, PI Industries) — LinkedIn: “460 TPM highly selective Herbicides with 24 flow skid”

PL Capital initiation, 26 Sep 2025 — pyroxasulfone volumes and realisations

Sterling SEZ liquidation auction notice (IBBI), Aug 2025

10 Likes

AgChem Domestic: Brand led with novel Chemistry

Domestic has been the soft spot (subdued farmer demand, channel destocking, an FY26 regulatory disruption in biologicals). What is changing is the quality of the pipeline, not just the volume.

FY26 launches: three herbicides — Alcor, Comet, Fixit — and one insecticide, Uranus (positioned in PI’s own deck for mite control, so not a diamide or mesoionic; active undisclosed).

Jivagro — the horticulture specialist subsidiary, ~60 brands, with 8 biologicals/bio-nutrient products growing ~20% YoY.

PI Mitra Kisan — direct-to-farmer app, launched to deepen grower connect.

Harpin αβ approved in India (Q3 FY26) — brings the PI AgSciences biologicals platform into the home market.
Dicloromezotiaz domestic — This is considered as the best alternate for Diamide market where existing products have developed significant resistance. It primarily targets Lepidopteran insect pests viz., All larvae which damages economic part and internal feeders of the plant.

Sources:

CIB&RC 456th Registration Committee minutes, 30 May 2024 — dicloromezotiaz TC, export only

CIB&RC 472nd Registration Committee minutes, 26 May 2026 — domestic TC + 20% SC

ZEN-NOH press release, 4 Mar 2024 — dicloromezotiaz rights acquired from FMC; Field Mast registration

ZM Crop Protection — dicloromezotiaz product page (20% SC)

PI Q1 FY27 earnings call transcript, 12 Aug 2026 — “three-digit product”, launch this season

PI Investor Presentation Q3 FY26 — FY26 domestic launches; Uranus = mite control

AgroPages — CIB&RC upholds UPL’s pyroxasulfone registration over PI’s objection

Jivagro — PI’s horticulture specialist

9 Likes

New Businesses: Biologicals (PI AgSciences)

PI acquired Plant Health Care plc for ~£32.8min 2024, rebranded PI AgSciences in Nov 2025 — HQ St. Louis, biologicals R&D Seattle, operations in US / Brazil / Mexico / UK / Spain.

The differentiation is super interesting and geniune. PREtec — synthetic peptides derived from harpin protein that trigger the plant’s own immune response (Systemic Acquired Resistance). Because they are non-living, they are shelf-stable (no cold chain), tank-mixable with synthetics, (zero residue) and low resistance risk. That is a real gap versus microbial competitors (Bayer Votivo, Syngenta Clariva) which need cold chain and lose viability in tank mixes. This is in some ways similar to how vaccines in humans work. The amount required per hectare is in grams.

Key Assets:

Harpin αβ — biostimulant; US, Brazil, Mexico, Argentina, EU; now approved in India.

PHC279 (Innatus 3G) — Asian soybean rust seed treatment; Brazil approved Jan 2021.

PHC68949 / TEIKKO / ShaNema— the flagship: first foliar-applied peptide nematicide; Brazil Jan 2024 (seed treatment, P. brachyurus, soybean), Mexico 2024, US EPA federal registration announced 3 Mar 2026 (corn, cotton, soy, potato, tree fruit, nuts, vines; distribution via Wilbur-Ellis; state registrations pending). Plant-parasitic nematodes are microscopic, roundworms that live in the soil and feed on plant roots. Using a needle-like mouthpart called a stylet, they puncture plant cells to steal water and nutrients. This damage stunts growth, causes wilting, and lowers crop yields.

The Brazil background for biologics based nematicides: This is one of the more remarkable structural stories in agchem, and it’s not a single cause — it’s four reinforcing forces hitting at once:The trigger — the aldicarb ban (Temik). Aldicarb (Bayer’s Temik) was the workhorse broad-spectrum nematicide/insecticide in Brazil. When it was pulled, an enormous block of treated area suddenly had no standard tool. That vacuum had to be refilled by something — and because the replacements were newer, more expensive biologicals and next-gen chemistries, the same treated hectares now generated far more revenue per hectare. The biological explosion. The mix reversal: 2015 was ~94% chemical; by 2021/22 it was ~75% biological.

Actual sales for TEIKKO — from IBAMA, Brazil’s primary federal environmental protection and law enforcement agency.

Brazil’s IBAMA pesticide-commercialisation series names the active — “Peptídeos Derivados de Proteína Harpin (PDPH)”, MAPA reg. 35023 — giving an independent product-level volume series:

PHC gave an estimate of 110,000 hactares for 2024/25 which implies aroudn 35 grams a hectare usage for PHC68949.

Scale, economics and the ambition

• PHC standalone did ~US$11m revenue at ~60% gross margin (FY2023) — acquired at ~3x sales, an IP premium.

• PI has quoted a PHC run-rate of “$10–12m” (Q2 FY26 call) and an ex-India biologicals run-rate of ~$12–13m at >60% margins.

In Q1 FY27 it was stated that global biologicals ran an EBITDA loss of ~₹120 crore in FY25.

Ambition vs precedent. PHC Brazil GM Rodrigo de Miranda has targeted US$150m in Brazil over 3–5 years, with TEIKKO volume guided from 22 kg to 3.5 tonnes. In the recent call mgmt sizes the Brazilian nematicide market at ~$750mn with ~5mn ha of farmer trials and said “a double-digit market share is not a challenge.” The competitors are at Corteva ~$476m, Syngenta ~$400m, UPL/NPP ~$365m. The fastest-scaling novel nematicide ever, Bayer’s fluopyram, compounded at ~35% ($13m 2012 → $189m 2021).

How is PHC68949 different: As mentioned earlier PHC68949 triggers the internal immune system of the plant unline the existing biological nematicides. The “foliar + tank-mix” operational advantage is real and near-unique — no specialised equipment, works with existing spray passes, mid-season rescue, no cold chain which none of the existing biologic nematicides offer.

Sources

Brazil approves TEIKKO (PHC68949) — Plant Health Care RNS, Jan 2024

PI AgSciences — US EPA federal registration of PHC68949, 3 Mar 2026 (Wilbur-Ellis distribution)

IBAMA — Relatórios de comercialização de agrotóxicos (PDPH volume series)

ADAPAR — TEIKKO bula (dose 30–120 µg/seed; MAPA reg. 35023)

AgroPages — Plant Health Care launches TEIKKO in Brazil (110,000 ha projection)

PI AgSciences integrates Plant Health Care — PR Newswire, Nov 2025

AgroPages — PI Industries to acquire Plant Health Care for £32.8m

Brazil Economy, Dec 2025 — PI AgSciences US$150m Brazil target; TEIKKO 22 kg → 3.5 t

PI Q2 FY26 earnings call transcript — PHC run-rate “$10–12 million”

PI Q1 FY27 earnings call transcript — FY25 global biologicals EBITDA loss ~₹120 cr

Plant Health Care — PREtec technology platform

MarketsandMarkets — Nematicides Market 2025–2030

Doriane — Top 10 biologicals companies 2025 (Corteva / Syngenta / UPL scale)

8 Likes

New Businesses: AgChem NCE Pioxaniliprole.

India’s first indigenously discovered insecticide, and the first ISO common name granted to an Indian company (ISO approval May 2024; CAS 2368920-61-8).

What it is. An anthranilic diamide — the same class as FMC’s Rynaxypyr (chlorantraniliprole) and cyantraniliprole. ~2039 patent life.

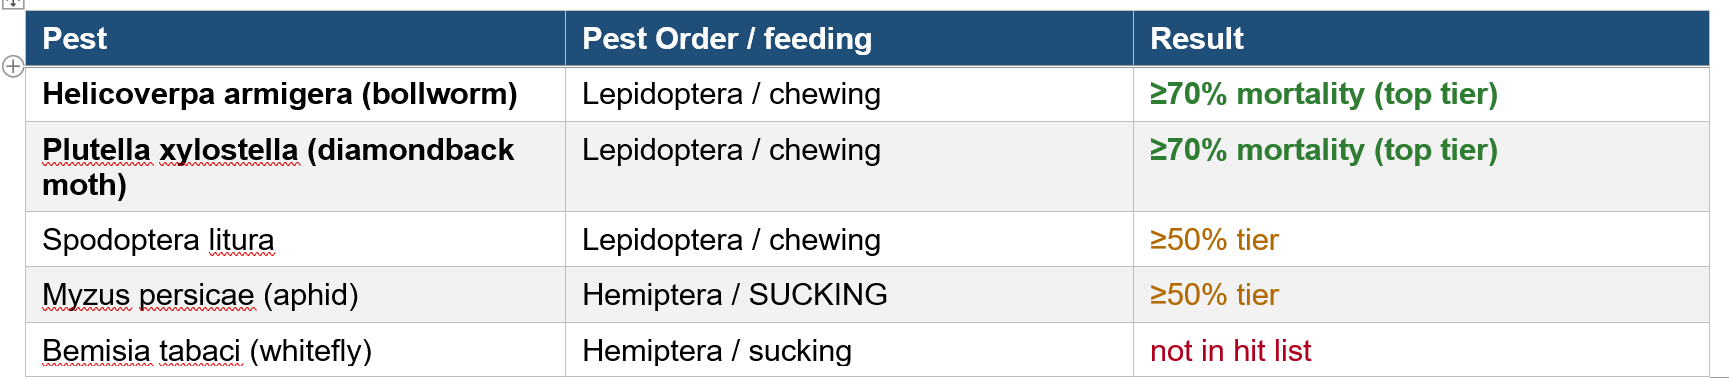
The efficacy data — buried in the granted US patent:

Pioxaniliprole is active in both the chewing and the sucking-pest screens. CTPR is strong on Lepidoptera but weak on sucking pests (0% on aphids at 100 mg/L); cyantraniliprole widened the class to aphids. So on the patent’s own data pioxaniliprole reads as a cyantraniliprole-type broad-spectrum diamide, not a Lepidoptera-only one. The above are very interesting data nos and company has multiple times iterated on the call regarding out licnesing partnerships.

Launch: FY26 AR: “Filed for regulatory registration in India ahead of a planned domestic launch”; the project is “moving toward the second round of kharif trials”. Q1 FY27: “we are hoping within the year we should get the launch for India”, with two further geographies in FY28/FY29. Meaningful volumes look like FY28+; The volume ramp up is a 4 to 5 year process but with pests showing significant resistance to existing diamides and no of applications going up significantly in a crop cycle the resistance to existing diamides is only going to grow.

The pipeline:

Sources

US 12,221,436 B2 — pioxaniliprole composition patent (Compound 99 bioassay tables)

WO2019150220A1 — Novel anthranilamides (Google Patents)

Global Agriculture — ISO approves ‘Pioxaniliprole’ (PI Industries)

PI newsroom — Pioxaniliprole: India’s first discovered molecule for crop protection

Lahm et al., Bioorg. Med. Chem. Lett. 2007 — chlorantraniliprole discovery; 0.01–500 ppm screening protocol

Environmental Clearance SPM-29/2, 17 Sep 2025 — Pyrazole-diamides line incl. TESA (PZA), FLIZ, L8E22; “14 Carboxamide (TTP)”

PI FY2025-26 Integrated Annual Report — “Filed for regulatory registration in India”; second round of kharif trials

PI Q1 FY27 earnings call transcript — analyst asks whether pioxaniliprole is flow-based; question not answered

PI Q4 FY26 earnings call transcript — “₹50 to ₹100 crore of additional spends” on launch

Subhagan et al., J. Trop. Agric. 63(3) — Kerala rice leaf folder CTPR resistance 72x–1,090x; tetraniliprole no cross-resistance

Siddhartha et al., J. Econ. Entomol. 118(5):2545 — I4775M RyR mutation in Leucinodes orbonalis, Tamil Nadu

Kulye et al. (Bayer), Insects 12(8):758 — Indian fall armyworm baseline; CTPR 0.9–6.8x, tetraniliprole max 2.3x

Tamilselvan, Kennedy & Suganthi, Crop Protection 142:105491 — Plutella resistance, Tamil Nadu

Vijayakumari et al., Legume Research 48(4):674 — Maruca vitrata CTPR 3.8–97x; CTPR/flubendiamide r = 0.999

AgroPages — 2024 India pesticide registration watch (CTPR = 8.22% of all registrations)

AgroPages — June 2025 India registration briefs (CTPR ~40 registrations, leads all AIs)

8 Likes

New Businesses: Pharma (PI Health Sciences)

The model: Three transactions in 2023 — Archimica S.p.A. (Italy) for €34.2m (27 Apr 2023), Therachem Research Medilab (US/India) for $50m + $25m earn-out, and Solis Pharmachem — plus Hyderabad. The model: “intermediates out of India, API out of the West” — cost-efficient Indian development and intermediates, with Lodi, Italy as an EU-GMP “safe harbour”. CCO Alessio Piccoli frames it as geopolitical de-risking: “clients can shift volumes, routes, or stages… without requalifying a new CDMO.”

Archimica has been a difficult asset

The collapse was customer-specific: Nostrum Laboratories, “the main buyer of the active ingredient Sucralfate”, entered Chapter 11, costing “a loss on receivables of approximately €2.2 million and an estimated loss on the annual business of Sucralfato of approximately €6 million.” PI **waived a €17.0m shareholder loan into equity, injecting €6.25m cash.
**
What is being built —

Lodi holds FDA, AIFA and KFDA (Korea) approvals24 active US DMFs; OEB4 potent handling; new GMP Kilolab + QC lab; line revamps for Diacerein, Sucralfate, Mianserin, Cytarabine; Mianserin obtained an EDQM CEP (Dec 2024); site on 100% renewable electricity.

Panoli pharma greenfield “launching in 2027”, designed fully automated from the ground up, with 330 kL combined capacity across the network

Peptides and “tides” identified as a significant growth area; TPD/PROTAC discovery offerings in Hyderabad. Candid maturity gap: LIMS “currently in progress.”

“$600M earmarked for future investment”; 60+ customers; 4 commercial NCEs launched — PIHS Apr 2025 deck,

Leadership was rebuilt, not retained: Dr. Ramesh Subramanian (ex-Piramal Pharma Solutions) became Global CEO in Aug 2024; Franco Moro (ex-CEO of FIS and Stevanato) COO; Alessio Piccoli (ex-Aragen) CCO; Simon Haydar (ex-GSK) CSO; Mahavir Prashad (ex-Novartis) CDO. The most interesting hires are in R&D like Dr Lalitha Vijayakrishnan as VP & Head of Discovery Biology a trained immunologist with more than 20 years of industry R&D experience across Ranbaxy, Daiichi Sankyo, Syngene and Eurofins Advinus, with a PhD in immunology and post-doctoral work at Harvard Medical School.

The capabilities being developed:

HPAPI: PI says it can currently handle HPAPIs up to OEB4. The FY25 annual report went one step further and said it was evaluating OEB5, highly potent APIs, peptides, ADCs and large molecules as future capability areas.

Pharma Biologics:

PI’s current Discovery Biology platform explicitly supports monoclonal antibodies, bispecific antibodies, ADCs, engineered biologics, peptides and peptide therapeutics. In Recombinant protein and molecular biology Pi says it can generate crystallography-grade recombinant proteins, and it has capabilities in protein expression and purification, gene cloning, plasmid preparation, stable cell-line generation, prokaryotic and mammalian expression systems. For monoclonal antibodies and engineered antibodies, PI says it has capabilities in antigen-antibody binding assays, SPR/Biacore affinity and kinetic analysis, FACS binding, ELISA specificity. Its Biacore 8K platform supports peptide-protein, protein-protein, antigen-antibody and protein-small-molecule interaction studies. There are furtehr capacities in Bispecific antibodies, Immuno Oncology, Organoids etc.

Financial trajectory (PI pharma segment): FY24 ₹3,149mn → FY25 ₹2,151mn (−32%) with an EBITDA loss of ₹1.8–1.9bn → FY26 +40% YoY (~₹300 cr), after Q1 FY26 +186% and 9M FY26 +50%. Management frames breakeven at ~₹5bn revenue; the CFO guided “a 12 to 18 month period” to EBITDA breakeven (Aug 2025),

Pharma is the least proven leg with a constant churn at top level — a turnaround under construction with a credible new team and real capability investment, but a base business that took a bankruptcy hit and needed fresh equity. The real nos will start in FY27 revenue ramp and after Panoli 2027 start. From a Pi’s standpoint Pharma cannot be just another business they were the pioneers in agchem CSM and would like to be the same in Pharma. The Chemistry capabilities exist, the biological capabilities exist, the assets exist, the manpower exist now it is a case of putting all of this together and scaling it up. Also for Biologics PI today is a pharma biologics discovery CRO, not a biologics manufacturing CDMO. For Lodi, the most recent inspection of any kind was AIFA in February 2024, which led to remediation observations now being addressed under the FY26 capex plan. A new FDA inspection has been pending and can be a dignal for commercial supply for US-destined APIs scales. The entire Pharma build up can be a spectacular success for Pi or too much stuffed too soon.

Sources

Archimica S.p.A. statutory accounts FY Apr24–Mar25 (English translation, hosted by PI)

Archimica S.p.A. statutory accounts FY2023-24 (English translation)

PI Health Sciences Annual Report / Board Report 2023-24

PharmaSource podcast — Alessio Piccoli, CCO, May 2026 (FDA/AIFA/KFDA; India–Italy footprint; peptides)

PI Health Sciences corporate deck, Apr 2025 ($600M; 60+ customers; OEB4)

PI Health Sciences corporate film, Apr 2026 — Panoli 2027, 330 kL

• PI Health Sciences Biology services
PI Health Sciences Peptide Synthesis

PI Health Sciences leadership team

Archimica — Mianserin CEP certified, Dec 2024

Indian Pharma Post — PI announces twin acquisitions into Pharma API & CDMO space (2023)

PI Q1 FY26 earnings call transcript, 13 Aug 2025 — pharma +186%; breakeven “12 to 18 month period”

PL Capital, 26 Sep 2025 — pharma segment revenue and EBITDA loss

8 Likes

New Businesses: Electronic & Performance Chemicals

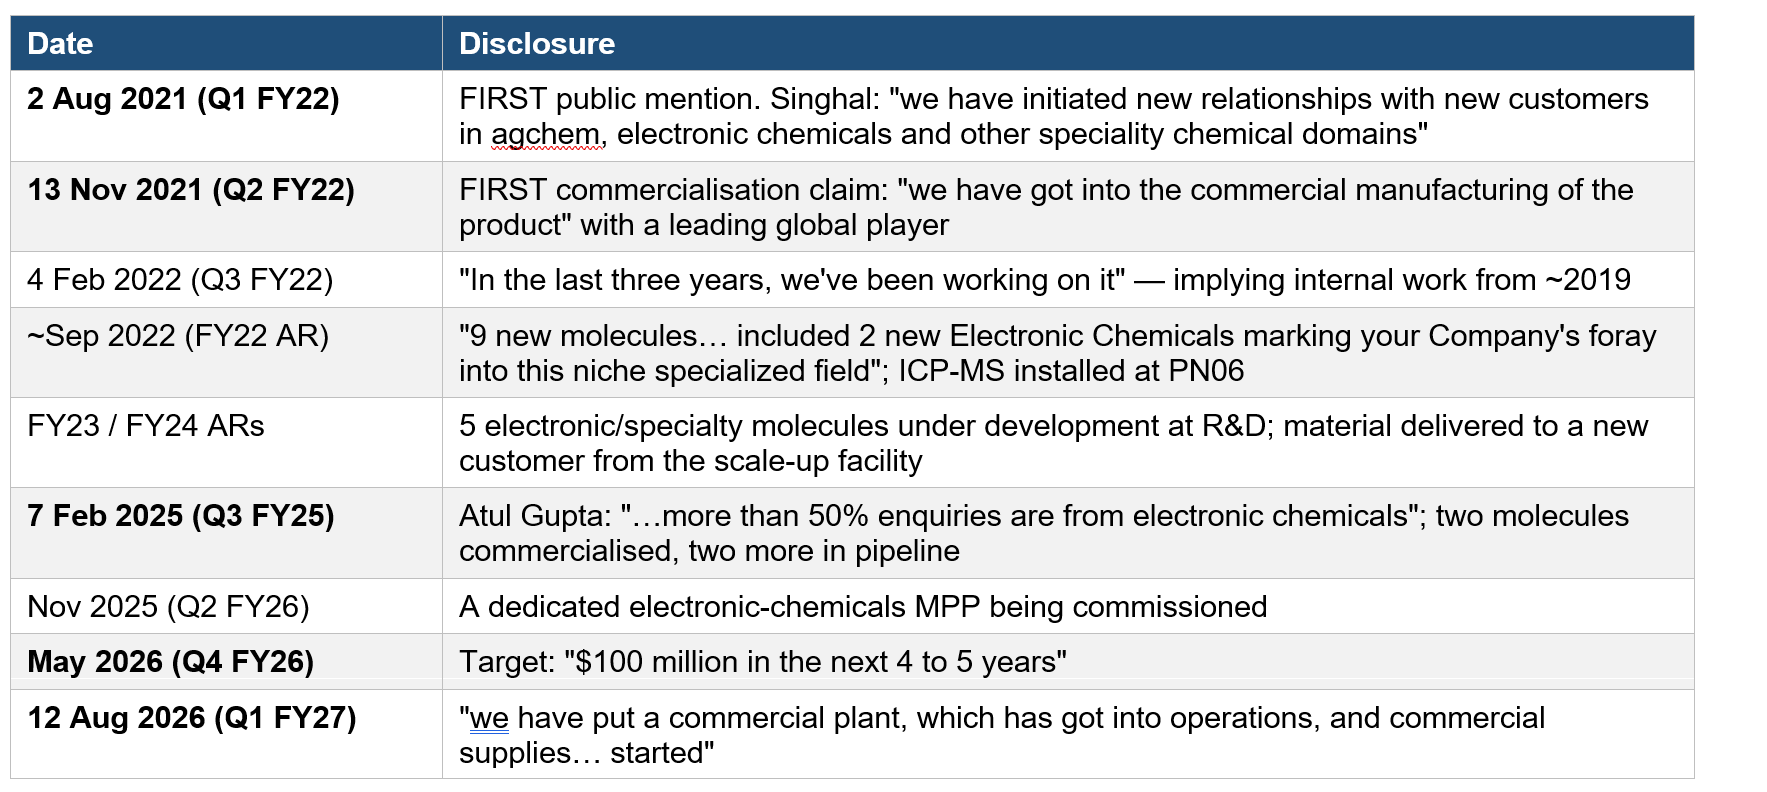
The timelines:

The environmental filings and the possible products:

The Sep-2025 and Jan-2026 Jambusar clearances create an entirely new “Electronic Chemicals” group, 0 → 1,000 MTPA, by cutting Performance Chemicals 13,000 → 10,000 and raising Pyrazoles 5,500 → 7,000 — i.e. a product-mix change at constant total capacity (43,240 / 44,240 MTPA). The product codes are interesting:

The fluorochemistry leg — HFPO and the possible Daikin link

HFPO is named in the environmental clearance. The “Performance Chemicals” group lists, , “…6-FDA/NEC, 4-FPH/2,4-DFA, AND/ HFPO/ DFBA, T-BUCON/TiC3 etc.” Identity as hexafluoropropylene oxide is probable rather than spelled out — but its line-mates (6-FDA, BPADA) are fluorinated polyimide monomers, which fits. Daikin’s product brand appears in the filings. The “Fluoro Speciality” group lists “Diakin-1 / DAISAVE SS-110 / TSS-1, Diakin-2 / TSS-4, Diakin-3 / TSS-5”, and the Specialty group lists “HFE-356 / DAISAVE SS-54”. DAISAVE is Daikin Industries’ brand for perfluoro and hydrofluoroether solvents (used in data-centre immersion cooling). A Government of India filing therefore places Daikin-branded product codes inside PI’s cleared capacity. On LinkedIn: “Commissioning and stabilization hexa fluoro propylene oxide plant and its down stream.”

The counterweight, from the ARs: four years after the “foray”, the annual reports still describe scale-up-facility deliveries, not a dedicated commercial plant, and no electronic-chemicals plant is named in Manufactured Capital in any year. The Q1 FY27 statement that a commercial plant is now running is the first clear indication of commercialisation. Also nothing should be taken as given in this segment as electronic chemicals require PPB level purity.

Sources for this section

Environmental Clearance, Jambusar SPM-29/2, 17 Sep 2025 — Electronic Chemicals 0 → 1,000 MTPA; JSR/adamantane codes; “AND/HFPO/DFBA”; DAISAVE entries

Environmental Clearance, Jambusar SPM-28 + SPM-29/1, 30 Jan 2026

Jambusar Unit-II Pre-Feasibility Report, Jan 2017 — 13,000 MTPA Performance Chemicals incl. “Negolyte”; 2,000 MTPA Fluorospeciality

Panoli Plot 237 Pre-Feasibility Report (SEIAA) — DEAM / Favipiravir intermediate

PI Industries — Electronic Chemicals (CSM) product scope and dedicated plant description

PI Q1 FY22 earnings call transcript, 2 Aug 2021 — first electronic-chemicals mention

PI Q2 FY22 earnings call transcript, 13 Nov 2021 — first commercialisation claim

PI Annual Report FY2021-22 — “2 new Electronic Chemicals marking your Company’s foray”

PI Q3 FY25 earnings call transcript, 7 Feb 2025 — “>50% enquiries are from electronic chemicals”

PI Q4 FY26 earnings call transcript, May 2026 — “$100 million in the next 4 to 5 years”

PI Q1 FY27 earnings call transcript, 12 Aug 2026 — commercial plant in operation, supplies started

PI Annual Report FY2022-23 — “high pressure oxidation involving toxic fluorinated compound”; vapour-phase fluorination (TFE, ETFA)

PI Integrated Annual Report FY2023-24 — HAZOP for high-pressure fluorinated oxidation

Daikin Chemicals — DAISAVE product brand (perfluoro / immersion-cooling fluids)

Nishant Meghapara, Production Executive, PI Industries (Panoli) — LinkedIn: MPP running 4,4-BPoDA, 4,4-BPATA, 3,3-BPATA

AgroPages — Mayank Singhal interview, Nov 2023: vapour-phase fluorination, azide chemistry, high-pressure oxidation of toxic fluorinated compounds

8 Likes

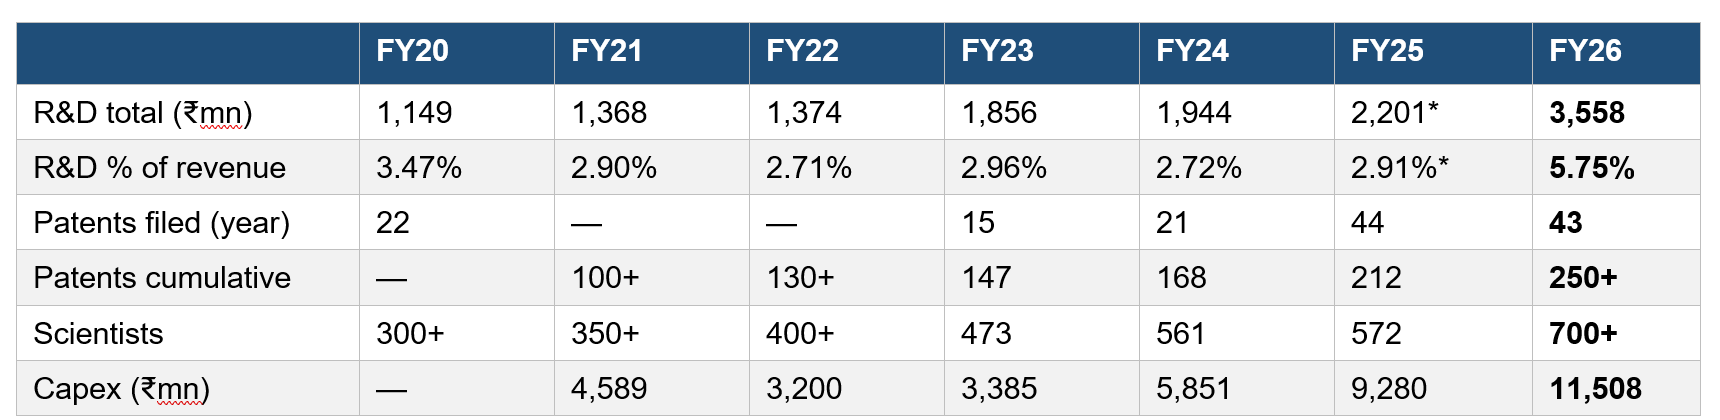
R&D expenses & Patents:

6 Likes

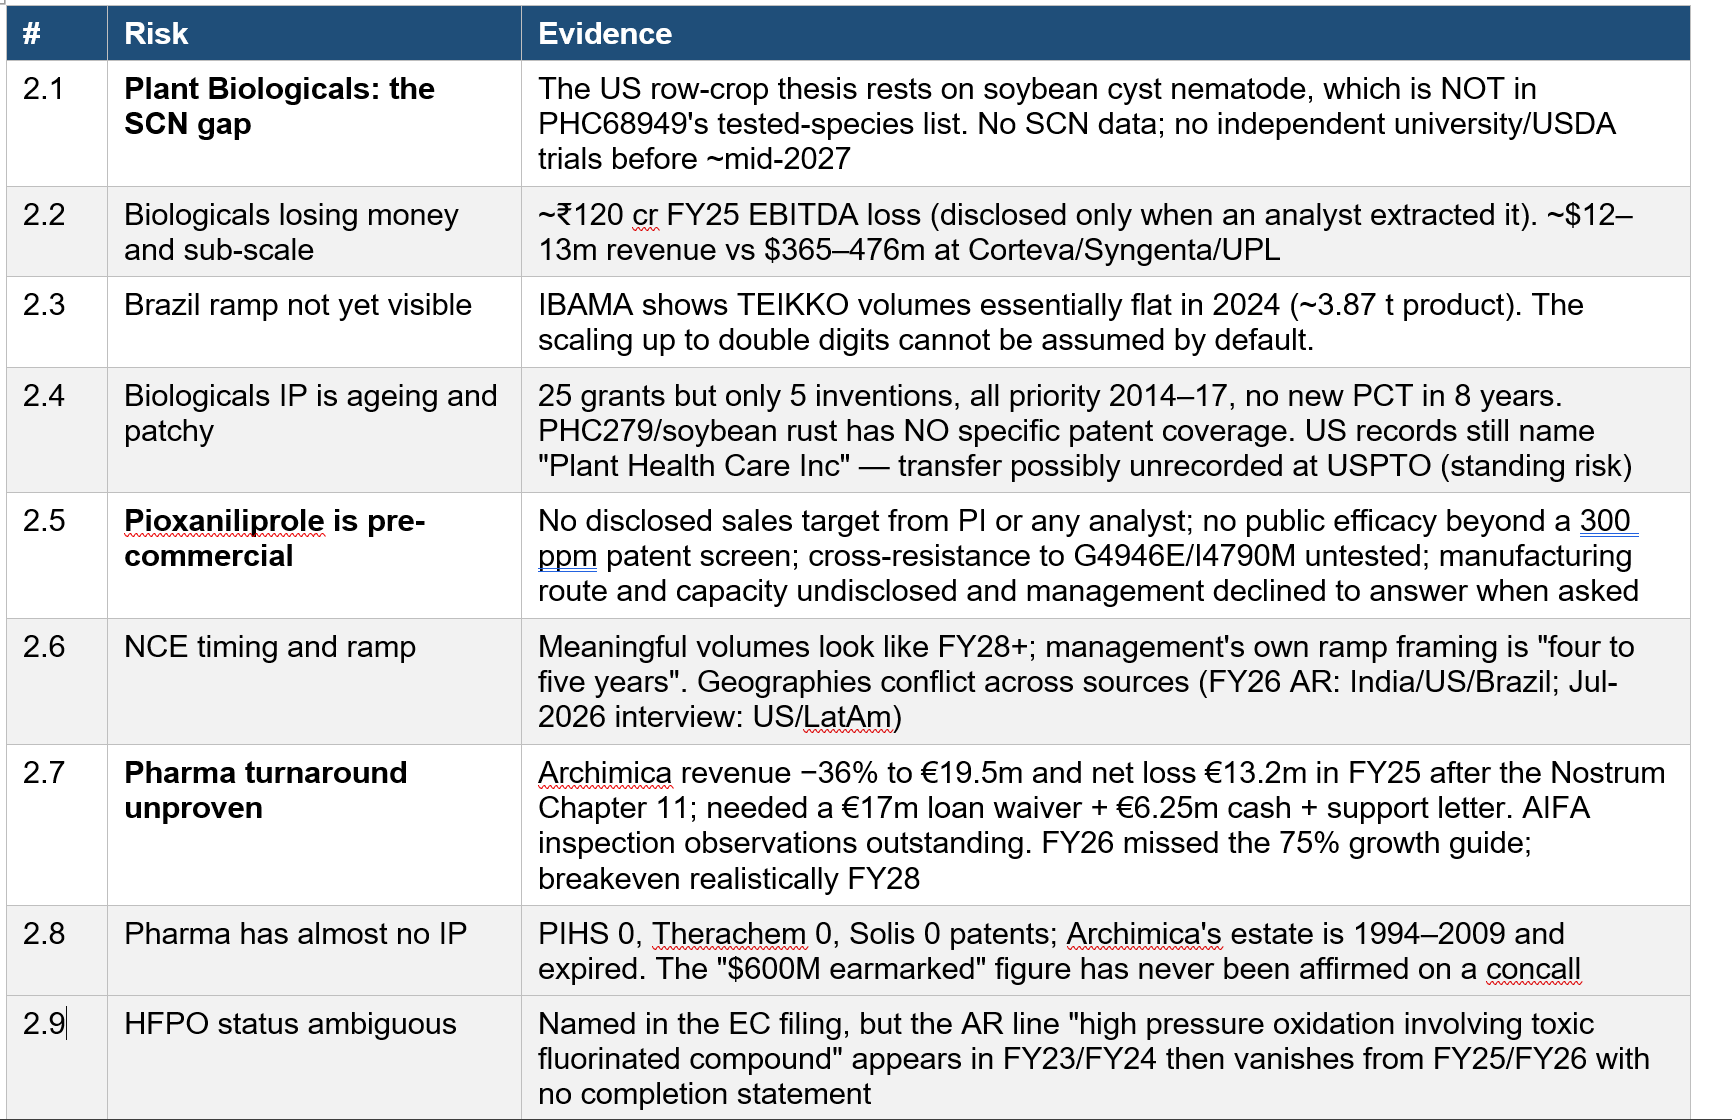
Risks:

  1. Concentration and the core molecule:

  1. New businesses — biologicals, NCE, pharma, electronics:

A material part of this note is inference from public documents that PI has never confirmed. PI files product lists under internal codenames, declines product-level questions on calls citing confidentiality agreements, and has published no code legend for anything added after 2017. Much of what follows was reconstructed by cross-referencing environmental clearances, SEZ approvals, patents, partner filings, regulator databases and LinkedIn — a method that is legitimate but fallible.

Specifically NOT confirmed by PI: (i) that the FY26 flow plant runs pyroxasulfone; (ii) that “HFPO” in the EC filing is hexafluoropropylene oxide; (iii) that the DAISAVE entries mean a Daikin supply relationship; (iv) that the JSR- and DIC-prefixed codes mean those companies are customers; (v) that ZEN-NOH is the dicloromezotiaz counterparty; (vi) where or how pioxaniliprole will be manufactured; (vii) any peak-sales figure for pioxaniliprole or TEIKKO.

10 Likes

What I would watch next:

Kumiai Q3 FY26 (early Sep 2026) — does H2 Axeev pricing deteriorate as guided?

IBAMA 2025 commercialisation release (~late 2026) — first clean independent read on TEIKKO’s post-launch ramp

India CIB&RC dossier for pioxaniliprole — first GLP field-efficacy and tox data; India launch guided within FY27

Independent US university SCN trials on PHC68949 (~mid-2027) — the single highest-value data point for the biologicals thesis

Electronic chemicals revenue disclosure — a $100m/4–5yr target with no segment break-out yet

Panoli pharma greenfield start-up (2027) and the pharma breakeven glide path

8 Likes

Disclosure: I hold PI Industries. This is not investment advice and my views are biased. Everything above is sourced from public documents, listed under each section. I have inferred a lot from public documents, EC filings, linkedin etc - notably the flow plant/pyroxasulfone link, the ZEN-NOH counterparty for dicloromezotiaz, Daikin relationships, the identity of HFPO in the EC filing, the unidentified product codes etc. I have taken help of agentic AI tools and tried to verify the information but that may be incorrect. Corrections very welcome.

11 Likes

Final thoughts: Pi is seeding multiple businesses and all of them are niche/differentiated and scalable. These businesses will have significantly higher margin profile at scale. Pi reports strong margin profile in the range of 25% to 30% despite significant R&D expenses and all of these businesses making significant losses, strip off these losses and the core business itself looks very different. The Pyroxa generic threat is real but seems overstated. The transition from a high dependency on Pyroxa to these newer businesses is the what will shape Pi and market perception.

Thanks @Sanjay_Kumar_E , @YachnaBhatia and @spatel for their help in unravelling Pi.

31 Likes

A few additions from digging through the EC filings, management commentary and Kumiai’s own disclosures.

  1. Non-pyroxasulfone CSM growth could be at a trough

New products held at 16-18% of CSM revenue in the quarter and 18% of AgChem export revenue in FY26; five molecules were commercialised in FY26 and three more in Q1 FY27; the order book has been flat at roughly US$1.2bn for three quarters, against 90+ molecules in the active pipeline with over 60% at advanced development stages. The new molecule book is growing but masked by a single product and weighed down by a weak agrochem cycle.

The customer side supports a cyclical rather than a structural read. BASF’s fluxapyroxad is growing and could double over three to four years. FMC has held its fluindapyr step-up. Isoflucypram was meaningful in FY26.

Set against that, several names PI is permissioned for at Panoli look dormant or well below what the customer’s own guidance implies: dichlobentiazox, fenoxasulfone, tetraniliprole and the spirotetramat intermediate, alongside newer entries still ramping or in qualification including isoflucypram, mefentrifluconazole and pyridachlometyl.

On a normalised agrochemical cycle, this cohort can come back together and drive growth in the base CSM business.

  1. MTP backward integration, and the gross margin risk

Management has guided long-term gross margin at 50-52% and reiterated it repeatedly through FY26. Reported gross margin was 57.8% in FY26, with quarters running 58-59%. The usual explanation is mix, but pharma, global biologicals and electronic chemicals together were only about ~5-6% of revenue in FY26. Even at very high segment margins, businesses that small move the group blend by well under 100bps against roughly 790bps of expansion.

The more likely explanation is that PI internalised the fluorinated starting material for pyroxasulfone. The Panoli Site 2 environmental clearance granted in October 2023 names MTP explicitly in the permissioned product list, so the capability is on record. If the arrangement previously involved conversion of customer-supplied material, taking that step in-house is exactly the kind of change that produces a step in gross margin with no change in price.

With realisations in the large molecule falling and management still holding 50-52% rather than raising it, there is 300-400bps of gross margin at risk in the base business.

  1. PI Health Sciences: leadership and the GMP gap

Dr Ramesh Subramanian was Global CEO for two years to August 2026. He was on every quarterly call through Q4 FY26 and absent from Q1 FY27. Alessio Piccoli, the Chief Commercial Officer, has also gone. The leadership page lists four names on their website.

Also, PIHS has no commercial GMP API plant in India. Lodi in Italy is the only site in the platform capable of commercial GMP supply into regulated markets; the Indian sites are development-GMP, fine for clinical material but not commercial API. So Indian GMP work has to go through a third party.

9 Likes

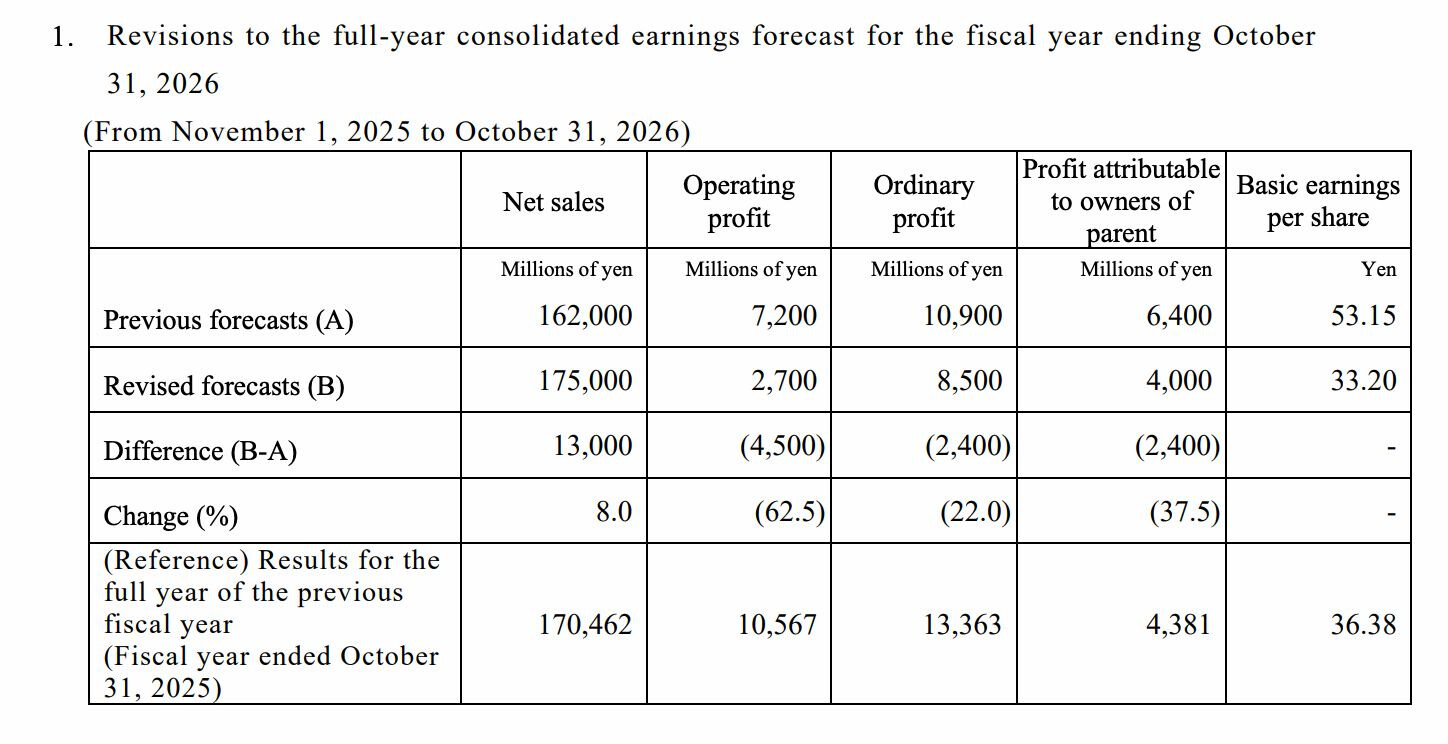
The following is Kumiai’s press release:

This is a geniune concern. There are few interesting things to point:
a) Pi is a contract manufacturer and time and again the mgmt has said they work on a cost+ model. Profitability of Kumiai is a function of how Kumiai sells it to the US distributors. Profitability of Pi depends upon how much volume is lifted and at what price.
b) Sales going up in a price competitive scenario would imply even more significant volume gains for Pi.
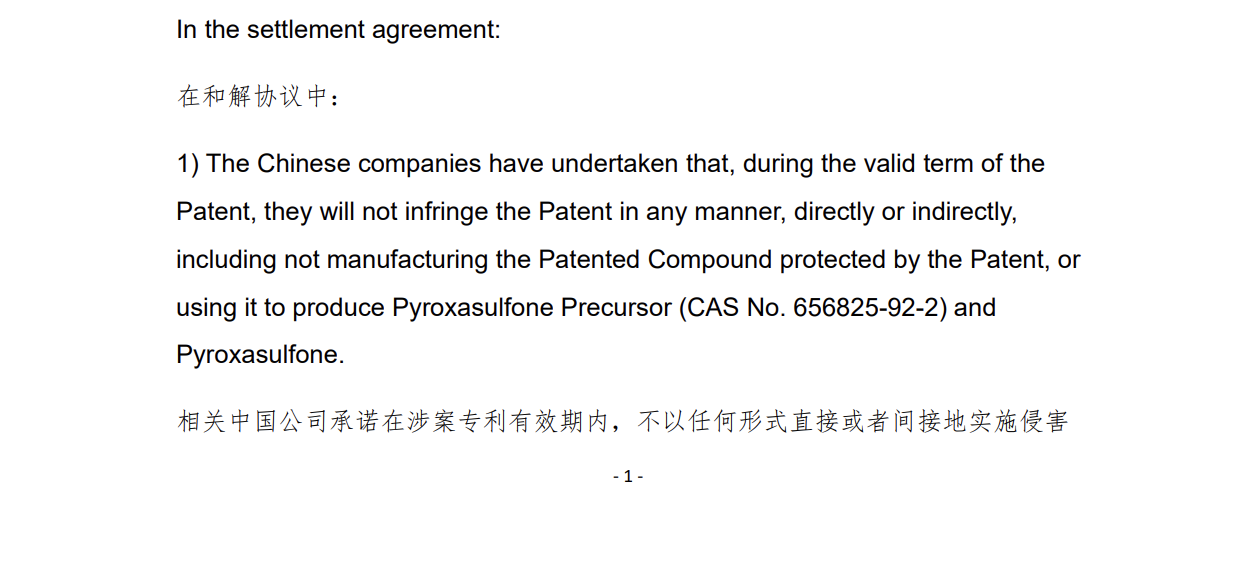
c) From what I can recall Pi has confirmed in its conference calls that it is the lowest cost producer of Pyroxa. With flow chemistry coming in pricing will go down further. Also Kumiai has filed process patent violations against most Chinese manufacturers and the Chinese courts have asked Chinese manufacturers to stop manufacturing, destroy inventory, take down the existing plants and settle with Kumiai. This also reduces the risk of Kumiai shifting to any other manufacturer. The reason Chinese manufacturers were using patented process from Kumiai was because it had much better yields. The process patent expires sometime in 2027. The formulations sold by Kumiai partners go much longer in US, the key market.

Settlement with Anhui:

There is no doubt that Kumiai reducing prices may have a direct or indirect bearing on Pi but as long as sales growth continues that should be managable.

14 Likes