Laxmi Dental is a one-stop shop for everything a dentist might need in India and around the world. Started in 2004, Laxmi Dental exports dental goods and full-service dental company. They handle everything from manufacturing dental chairs and instruments to operating labs that specialize in the latest advancements like digital dentistry, clear aligners, pediatric care, and lab automation. Today, they serve over 22,000 dental clinics and dentists across more than 300 Indian cities and 95+ countries.
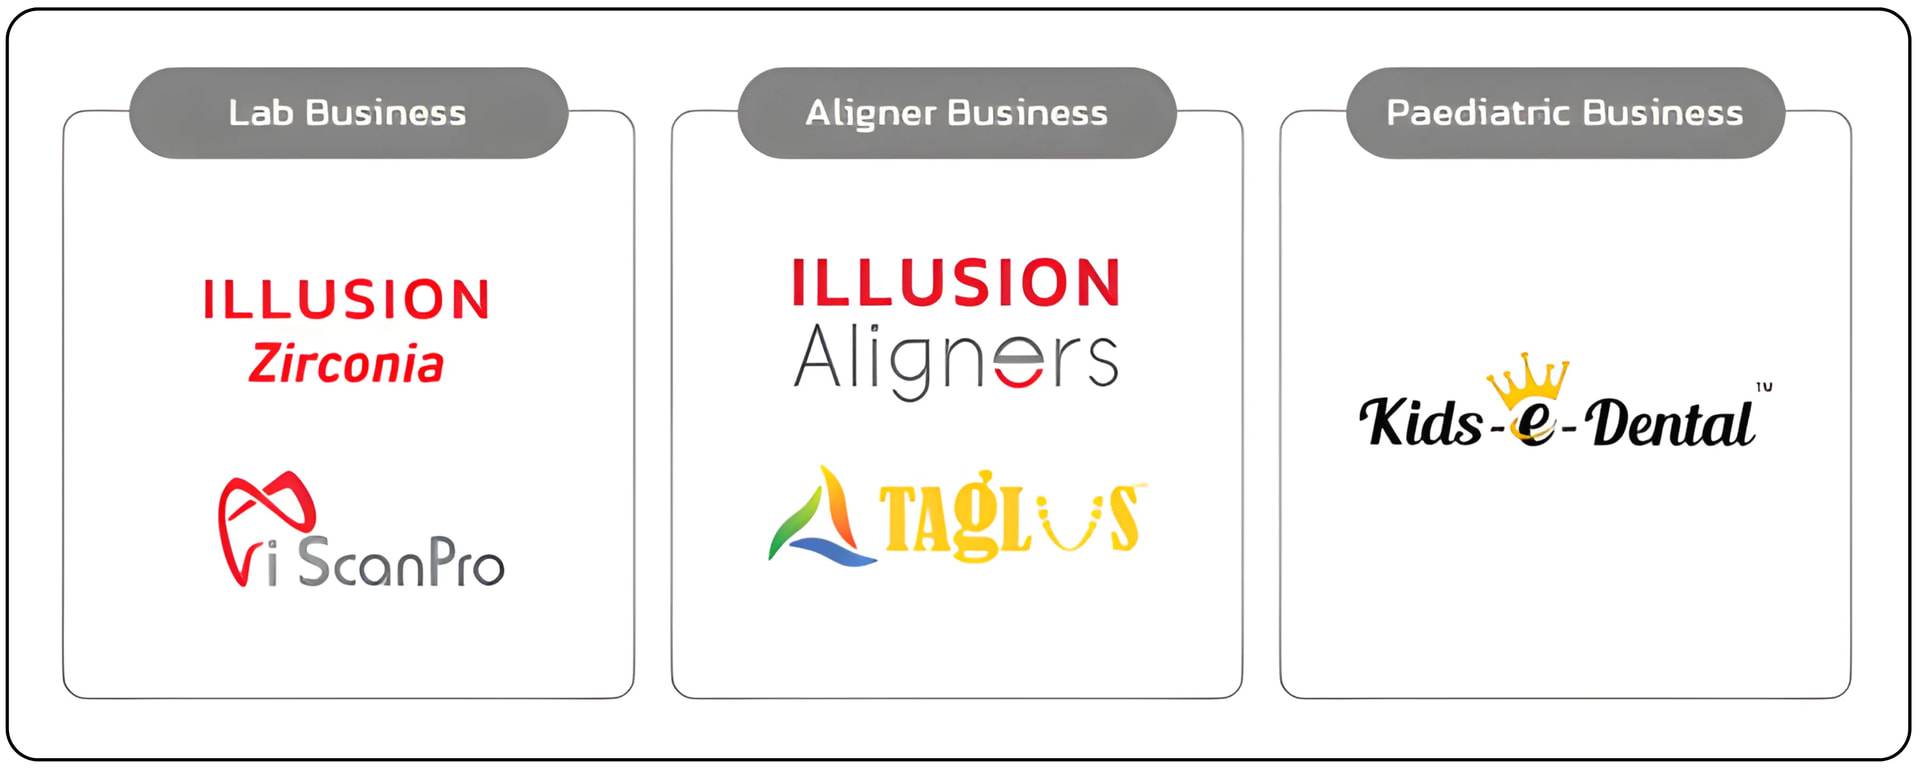
Laboratory offerings (62.8% of revenue)
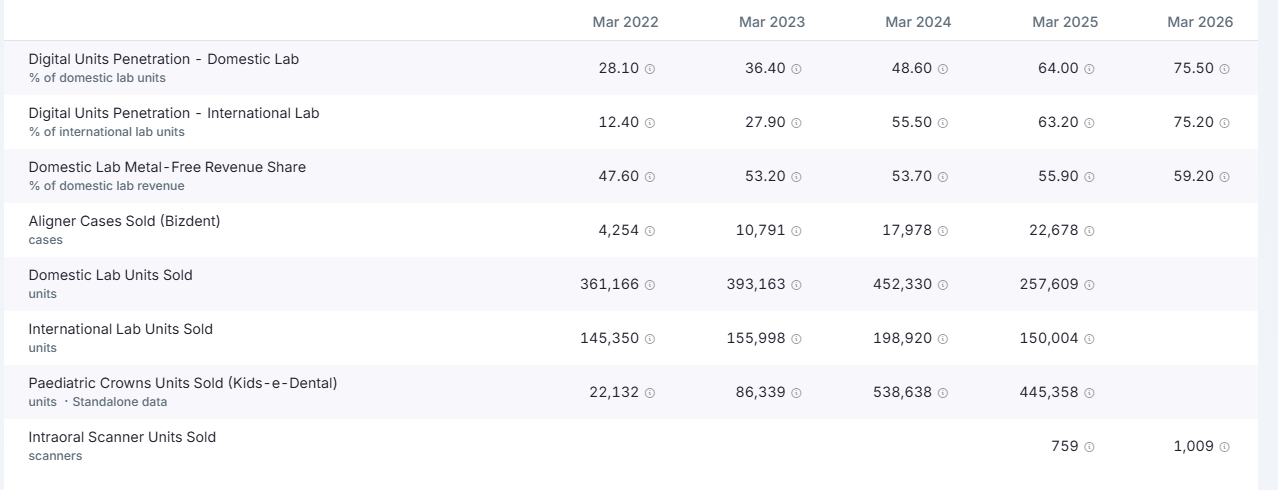
Contributing ₹197 Cr, this segment focuses on creating fully customized dental prosthetics, including crowns, bridges, and restorative solutions. Operating through dual markets, domestic (36% of total revenue) and exports (25% of total revenue). In recent years, it has successfully shifted toward premium metal-free products. For example, zirconia-based crowns now represent 55% of domestic laboratory business, , driving improved margins through the premium “Illusion Zirconia” brand.
Aligner solutions (20% of revenue) - Aligner market penetration
Generating ₹77 Cr, this fast-growing segment operates through “Illusion Aligners,” the first Indian clear aligner with US FDA 510(k) clearance. The segment combines
Bizdent Devices Focuses on the final product, delivering 100% customized, clear aligners to dentists based on patient-specific prescriptions.
Vedia Solutions handles advanced manufacturing and backward integration, producing essential components such as thermoforming sheets, 3D printing resins, and dental-grade machinery.. With India’s malocclusion prevalence at 75% but only 0.1% orthodontic treatment adoption versus 3% in the US, the segment projects 39% CAGR growth from FY25E-28E.
Kids-e-Dental (11.1% of revenue)
Through its 60% stake in Kids-e-Dental LLP, this segment contributes ₹26.27 Cr, offering a range of pediatric dental solutions, including pre-formed pediatric crowns, Silver Diamine Fluoride, space maintainers, and fissure sealants. The global pediatric dental crowns market is expected to reach $3.5 billion by 2030 with a 23% CAGR, supported by India’s young demographic profile.
Other business (6.06% of revenue)
This segment contributes ₹9Cr and includes dental instruments, consumables, and emerging digital solutions, providing diversification and comprehensive customer solutions.
Financial performance
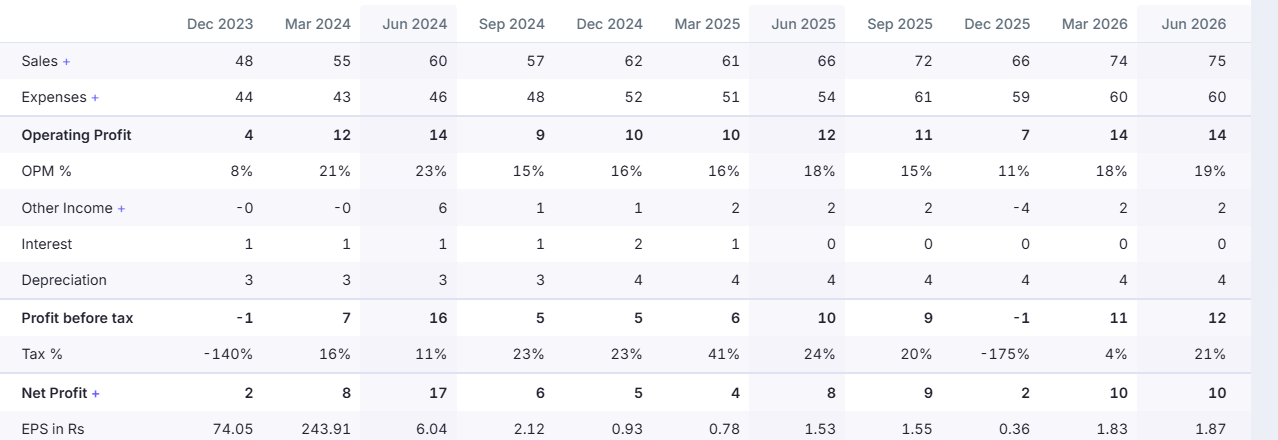
| Fiscal Year | Revenue (Crores) | EBITDA (Crores) | Profit Margin (%) | Net Income (Crores) |
|---|---|---|---|---|
| FY22 | 136.84 | 5.42 | 3.96% | -18.68 |
| FY23 | 161.63 | 8.96 | 5.54% | -4.16 |
| FY24 | 193.56 | 23.79 | 12.29% | 25.23 |
| FY25 | 239.11 | 41.87 | 17.51% | 31.83 |
| FY26 | 287.00 | 43.00 | 16% | 29 |
Latest Concall summary
They expect to keep growing at a healthy pace. Their own target is 15-20% revenue growth and 18-20% profit margin (EBITDA) going forward.
They think profits will get better as one-time costs fade away. Last year (FY26) had some extra costs eating into profits, like a new labor law, US tariffs, and employee stock costs. Management says most of that pain is now behind them or shrinking, so profits should look cleaner going forward.
Their main growth bet is on scanners. They’ve been placing a lot of dental scanners with dentists (aiming for 800-1,000 more this year). The idea is simple: once a dentist has one of these scanners, they end up sending a lot more business (lab work, aligners) to the company over time. It just takes about 6 months to 1.5 years for that extra business to show up.
They’re building their own facility instead of renting. Right now they rent two separate buildings and pay about ₹2 crore a year in rent. They’re buying land to build one big facility (3x bigger) instead, which should save money and run more smoothly.
They just hired a new boss for their US business who has 11 years of experience in dental, and they expect this to start paying off in a couple of quarters.
Tariffs aren’t scaring them. US import tariffs dropped from a painful 50% down to 10%, and management says that’s manageable, not a dealbreaker.
They have plenty of cash (₹99 crore) and no debt, so they’re open to buying other companies if the right opportunity comes along
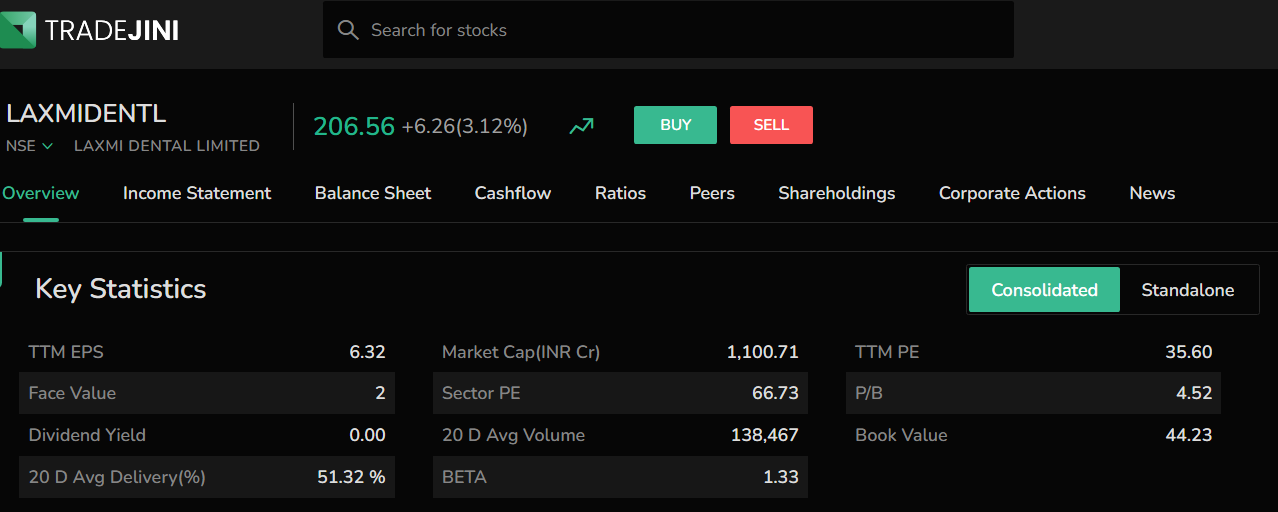
Laxmi Dental trades at a P/E of 35.6x, with the sector P/E at 66.7x, the stock is trading at a significant discount to the sector, leaving room for potential re-rating if earnings growth sustains.
Promoters of Laxmi Dental
- Rajesh Vrajlal Khakhar (Chairman) — founded the business in 2004 as Laxmi Dental Export Pvt Ltd and has been director since inception. Under his watch the company grew into India’s only end-to-end integrated dental products company, roughly 5x larger than the third-largest domestic player.
- Sameer Kamlesh Merchant (Managing Director) — co-promoter recognized alongside Khakhar in the same Forbes 2021 feature; continues in an operating MD role and has been actively adding to his stake on the open market.
Negative news check
NSE fined Laxmi Dental ₹2.07 lakh for a 35-day delay in SEBI compliance (Reg. 23(9) of LODR) for the quarter ended September 2025, which the board attributed to administrative oversight during the Company Secretary’s maternity leave, after which they brought in a new Company Secretary to tighten compliance.
| Metric | Laxmi Dental Ltd | Prevest Denpro Ltd | Vasa Denticity Ltd |
|---|---|---|---|
| Market Cap (₹ Cr) | 1,102 | 458 | 689 |
| Current Price (₹) | 200 | 381 | 397 |
| OPM (%) | 16 | 35.7 | 4.42 |
| Stock P/E | 31.7 | 20.3 | 56.9 |
| Book Value (₹) | 44.3 | 105 | 101 |
| Dividend Yield (%) | 0 | 0.26 | 0 |
| ROCE (%) | 14.9 | 24.7 | 9.21 |
| ROE (%) | 14.8 | 18.5 | 7.02 |
| EPS (₹) | 5.62 | 18.8 | 6.98 |
| Sales Growth – 3 Years (%) | 19.8 | 12.9 | 31 |
| Sales Growth – 5 Years (%) | 24.7 | 20.3 | 47.2 |
| PEG Ratio | 0.26 | 1.86 | 4.6 |
| Price / Book Value | 4.53 | 3.64 | 3.94 |
| Enterprise Value (₹ Cr) | 1,106 | 385 | 685 |
| High / Low (₹) | 377 / 156 | 622 / 318 | 636 / 322 |
Based purely on these numbers:
-
Prevest Denpro : looks strongest on profitability and valuation — highest ROCE, ROE and OPM, while having the lowest P/E.
-
Laxmi Dental : has the most attractive PEG ratio (0.26) and reasonably good growth/profitability, but its P/E is higher than Prevest.
-
Vasa Denticity: has by far the strongest 3-year and 5-year sales growth, but the market is already assigning it a very high 56.9 P/E and 4.6 PEG, while ROCE/ROE and OPM are comparatively weak.
-
All three stocks are substantially below their previous highs, which means valuation compression has already occurred, but that alone doesn’t establish that they are cheap.
Disclaimer: I hold fewer than 150 shares of Laxmi Dental Ltd. This is not a stock recommendation or investment advice. I am not a SEBI-registered Research Analyst or Investment Adviser. The information and views expressed are for educational and informational purposes only. Please conduct your own research and consult a qualified financial professional before making any investment decision.