
me too if possible because there will be valuable insights from company.
Great development for specialized wagon business (in automobile segment) →
Railways has introduced a reform allowing special wagon designs while giving flexibility to the industry. Manufacturers can now design wagons based on specific origin-destination routes with high-capacity.
https://www.pib.gov.in/PressReleasePage.aspx?PRID=2244597®=20&lang=1
10 Likes
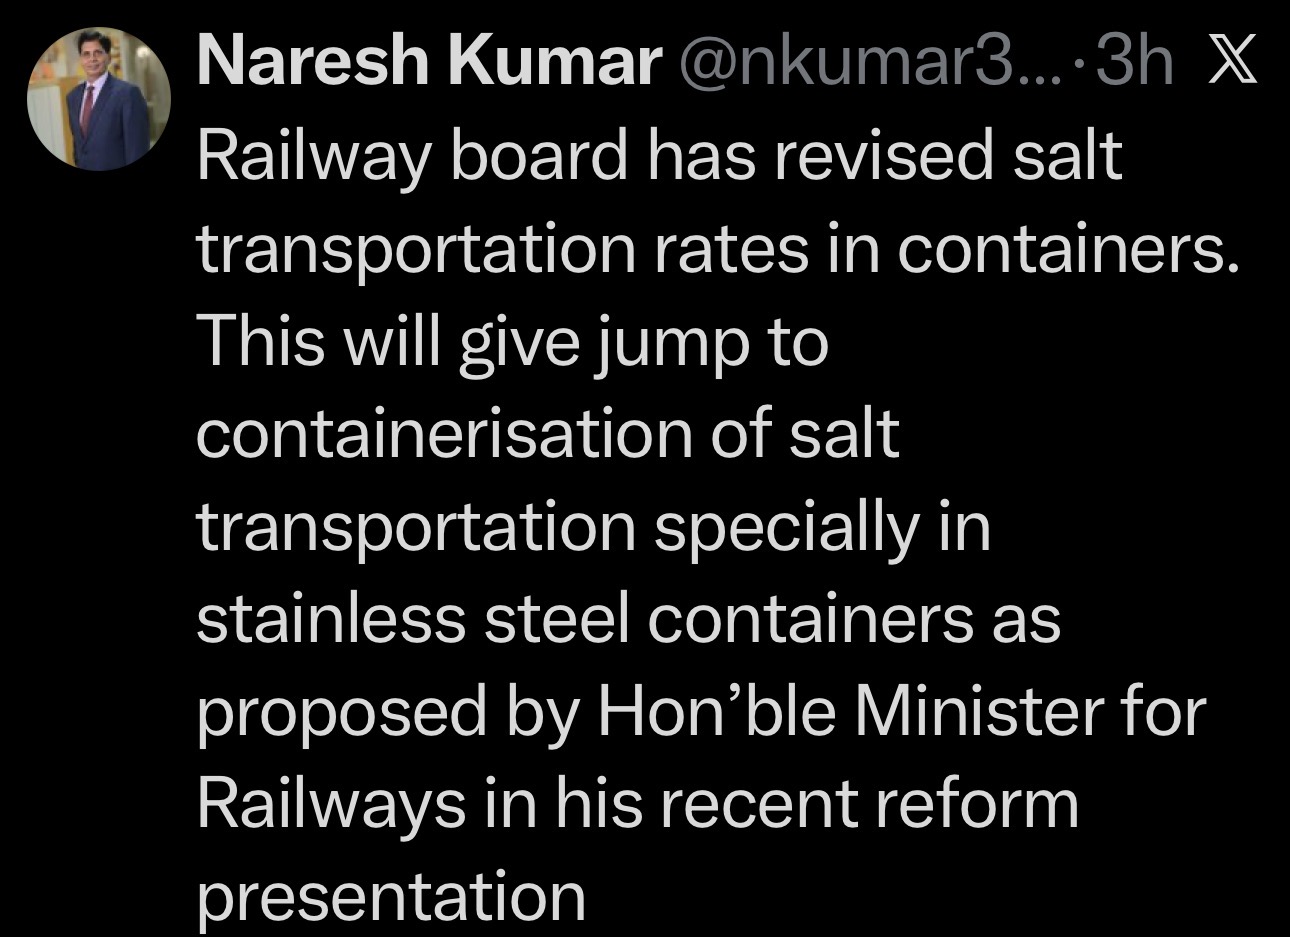
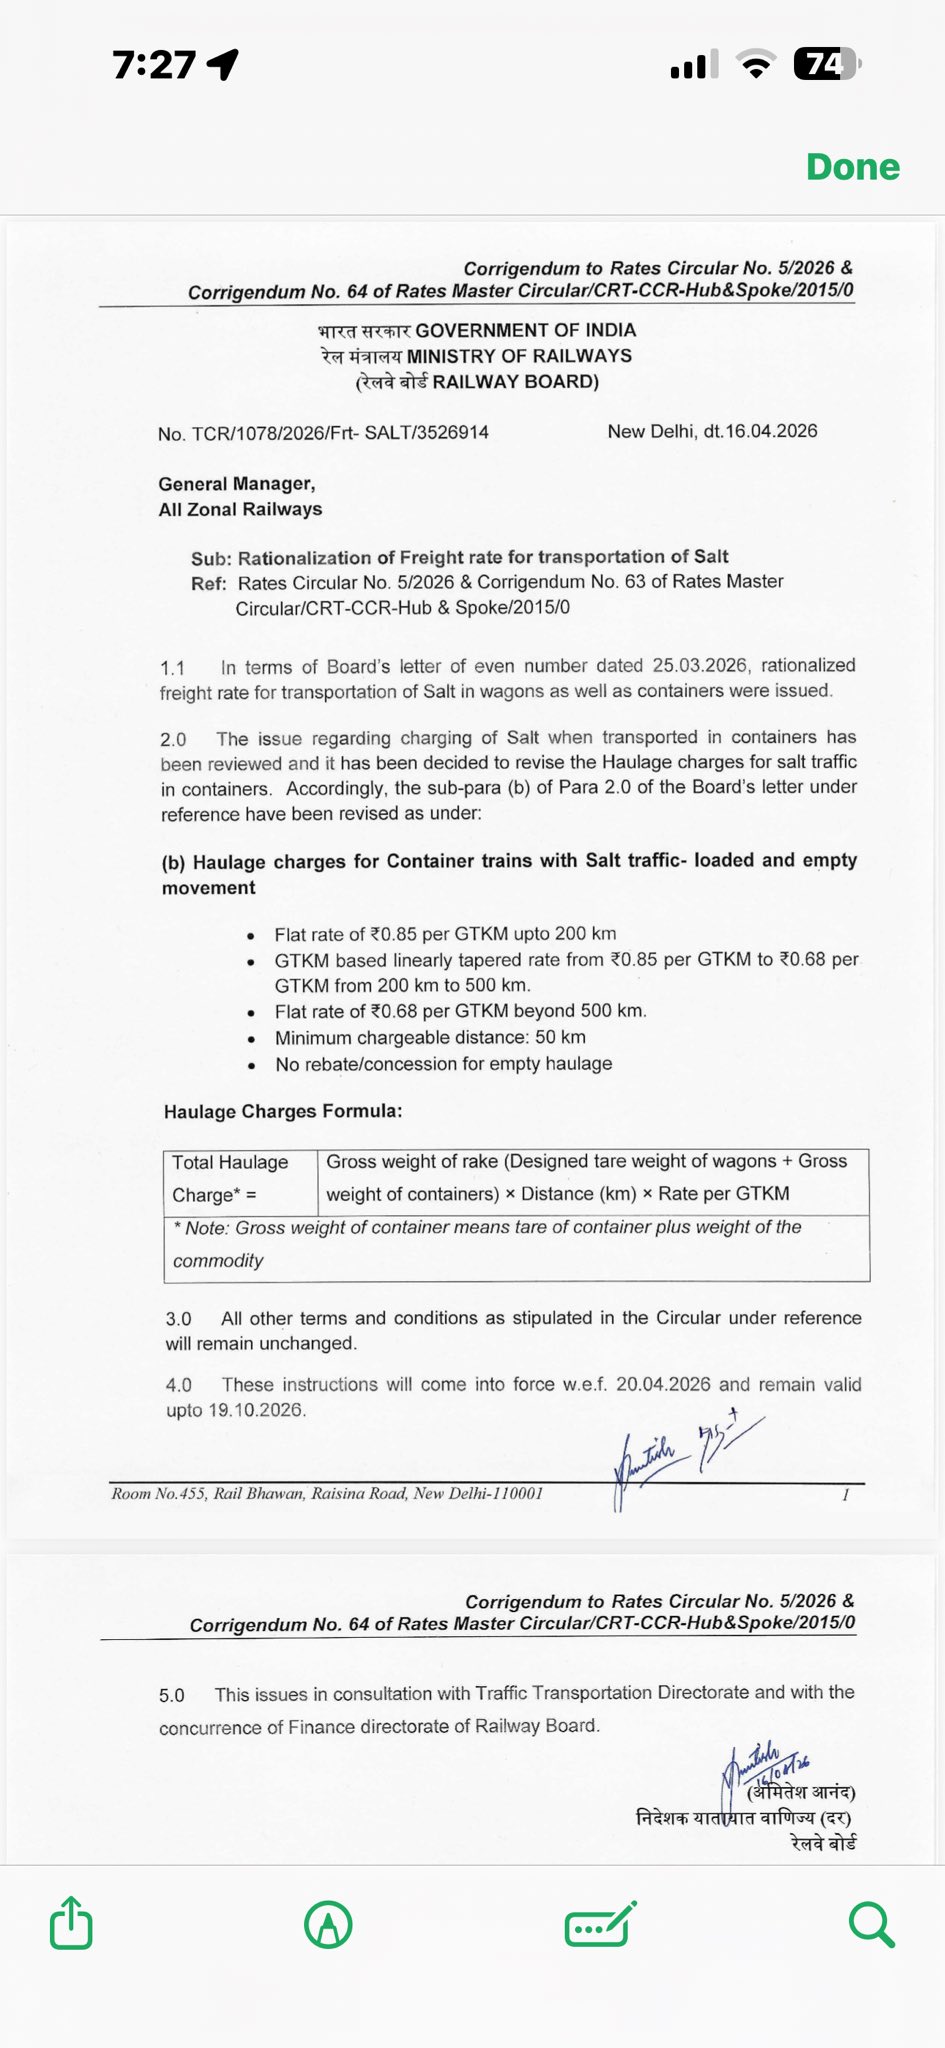
Has the rates been hiked or lowered? If lowered will it not affect bottomline of Kalyani? Or volumes will increase to compensate ?
As per my understanding, Rates have been decreased for transporters not for Kalyani.. as a result of which transportation through Containers will increase and that will benifit kalyani by receiving more Container manufacturing orders.
Correct me if I am wrong
3 Likes
Yeah I also think so…it will boost Kalyani’s topline
1 Like
Well that was fast.
Rs 10,350 Crore Scheme Nears Approval:
6 Likes
Is Adani Enterprises also in the container manufacturing? If yes, small companies like Kalyani Cast Tech will get only a small pie.
1 Like
Big players will come into this space for sure. But KCT being the only pure play in this space and good promoter pedigree will benefit the most. I do not see the point of investing in Adani or JSW if I wish to ride the container manufacturing business. Big players like Adani are better poised for container leasing business which requires deep pocket and high margins.
1 Like
Any idea on the H2 results? They haven’t posted any order wins. Is it going to be flattish or muted?
The opportunity from PLI is huge if you compare it with the market cap, even if able to catch a small portion . But giving a percentage would be imprudent as it adds more bias. However, I am able to see a direction in which the company is progressing.
Lloyd’s certification for corner castings is a barrier no peer currently has. Kalyani Cast Tech is one of the first movers, which gives them some advantage.
Another moat they have is the patents they hold and the culture of innovation, although this could stem from the promoter — which makes it both a moat and a risk.
Be it wagons, specialized containers, or ISO containers, each carries an independent probability of success. Any single outcome turning favourable is sufficient to re-rate the story.
The key risks I foresee, based on discussions with a friend, are that government policies—although favourable in the short to medium term—could change, especially with the general election coming up in 2029(although seemingly distant, I was unable to ignore it). Execution is also a major risk, along with the possibility of leverage or dilution.
Invested - probably biased
5 Likes
How much topline do you expect the Comany to post by 2029-2030…Any estimate?Also will they enter ISO segment after the govt scheme?
1 Like
This has been discussed earlier in the thread—RocketMan has already shared a detailed view on both topline and the ISO segment.
4 Likes
Used a few sources to gather more details.
Disclaimer: This is based largely on market chatter and informal sources. Timelines and facts may vary, so please take this with a pinch of salt.
While the MoU for BCSL was signed on February 3, 2026, the actual “rolling out” of orders is tied to the opening of the CMAS Unified Portal, which is scheduled for July 2026.
- Pilot Phase (May–June 2026): The Ministry of Ports, Shipping and Waterways (MoPSW) is expected to place “Letters of Intent” for a small batch of pilot containers to test the production lines of early-movers.
- Bulk Order Cycle (Q2 FY 2026-27): Once the CMAS portal opens in July, BCSL and CONCOR will begin placing the formal, subsidy-backed orders. These orders will be part of the initial 100,000 TEU target (not verified) for the current financial year.
- The government has officially committed to ordering 15 domestically manufactured container vessels through BCSL during this fiscal year (FY 2026-27). The container orders are being synchronized so that the boxes are ready by the time the first regional feeder vessels are delivered or chartered.
- The government is actively engaging with foreign shipping lines, promoting CMAS, and encouraging them to divert orders toward domestic manufacturers.
9 Likes
Why would I be interested if it wasn’t.
7 Likes
DP World to soon operate the upcoming Tuna-Tekra Mega Container Terminal at Deendayal Port (Kandla, Gujarat)
> https://x.com/Deendayal_Port/status/2047367351461695833?s=20
Kalyani’s upcoming facility is located near Kandla Port, and DP World is already one of its largest customers.
Key Details :
-
Concession Agreement: In August 2023, DP World signed a formal concession with Deendayal Port Authority (DPA) to develop, operate, and maintain the new terminal on a Public-Private Partnership (PPP) basis under the Build-Operate-Transfer (BOT) model.
-
Investment & Capacity: DP World is investing ~$510 million (₹4,243.64 crore) to build a greenfield mega-container terminal with:
-
2.19 million TEU annual capacity
-
1,100-metre berth (extendable to 1,375 metres)
-
Capability to handle next-generation vessels carrying 18,000+ TEUs
-
-
Timeline: Foundation stone laid by PM Modi in October 2023; expected completion in February 2027.
- Once operational, throughput of containers will increase significantly, which should translate into strong orders for Kalyani under CMAS.
7 Likes
Development of what seems to be the new facility diverted from Shivlakha railway station, a blue shed appears at end of what appears to be railway tracks(?). Newer images are from period Oct-Dec 2025.
Older satellite picture

Newer picture

Disc :invested
2 Likes
In ppt, it’s mentioned factory is above NH41.

Also, NH27 seems pretty far from Kandla port, whereas NH41 looks closer.

Latest disclosure to exchange mentioned this exact village

It’s just before Samakhiali junction, so Mundra, Kandla, many more locations are easily accessible.
Disc : invested
6 Likes
Shipping Corp of India tenders for methanol dual-fuel-ready container ships
4 Likes