Disclaimer: Personal opinion, Not a recommendation,
From today’s hearing, it became evident that other exchanges - primarily PXIL - have been attempting to find mechanisms to combine bids since 2013. To this end, they have periodically filed petitions before CERC and made representations to the Ministry of Power. The first such petition was decided by CERC in 2016 and primarily dealt with pro-rata allocation of transmission corridors. Under that order, 10% of the corridor was allocated to PXIL, with the balance allocated pro-rata (largely to IEX based on trading volumes) for a six-month period.
Subsequently, PXIL faced operational issues, including sustained losses and failure to meet minimum capital requirements.
In 2020, through the Draft Power Market Regulations, CERC attempted to introduce market coupling. However, following objections and hearings, CERC deferred this proposal to a future date, stating that market coupling would be introduced through separate regulations. In the process, the provisions relating to the Market Coupling Operator were removed. HPX was granted permission to operate as a power exchange only in 2022.
In Europe, what is coupled are the markets, not the exchanges themselves. In India, the five regional grids are already interconnected and effectively coupled.
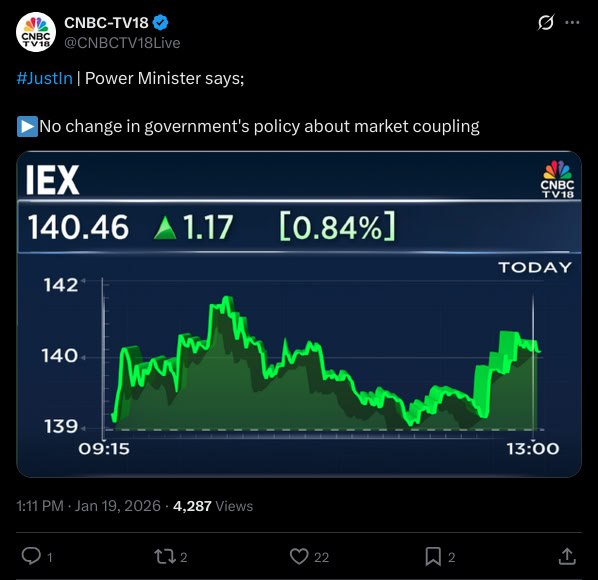
In the contested order of July 2025, CERC decided to implement market coupling through a round-robin mechanism. This, according to IEX, violates CERC’s own regulations, which require a separate regulatory framework for market coupling.
IEX’s core arguments are:
1. CERC bypassed its own regulations.
2. The process lacked transparency.
3. The stated objective of welfare enhancement was not achieved, as shadow-market studies showed only a marginal welfare increase (approximately 0.3% / 0.01%).
4. The order is tainted due to selective leaks by CERC officials, allegedly enabling profiteering, invoking the “fruit of the poisonous tree” doctrine.
One argument that IEX could not raise before APTEL, but may raise in the future before the High Court or Supreme Court, is a challenge under Article 19(1)(g) of the Constitution, on the ground that market coupling imposes an unreasonable restriction on the freedom to carry on trade.
CERC’s counsel broadly argued that the impugned order/direction forms part of a legislative process and is therefore not amenable to appeal before APTEL. Regarding the SEBI report, they stated the early repatriation of one employee and the transfer of two others to other departments of CERC, and that a suo-motu case/inquiry initiated by CERC has been stayed by the Punjab and Haryana High Court.
For interim relief, the primary issues are whether the appeal is maintainable (as contested by CERC’s counsel) and whether IEX has established a prima facie case. If such a case is made out, IEX must also demonstrate that it is an aggrieved party and that it would suffer irreparable harm if the order is not stayed.
In this context, IEX’s counsel is likely to focus on paragraph 6 of the order, which directs implementation of market coupling and effectively places all exchanges - including two with negligible market share—on an equal footing.
This challenge would remain relevant even if the round-robin mechanism is introduced later through fresh regulations. Notably, despite CERC’s counsel asserting that market coupling will not be implemented without formal regulations, the order itself directs the implementation of day-ahead market (DAM) coupling and further states that real-time market (RTM) coupling will follow based on the experience gained from DAM coupling.
Conclusion:
Power exchanges operate as a regulated monopoly in a winner-takes-all market, with trading done by at most a few hundred participants who are producing or distributing power. The disputes arising from this order and future regulations (if any) for market coupling are likely to continue for years—challenging the order itself before APTEL and the Supreme Court, and the eventual regulations before the Delhi High Court and Supreme Court. IEX has reasonable grounds to challenge market coupling, and SEBI’s findings regarding gains from UPSI strengthen its position. Prolonged litigation benefits IEX rather than its competitors, and the pro-rata allocation of transmission corridors continues to work in favour of IEX.