3 Likes
Mr. RP Singh has also written a scathing opinion on market coupling. For some reason CERC’s action seems very enigmatic. rpsingh's blog space - Market Coupling: A Premature Reform Hijacked by Private Interests
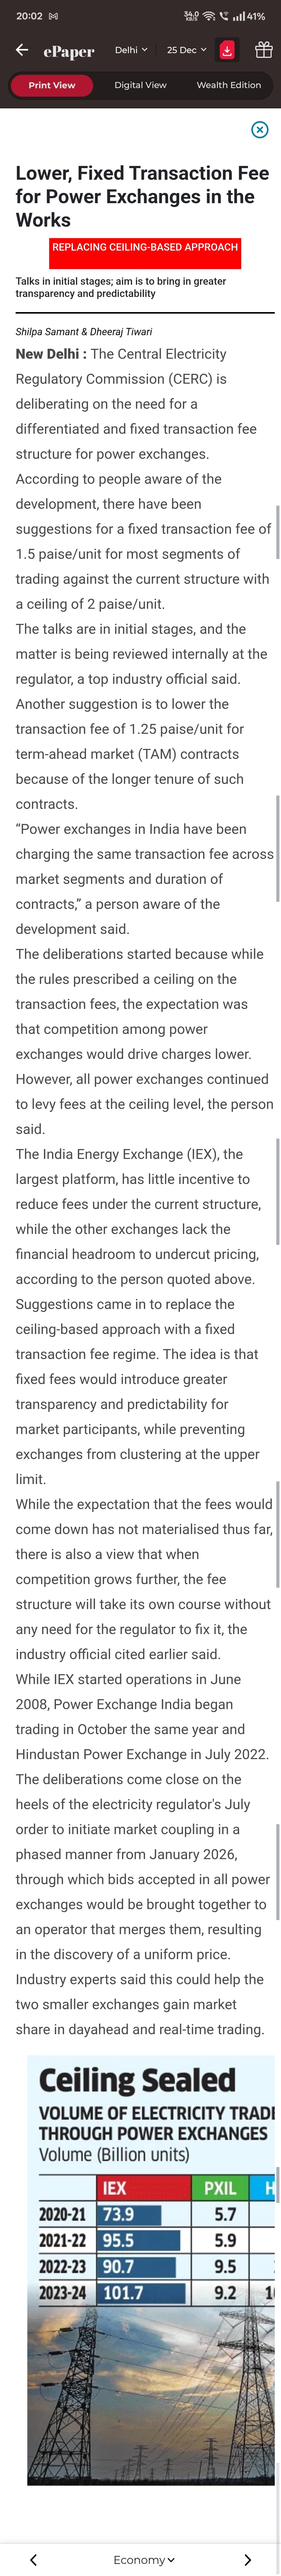
If broadening the power market with more competition was an intended outcome, then leaving the upper threshold as is and letting the individual exchanges provide discounts would have probably worked better. In earlier con calls, IEX has mentioned that they will be able to withstand reduction in fees, but other exchanges cannot survive.
Anyway, we have to watch how the case against market coupling proceeds in the appellate tribunal.
5 Likes
Mr. RP Singh’s blog captures the core of the issue. Really does raise the question - who benefits from this whole chicanery and why is it happening? “Regulatory capture” summarizes the issue perfectly.
Since FY24, other income for IEX has been more than all the expenses, so even at zero transaction fee it can continue as going concern. But I am not sure what the regulator is trying to achieve with this constant fiddling around.
3 Likes
It was clear that Coupling couldnt be implemented by jan, so I had a hunch that CERC would try to reduce the price cap. But its just unclear why CERC wants to mess up the most stable part of power transmission in india. IEX and other power exchanges revenue would be around 600-700cr for the whole year which is a miniscule part of india’s power transmission. The real problem lies with discoms who run into tens of thousands cr losses due to inefficiencies.
6 Likes
Yes. This is just another example of the regulator instead of trying to facilitate the system is in effect increasing the friction. NSE & BSE are examples of exchanges that have been massively profitable however they have been able to ensure that the underlying stock markets work smoothly and seamlessly. The regulator has interfered but has by and large let them make their profits which the exchanges have invested into better infra etc. It is in the industry’s interest that the exchanges remain healthy and profitable so that they provide good service and products.
6 Likes
Key Points from the News
- India’s power regulator, CERC, has introduced formal Virtual Power Purchase Agreement (VPPA) norms. (The Economic Times)
- Under these norms, large consumers can enter bilateral contracts with renewable generators without taking physical delivery of the electricity — the contract is financial, not physical. (The Economic Times)
- These VPPAs are non-tradable and non-transferable and have a minimum duration (e.g., one year). (The Economic Times)
- Generators continue to sell actual power on the market (like exchanges), while consumers settle the difference between agreed VPPA price and market price. (The Economic Times)
- The move is designed to help companies comply with renewable energy consumption targets (RCOs) and to support revenue certainty for renewable developers. (Energetica India)
Other draft/consultation sources add that:
- VPPAs may be eligible for RECs issuance, enhancing green credibility for participants. (azb)
- The framework aims to unlock financing for 40 GW+ of renewable capacity. (PV Tech)
- CERC is finalizing the rules to provide regulatory clarity and oversight. (ETEnergyworld.com)
Why This Matters for IEX — Investment Perspective
**1. VPPA reinforces the role of power markets
VPPAs work only if there is a transparent market price for electricity.
IEX provides Day-Ahead Market (DAM) and Real-Time Market (RTM) prices, which can serve as the reference price for settling VPPAs.
Implication:
IEX price discovery becomes ever more central as VPPAs grow — the market needs a credible public price benchmark.
This can increase trading volume and relevance of DAM/RTM prices.
2. VPPA supports renewable revenue certainty
Renewable generators gain a fixed economic stream via VPPAs without needing physical buyers at specific locations.
IEX benefits indirectly because:
- Renewable generators can continue selling actual output on the exchange, increasing liquidity.
- VPPAs may lead to higher generation being offered into DAM/RTM, enhancing sell-side liquidity.
Implication:
More volume + more participants → more transaction fees for IEX.
3. RECs and VPPA linkage
Draft guidelines and commentary indicate that RECs under VPPAs will be eligible and can be directly transferred to corporate consumers. (azb)
IEX already handles:
- REC trading
- (and may support ESCerts / carbon credits in future)
Implication:
VPPAs could expand certificate markets, increasing IEX revenue from non-pure electricity verticals.
4. Facilitates corporate demand for green power
Large commercial and industrial players (e.g., tech firms, data centers) now have a structured way to meet renewable targets without altering their physical supply contracts. (The Economic Times)
This reduces friction around:
- Renewable procurement
- Long-term green commitments
Many such players already participate on IEX or could do so via:
- selling surplus power
- purchasing on DAM/RTM
Implication:
Possible new user base of corporate buyers/hedgers engaging with exchange markets.
5. Not a direct line of revenue for IEX — but synergistic
VPPAs themselves are bilateral contracts and not traded like typical contracts.
But IEX enables the underlying price reference and liquidity.
So VPPAs are not:
- a new product IEX sells directly
But they enhance the utility and stickiness of IEX’s core platforms.
Investment View Summary
CERC’s introduction of virtual PPA norms is structurally beneficial for IEX because:
- It cements the importance of transparent market prices (DAM/RTM), which are critical for VPPA settlement.
- It boosts renewable generation liquidity on spot markets.
- It can increase certificate trading flows (REC/VPPAs).
- It broadens the corporate participation ecosystem, strengthening long-term market depth.
Therefore, VPPA norms validate and potentially accelerate demand for IEX’s exchange services, even if VPPAs themselves are not directly traded instruments.
6 Likes
I have been following this stock since 2012. But always found something lacking. Today while going through my old notes, I found a motilal oswal report from 2012-13.MCX and Financial Technologies
I checked iex 2013 motilal oswal share price estimation which came to INR91. Current market price is 140. Calculating you get a return rate of 3.75% per annum. Let us go for best circumstances before market coupling CMP was INR210. That results in a rate of 7.31% per annum. So in a 13 year period this stock has returned at best 7.31% and on ground reality 3.75%. I would have been better off keeping my money in savings account in bank. This stock fulfills all criteria to be called as a long term wealth destroyer.
4 Likes
check the market capitalisation as whole instead of going by just the price. the stock underwent split and bonus issuance after listing.
4 Likes
IEX was listed in 2017. Hope you are not confusing some other stock with IEX.
6 Likes
Before iex listing, it was part of financial technologies..FTECH. this iex stock price estmation was done by M.O.S.T analyst for sum of the parts calculation. He arrived at INR91
2 Likes
multiply the 91 number given by the MOST analyst by outstanding shares in that report and multiply the current price by the number of outstanding shares.
FTIL signs pact to exit IEX - The Hindu
FTIL exited stake at valuation of ~2000 crores and current mcap is 12000 crores, thats 15%+ CAGR, no wealth destruction by any means.
5 Likes
The stock was split from Rs. 10 FV to Rs. 1 FV in 2018. There was a bonus 2:1 in 2021. The company is a consistent dividend payer. So you will have to account for all that. I guess that journey of 91 to current 135 would be that of a significant wealth generation rather than destruction.
7 Likes
Microsoft Word - IEX_Media_Release_Power_Market_Update_December25
RTM volume for Q3FY26 is 12,650 MU (36% growth YoY) whereas DAM volume for Q3FY26 is 16,250 MU (2.8% decline YoY).
What is driving the volume towards RTM? The way RTM is growing it should overtake DAM in a couple of quarters, if so, will RTM prices become the benchmark for power derivatives?
1 Like
Valuation multiple is 26 now. why it should reduce to half (13 P/E) ? The revenue loss will lead to market cap erosion and not P/E derating which is already down from 45 to 26. IEX will trade at 25+ P/E (if not 40) for a very long time due to profit to free cash flow conversion ratio and longevity of business.
Also, summing up all your 3 low probability bearish points (50% mkt share, 50% transaction fee and 50% valuation multiple), IEX will lose 80% market cap from current level. Do you want to review your points?
Lot of times, a combination of things will happen - not necessarily fully one way or other.
What happens if Pts 1 and 2 from bear case and all 3 from bull case happens, how it will fare w.r.t to revenue, profits ?
e.g. 50% market share due to market coupling, 2 paise to 1.5 paise charge reduction
electricity market increase, short term trading gains, IGX goes ipo..
Rather than specific revenue, profits, will this in in growth trend or trailing trend. The direction of future is more important.
Please share your thoughts
IEX up ~10% today on strong positive remarks from APTEL in the ongoing market coupling hearing.
Tribunal called the CERC regulation process full of “theatrics” that could have been handled quietly
Expect CERC to be independent and above suspicion like Ceaser’s wife.
If there is something amiss, we’d like to enquire and take action to avoid a repeat.
IEX says:
Even without SEBI findings of insider trading, the coupling order is wrong and needs to be set aside.
Big relief rally as this threatens to delay/block uniform pricing that would erode IEX’s dominant market share.
This case is going to exciting.
Update1: IEX Case deferred. No withdrawal of Coupling order from CERC yet. Friday hearing will start again at APTEL. No Stay given by APTEL to IEX as of now.
Update2: Court has asked counsel for CERC to consider withdrawing coupling order.
Prima facie it appears to me either coupling order will be withdrawn or court seems inclined to pass more adverse comments.
Disclaimer: Biased and invested.
9 Likes
Two other important points put forward by IEX counsel were:-
(1) CERC is free to formulate the market coupling regulation as per its discretion but the regulation must meet the objective stated - i.e. material improvement of market efficiency - something not evident from 0.3% gains of Grid India pilot study.
(2) CERC is also free to enforce market coupling if it feels 99% market share is not OK but to do that it has to prove abuse of market dominance.
APTEL members were keen to finish proceedings at the earliest and didnt agree with date request for Monday. Hope, Friday is the day we get the good news.
15 Likes
IEX shares rise up to 13% on likely APTEL relief on CERC market coupling norms
As per my views stated earlier …let’s hope wrongs are righted now
1 Like
As per efficient market hypothesis, if market coupling is removed, and everything else remains the same, price should immediately increase to pre-coupling price (before 23 july).
As per behavioural finance, recovery may take time due to increased perception of regulatory risk, investor memory bias, and other behvioral biases at play.
Between coupling announcement and now there have been following changes -
- Another quarter of great results
- rumor on reduction in transaction price
I would rate overall impact of these developments as neutral.
Pre-coupling price also included overhang of a potential coupling order. In case the coupling order is withdrawn the overhang is also removed, which implies price should immediately increase to levels above 23july levels on 9th Jan.
Happy to learn if i am thinking correctly.
2 Likes