
Please use operating cashflow instead of this as PAT< Operating cashflows due to longer subscriptions sold by company to its suppliers (greater than 1 year) that would be better to forecast as deferred revenue is huge component and it creates float for company as it receives money in advance and recognise revenue later but expense being upfront in nature.
1 Like
Based on the 2025 annual report Indiamart has about 1500 cr investments in Mutual Funds and about 1200+ cr in Corporate bonds and Govt secs. My question is on the tax efficiency of these investments. On the capital gain from these investments the company would be paying CG Tax. In addition as the capital gain is part of other income to the company, they would also be paying corporate Tax. Is my assumption correct. I am naive on this subject. could someone clarify please..
If capital gains tax is paid, there will be no corporate tax again on the same income.
8 Likes
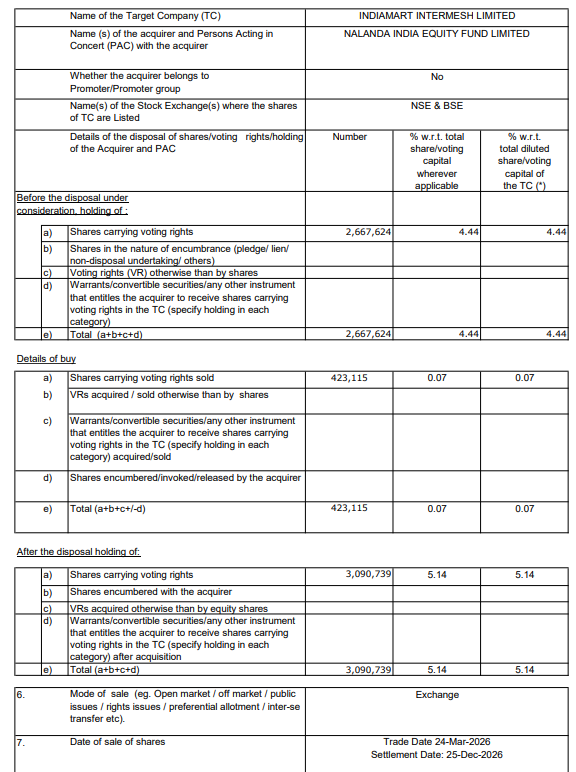
Nalanda India Equity Fund buys 11,17,834 shares @ 2110 INR via bulk deal. First new position in years.
Disc: Not invested, tracking.
8 Likes
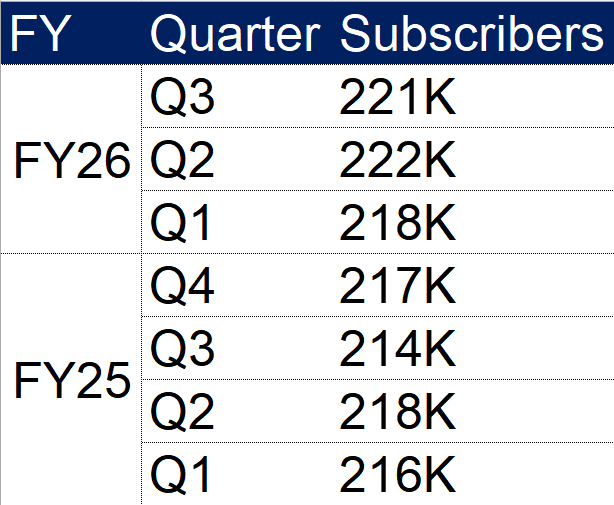
A question for those tracking IndiaMart, is anyone else concerned about the subscriber count staying flat? It’s been hovering around that 220K mark for nearly 7 Quarters now. The MSME market is around 63M, so is this stagnation on purpose to boost ARPU, or are they running out of people willing to pay? At what point does the lack of volume growth become a major red flag for the business?.
Disc: Not invested, tracking.
4 Likes
1 Like
63M number is a vanity TAM, many would be in business where IndiaMart cannot add value or limited to regional pockets of demand due to logistics cost.
Stagnation seems to be on purpose and imo necessary for the survival of business model from negative network effects. Chasing growth in supplier count by onboarding questionable suppliers would adversely impact the experience of buyers and once buyer brand IndiaMart as untrustworthy platform they may think twice before returning. Once the high intent buyers dry up so would the platinum and gold tier suppliers.
One could also argue that too many suppliers would drive down the lead dilution to a point that post fee no supplier is profitable.
I think the investment in Vyapar & Busy Infotech are acknowledgment by management that they would be better off building a walled garden ecosystem for paying subscribers than increasing the subscribers count number.
I would be very curious if these numbers increase materially. MSMEs are resource efficient and price sensitive, and many I think use silver tier strategically during the peak season as rest of the time, subscription price might not justify the value they get.
11 Likes
Is my understanding correct, a low subscriber count isn’t inherently negative. If identical leads are shared across Silver, Gold, and Platinum tiers while buyer numbers are limited, lower-paying members are naturally eliminated by price hikes?
1 Like
My few cents:
- Optimise before Scale
It is a winners-take all market in the long run, optimisation before scaling is the key. Because if you do not optimise the system correctly and scale, it is an utmost failure. Example: Snapdeal’s Vendor Crisis, they tried to increase the seller counts, diluting the brand reputation and creating a low quality goods. The last price hike is a good move for Indiamart. It keeps the brand equity intact.
It is similar to stock market analogy, how do you decrease the value of existing shareholders ? just dilute the shares outstanding when the stock is undervalued. Boom.
- Innovation and customer success are non-negotiable.
How did Yellow pages die ? They were phone book company, they had all the relationships with their customers. They were already a search market, they just did’nt know they were in a search market where they can use technology to scale. But Google did, Google destroyed them.
I am happy that Indiamart did not do a facelift of their website(frontend) or not cared to, but they have mentioned that they have a strong team in the backend. I hope their engineering team is as strong, hire the latest and quality data scientist and engineers, optimise and understand their buyer-seller behaviour closely.
With technologies like AI moving so fast, every graduate with an idea and a VC capital is a threat to e-commerce business. The only edge that Indiamart is going to have is only behavioural and mindset.
-
Create a Culture as a moat
It is really hard to create a culture in company in India, but their American counterparts did that pretty well, like what is the culture of Microsoft ? {To win}, What is the culture of Amazon ? {Be a day 1 company, never be a day 2 company}. But I don’t see anything in Indiamart here. With 60% market share in a cut throat market, it should start to become a what you call “Indian Alibaba“, as the title suggest. -
Look for any sights of discounts or predatory sales:
I am getting a hint of them giving massive discounts to get the subscriber counts. I hope they are not doing predatory sales like what byju’s did, you get it. {Your kid will fail, so get our service, stupid pitch}, it always ends up bad. -
50% of revenue comes from the Top tier:
I believe they have some pricing power there, it is better to have quality limited number of relationships between great businesses rather than plenty of relationships of bad businesses. Vyapar & Busy constitutes sticky though. -
Metrics:
I know the AI bot traffic can’t be taken into account of real customers, but they should give some light on their standarised bias free metrics in the subsequent concalls.
Disclosure/Comments/References:
→ Nalanda Capital invested is insignificant in terms of percentage of the money they manage, although they have invested after a drought of buying, I guess after 3 years. I believe they are testing waters here.
→ Yellow Pages : Yellow Pages: Evolving to Survive Mass Extinction - Technology and Operations Management
→ Byju’s : What Investors Should Learn from the Fall of Edtech Unicorn Byju’s
→ Culture : https://www.youtube.com/watch?v=fTwXS2H_iJo ; )
→ This is my low-IQ and reductionist take. If I give a bright Indian mind 1 billion USD to compete against Indiamart, what is stopping him/her not to compete ? Nothing.
Not financial Advice of any kind. Still studying about the business.
13 Likes
Few more cents, understanding and what I will do:
-
Every Buyer is a seller and Every Seller is a Buyer.
-
Indiamart should or will move towards high margin, low volume business in their top tiers and volume base on their bottom tier.
-
Silver Churn rates are unavoidable. If your subscribers are highly price sensitive, have less than 30 lakhs/year turnover, they will churn. Especially when they are monthly payers instead of yearly payers.
-
Protect your Gold and Platinum subscribers the most by giving the highest service {including new AI features}. Keep their (Total Enquiries/ Unique Enquires) ratio less for them, if you dilute their experience by creating more competition in seller traction, they churn. Save all the AI savings to add more value to the top tiers.
Example of what I mean: A Gold member will churn if they have like 10X competition instead of 3X. This is trivial isn’t ? Maintain a standard for the highest premium member, add “MVS Tag: Most Valuable Supplier“ tag for them, make them highly trustworthy after a checklist of verfication. I know this creates high churn rates in the silver tier. You do not create great businesses by people leaving you, you create by repeatable customers. The top tiers are repeatable, protect them at all costs.
-
Vertically integrate their busy software along with Indiamart, right now they looks like two businesses, of course you can see their revenue in consolidated statements. I think Indiamart should give 2 months free accounting tools for their platinum to make their life easy. Why justify 10% price hike as inflation-adjusted instead you can increase your prices more by giving most valuable services to your repeatable customers. Make Busy business as a Feature for top tier, not just a software subscription tool.
-
Should Indiamart focus on ARPU or Volume Growth ? The CEO says it is both. I agree with him, it’s volume based on the lower pyramid and price on the higher ( this pyramid analogy is what they tell in concalls )
-
The above steps might create less buyers as sellers are getting low ( in the top tier), as we reduce the ratio mentioned above, but what if we incentivise the top sellers to reduce prices. Sellers switch to another market place if the profits reduces, but once they get additional benefits, like more volume. They should probably stay in Indiamart.
-
They already choose not to care sacrifice growth for quality of the customer base. That is they clearly avoided Error of Commission. That is one of the reasons Nalanda added to their portfolio.
-
Avoid bad data, low-quality leads, hire best cyber security experts and data scientists.
**Disclosure/Comments/References:
**
→ Reduce Price to Increase Volume: Costco’s Model
→ Vertical Integration : Apple’s masterclass on making i-cloud vertical integrated to its devices.
→ Focus on Pyramid: Q2 FY26 Earnings Call: October 2025
→ Error of Commission/Bad Data: Bad Data = Bad Outcomes
Note: Showing that they increased subscriber counts at the cost of the platform’s quality is the not the best way for long term growth. By the way, their market share might reduce following the above but who cares, their top-tiers are high quality repeatable suppliers who gets high volume based buyers. ; )
Not financial Advice of any kind. Still studying about the business.
9 Likes
An important case that needs more attention
3 Likes
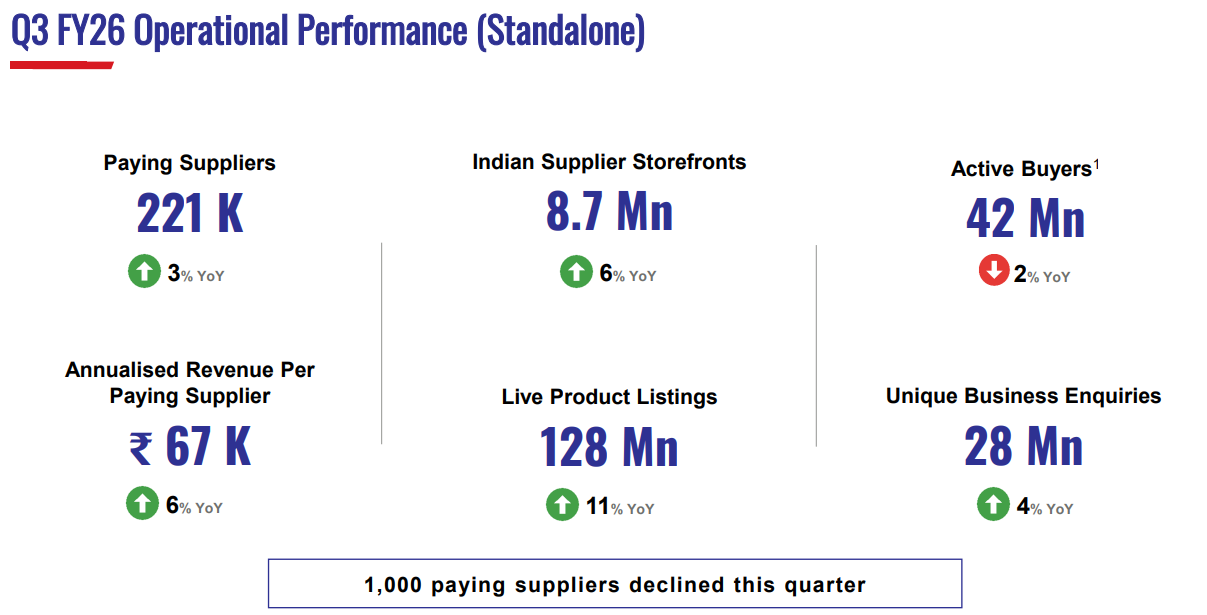
I don’t understand how this company will grow…..because paying suppliers are grow at 3% only and 1000 paying supplier declined this quarter…. I feel at the end its value trap….market will not offer high PE when you are not growing.
3 Likes
I found this article insightful. I’m getting a bit concerned now about the future sustainability of their business model.
Discl: Invested
3 Likes
Biased Metric : Online bot traffic will exceed human traffic by 2027, Cloudflare CEO says | TechCrunch
As per the article the real issue faced by the business is churn of subscribers especially at the silver level subscribers. The following excerpt is from one of the concall:
The Silver monthly and Silver annual customer continue to be a problem to be solved better. Despite such a low ARPU, there is a very, very high churn. However, once they upgrade to Gold and Platinum, I think their stickiness improves to almost 90%, and their ARPU also goes upwards of Rs. 2 lakh. So you are right, at Rs. 3,000 a month, why there is so much of churn, and we are yet to find a better solution there.
1 Like
Per the article I shared earlier, that’s because their subscribers are seeing less value in the subscription due to lower enquiries since OpenAI does not share links to IndiaMART microsite with their users.
1 Like
Its a value play. A good business with good fundamentals at a good price. A compounding story.
1 Like
They invested in Aerchain, which is an AI-powered procurement automation platform that delivers autonomous sourcing for enterprise procurement teams. It raised a $13M round.
https://www.f6s.com/company/aerchain?action=linkClicked&version=india_2026_03_24&source=email&template=fresh_funding_india§ion=funding&linkType=companyName&linkText=Aerchain&utm_campaign=website&utm_medium=email&utm_source=sendgrid.com#about
1 Like
IndiaMART’s stock has been sideways basically because of one BIG problem - subscriber churn is out of control, especially silver category customers (4% annual, 7% monthly churn!).
Paid subs actually dropped ~1,000 QoQ to 2,21,000 in Q3 FY26. The September 2025 price hike for silver customers made things worse tbh.
So now ARPU is doing all the heavy lifting for revenue growth. Not ideal na?
JM Financial and Motilal Oswal still have Buy ratings (targets ₹2,800 and ₹2,750), but Nomura is bearish with a Reduce rating and ₹1,975 target.
IMO the most intresting thing, Bandhan Small Cap Fund is treating this as an “unpopular value stock” and accumulating. Management says they’ll fix churn before pushing new acquisitions. Could be worth watching!
3 Likes