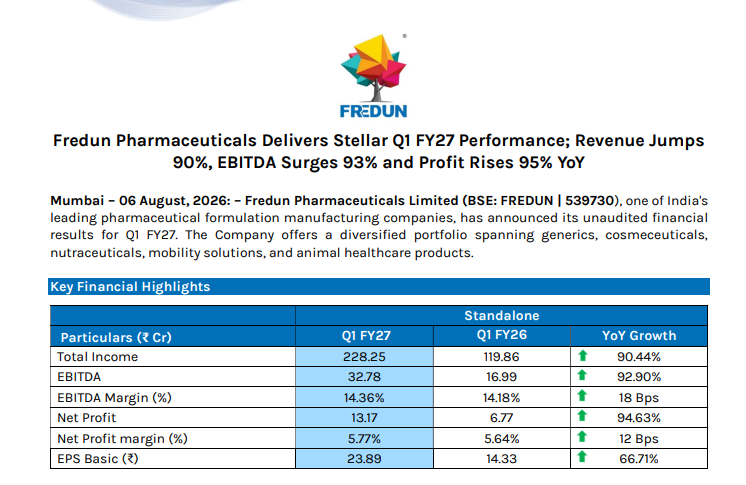
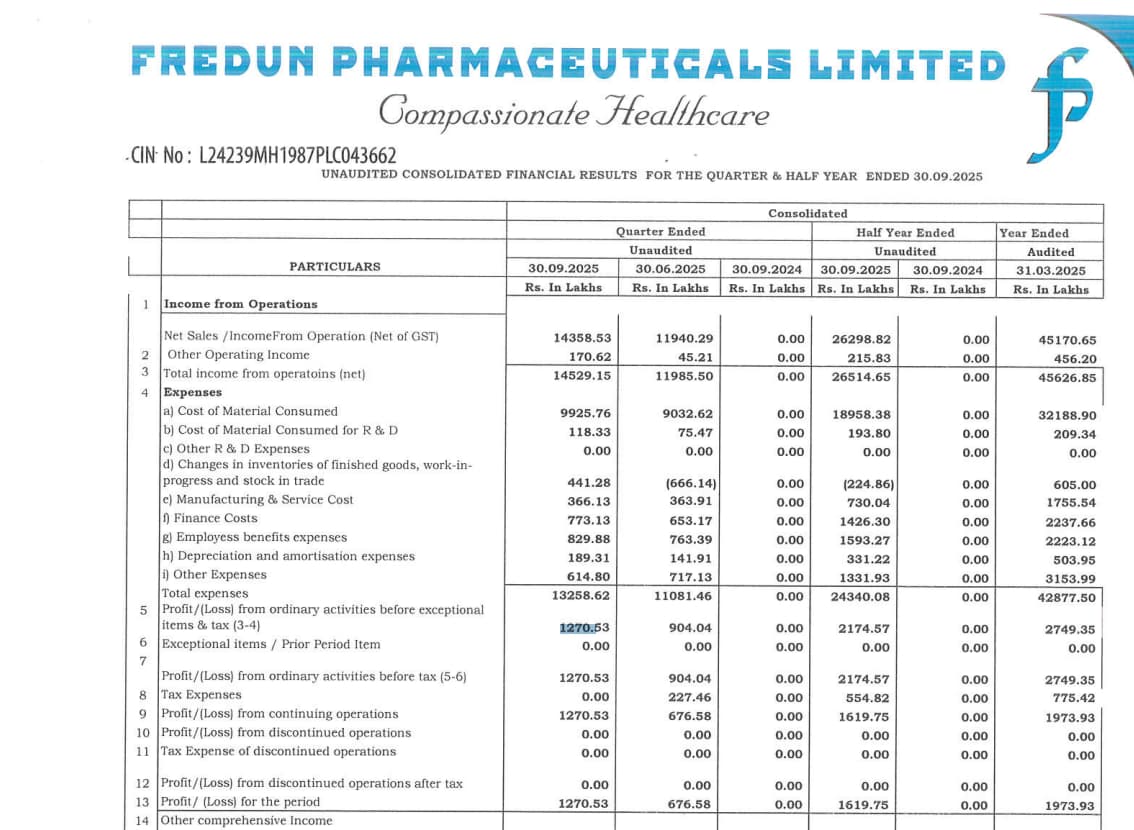
Another excellent quarter from Fredun pharma.
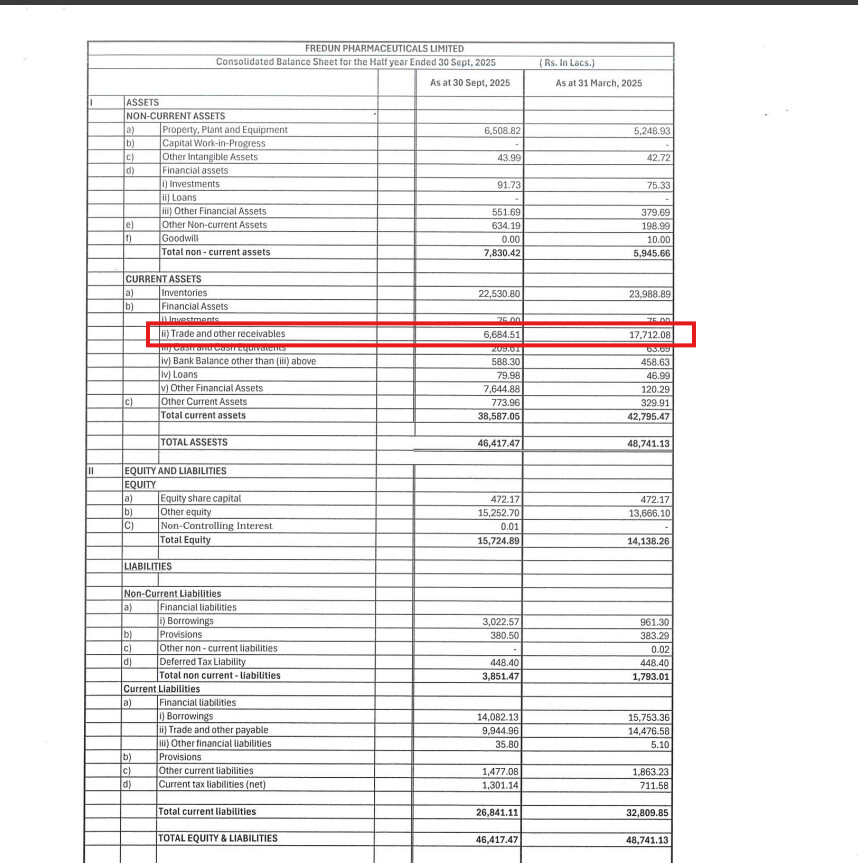
Balance sheet has also getting better with receivables going down and capital infusion(post the quarter end).
Management is walking the talk.
Regards,
Raj
Disc: Invested
Another excellent quarter from Fredun pharma.
Balance sheet has also getting better with receivables going down and capital infusion(post the quarter end).
Management is walking the talk.
Regards,
Raj
Disc: Invested
there is a similar company in this space - sequent. not sure if they both will be competitors ?
Sequent scientific is towards cattle and poultry healthcare.
Fredun Pharma addresses pet care also together with cattle and poultry.
In addition, with the recent acquisition of One Pet Care, they have now entered Pet Grooming business. This makes the proposition even more interesting.
Waiting for the outcome from its investors concall .
Management gave a healthy long term growth plan in the last investors call.
Refer the screenshot from last investor’s meet.
Q2FY26 Conference Call Highlights
General:
Financial Performance
New Age Businesses:
Pet Care:
Mobility:
Nutraceutical:
Cosmeceuticals:
Wagr:- Recent acquisition
Contract Manufacturing:
Fund raise:
It will be used for new product development, team building, marketing, and distribution.
Team Augmentation:
Growth Forecast:
Disc: Invested.
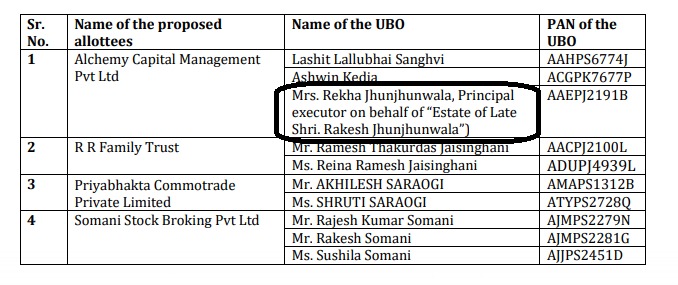
Fredun published the ultimate beneficiary name of the recently done QIP. List is below:
One interesting name appears in the list though the quantities allotted are insignificant,
Regards,
Raj
Disc: Invested
It’s Paid article. Anyone has subscription please share your insights from the article.
Q2FY26 Conference Call Highlights
Financial Performance
Q3 FY26:
9M FY26:
General:
New Age Businesses:
Pet Care:
Mobility:
Others:
Capacity expansion:
Fund raise:
Guidance:
Disc: Invested. No trade in last 90 days
The above summary is my understanding of the conf call of Q3FY26. I might have missed out or misunderstood a portion of it.
Q4FY26 Conference Call Highights:
Operational Highlights:
Financial Performance:
Q4FY26:
Total income: 213Cr vs 167.41Cr in Q4FY25, a growth of 27.27%
EBIDTA: 29.13Cr a growth of 67.05%
EBIDTA Margin: 13.67% vs 10.41% an improvement by 326 basis points
Net Profit: 11.07Cr a growth of 56.47%
Net profit margin: Improved to 5.19% expanding by 97basis point.
FY26:
Total income: 639.12Cr, a growth of 40.8%
EBIDTA: 94.79Cr a growth of 72.05%
EBIDTA Margin: 14.83% an improvement by 276 basis points
Net Profit: 33.21Cr a growth of 59.59%
Vintage business: Our vintage business is growing at 15-20%. Exports are around 110-120 crores, tolling is 24 crores, institutional sales are 120-130 crores, and domestic third-party branding is 45-50 crores.
For new-age business: Pet care did 42-43 crores, mobility did 29-30 crores, nutraceuticals did 26 crores, mass-market cosmetics did 20-22 crores, and dermaceuticals did around 12 crores. New-age businesses are growing at a 40-50% CAGR. Gross margins in the new business are higher, around 45-55%, with some products like diagnostics at 80-90%.
We are transitioning from a contract manufacturer to a mass-market consumer product company while retaining our pharma roots.
New Business Lines:
Hormonal and anti-aging lines:
This year we focus on hormones and anti-aging. We are launching two sets: one is a hormonal line and the other is an anti-aging line.
Harmonal line: There are hormones which are used for medicinal purposes. We are using the doctor channel because we want only good hormones in the market. There is a huge demand as the population gains awareness and requires targeted therapies such as testosterone replacement therapies. Even in terms of pregnancy and estrogen for both men and women, hormones as a sector are not very focused. The market is quite fragmented here as there are not many good hormone products available.
We have created a list of products where we will be one of the first or second in the country to have them. We have a ground-level team currently focusing on the MMRDA region and certain metros. We will also be the first to have medicated hormone products sold online through our website and doctor channel.
Anti-aging: The number of clinics is growing rapidly. CDSO recently announced that only certified doctors can prescribe these therapies, which works to our advantage. We are one of the first manufacturers for NAD and NAD plus and have exclusive import rights for the API. With an end-to-end supply chain and decent margins, we can use our dermaceutical and specialized anti-aging products to create a basket for dermatologists and doctors. It is a high-margin, fragmented, and unorganized market with no strong competition, making it a “brownfield” for us to build our brand quickly.
Fitness Industry: We are also adding specialized therapeutic products for the fitness industry, such as specialized pre-workouts and protein powders, because we are already doing an entire protein range under Fredun Energy. These targeted therapies will help the fitness industry and give doctors alternative long-term treatments.
Mobility Division:
Mobility has been a very positive division. Last year we did almost 30 crores in mobility products. Mobility has four brands: Grayson, DG on Neborn, and we are launching Mobilix by July. These products like knee braces, orthopaedics, and digital products like BP machines and glucometers go to chemist shops. We use the same distribution channel we have for Fredun Pharmaceuticals to add on mobility products, giving us an upper hand in distribution and logistics compared to competitors.
We foresee reaching a 100 crore run rate within two to two and a half calendar years, and a 250 to 300 crore enterprise within 5 to 7 years. It is profitable and does not burn resources as we are a completely offline pure distribution brand. We have strong distribution in Maharashtra and are expanding into Goa, Chhattisgarh, and Karnataka. Our Mobilix brand targets physiotherapists specifically, who are first-hand influencers for these products. Our pre-booking is already completely booked for the July launch. The division is growing at almost a 55% to 60% CAGR.
Pet business:
We are the only company manufacturing allopathic formulations, herbals, grooming, functional foods, and diagnostics all under the same roof. Our long-term goal is that by 2032-2033, no pet in India can be born or die without using a Freossi product or service. We create products for all parts of a pet’s life. We are launching 42 variants of functional food biscuits for all kinds of breeds.
In grooming, we have displaced market leaders because of our manufacturing background in human dermaceuticals and cosmetics. Within the next 9 to 12 months, we will come out with formulations that will be the first in India for pets. Our online platform, Wagr, is in the launch phase with a soft launch in mid-June and a full launch in the first week of July. It is a holistic pet care portal, not just e-commerce. We also launched India’s first bulletin on radiology and vet imaging to educate doctors on diagnostics. We are pioneers; for example, we recently performed a CT scan for a cobra.
Pet care business model: Most of our products are prescribed. We didn’t start with online platforms; we started with first-line influencers like breeders, groomers, dog walkers, and trainers. We went to Tier 1 through Tier 4 cities to train them on product benefits. This created a bond before we launched the products. Doctors then realized we were strong in science. We have India’s top nutritionists and vet radiologists on our team. We are not spending money to buy inorganic growth; we are a pet care company, not just a pet food company.
Wagr.in, it is a holistic pet care portal using AI and analytics. It should be active and live within the next 15 to 20 days.
Future projections:
Margin growth will continue at 30-40% on current levels. Targeting a 10-12% PAT margin in next 8 quarters.
We are on track to achieve our 2029 and 2030 targets earlier.
Others:
Inhouse vs Outsourcing: We have around 43 locations. We outsource products we cannot make in our pharma plant, like wheelchairs or specialized injections. However, 80% or more of our products are manufactured in-house. We are adding 12 to 13 packing lines by September and constructing a new wing. We are a cluster of four plants at one location and are setting up facilities for functional foods. It would take 15-20 years for a competitor to match our validation and licensing levels.
Working capital and free cash flow: We have constantly improved inventory levels. We needed higher inventory while launching 2,100 SKUs, but now at 700 crores top-line, our inventory is only 270 crores. Cash flows have improved and are now positive from operations. Debt to equity is 0.8. We are growing faster than anticipated, so working capital will be stretched, but we are mitigating those concerns.
Finance cost: The absolute number might increase but it will decease as % of sales.
Drivers for margin improvement and sustainability: New-age businesses have higher intrinsic margins. Vintage businesses margin has improved from 1% to 6.5% with improvements in scale. We are looking for a 10-12% kind of PAT margin within next few years.
Impact of war in middle east: Prices have increased but we generally keep three to four months of stock, so the initial jolt never bothered us. We were able to cater to clients at the same prices, which increased our sales. We have orders in hand for 6 to 7 months, upwards of 320-330 crores.
Regards,
Raj
Disc: Invest since almost a year. No trading in last 6 months.
I Have summarized it based on my understanding of the call and took some help from notebooklm to generate the base transcript. Please do your due diligence.
Fantastic result by Fredun.
Regrads,
Raj
Disc: Invested since more than a year and sold one third of my holdings in recent runup. Still among my top 3 holding.
Fredun Pharma Q1FY27 Conference Call
Growth:
Vintage business growing @15-20%
New age businesses growing @ 35-45%. Some growing even faster due to lower base.
Our new brands such as pet care, nutrition and mobility brands have also got good acceptance from pharmacies.
We will grow 25-35% for next 5 years as we have a very small base.
Q1 historically has been weaker quarter. This time it was a little better. We booked some extra orders buy giving buyers to buy at older prices due to availability of old inventory. Next quarter will be similar to Q1 numbers.
Capex:
Financials:
Working capital required for us is 170-175cr on a sales of 850Cr which is reasonable. 50% of working capital is cash on hand. We will need higher working capital when the revenue grows.
Interest costs are slowly reducing.
Inventory days are around 145 days which will go down to 120 days in next four quarters.
Our focus is on product penetration and acceptance for next 3 years, not purely on margins.
Others:
Every single division has a separate CEO in place.
Core team is almost same since last 19 years when I came in and hired them.
GX Business:
Pet Care:
Pet care business is currently 40-45Cr, Will grow 40-50% for next 3-4 years.
We are adding 42 variants in functional foods. Jain variant has picked up very well. We have different food for Tier 1 city and Tier3-Tier4 towns. We are also coming out with cat biscuits. We are creating a functional line for Cat which will come out in next 6-7 months.
Wagr.ai site is looking great. We took 3-4 months to create a team post acquisition. We are creating a pet parenting platform. It will become a comprehensive platform for pet owners, groomers, dog walkers, vets besides pet parents. We will link our diagnostic also. It will also be for blood collection/donation for pets. It will get better as we are just in beta phase. Next 90 days there will be campaigns coming out.
Some acquisitions are coming in pet care.
This is my interpretation of the conference call discussion. I might have missed some key points. Please do listen to it for exact details.
Disc: As above.
“Fredun Pharmaceuticals Acquires 26% Stake in ₹300 Crore-Valued Goodman Vetcare Pvt. Ltd., One of India’s Longest-Standing Dedicated Pet Pharmacies”
This was the announcement. The company Goodman has just 3 stores. Hasn’t Fredun over overpaid on this one ?