DDev Plastiks Industries Ltd - A Smallcap Gem

The detailed mechanics of Ddev’s BESS entry, including their manufacturing model, component sourcing, and technology:

1. The Assembly Business Model

Ddev Plastiks is adopting an “assembly-led manufacturing” model rather than attempting to manufacture battery cells from scratch. This capital-efficient approach allows for a faster go-live period, lower capital intensity, and phased capacity additions. The company will position itself as a BESS systems assembler and supplier, targeting EPC (Engineering, Procurement, and Construction) players, utilities, and commercial/industrial customers.

2. Outsourced / Imported Components

Because Ddev is using an assembly model, the foundational chemical and electronic components will be sourced externally:

· Lithium Cells: The company will not manufacture the actual battery cells. Instead, they will import/buy high-quality Lithium Iron Phosphate (LFP) prismatic cells.

· Core Electronics: Components such as the Battery Management Systems (BMS), Battery Management Units (BMU), and internal cables will be imported or purchased from specialized suppliers.

3. In-House Capabilities and Manufacturing

While the base cells are imported, the value addition, integration, and quality control will be strictly managed in-house:

· Pack and Container Assembly: Ddev’s automated lines will take the imported LFP cells and assemble them into batteries, integrate the batteries into packs, and finally assemble the packs into fully integrated BESS containers.

· System Integration: The in-house process includes integrating power electronics, Energy Management Systems (EMS), temperature cooling systems, and fire management systems into the final container.

· Customization: BESS units will be tailor-made in-house to suit specific geographic and environmental requirements. For example, the design, cooling, and structural build will vary significantly depending on whether the unit is deployed in a marshy area like Khavda or a high-temperature desert in Rajasthan.

· Rigorous Testing (Reliability Lab): Ddev is setting up a state-of-the-art reliability lab inside the factory. They will conduct 100% testing on all imported LFP cells, BMS, and cables before production begins. During production, every parameter—including open-circuit voltage, insulation resistance (IR), and safety precautions—will be tested in-house. They also plan to conduct mandatory safety tests like UL9540A and IFC certification testing internally.

4. Technology Profile

The technology powering Ddev’s BESS venture is focused on longevity, scalability, and international standards:

· Cell Chemistry & Configuration: The company will exclusively use LFP (Lithium Iron Phosphate) prismatic cells, which are known for their safety and long lifecycles. The assembly lines are configured to handle advanced, high-density cell configurations ranging from 314 to 587 (and up to 600) kilowatt-hours.

· Future-Proofing: The automated assembly line is designed to be compatible for at least the next 10 years, capable of running BESS prismatic cells to build containers ranging from 5 MWh to 10 MWh.

· Lifecycles: While current industry standards offer around 6,000 cycles, Ddev’s technology target is to provide systems capable of 10,000 cycles, translating to a lifespan of more than 15 years.

· Technical Tie-ups: To ensure technological superiority and bridge any competency gaps, Ddev is actively securing technical tie-ups and technology transfers with partners in China and other countries.


To determine whether this is a “Good Diversification” or a classic Peter Lynch-style “Diworsification,” one must objectively weigh the strategic rationale against the execution realities.

The Bull Case: Why it is a “Good Diversification” (Pros)

1. Massive Total Addressable Market (TAM) & Tailwinds

India is entering a multi-year clean energy build-out, with a national target of 500 GW of renewable energy by 2030. Because solar and wind are intermittent, BESS is a critical enabler for grid stability and peak load management. Projections indicate India’s BESS capacity could reach an astronomical ~208 GWh by 2030 (a ~$32B value). Capturing even a fraction of a percent of this market provides exponential revenue growth visibility.

2. Capital-Efficient, “Asset-Light” Assembly Model

Crucially, Ddev is not attempting to manufacture battery cells from scratch, which requires billions of dollars and deep chemical IP. Instead, they are adopting an assembly-led manufacturing model. This ensures a faster go-live period and drastically lower capital intensity.

3. Controlled Downside Risk (Self-Funded)

The Phase 1 expansion involves setting up a 5 GWh assembly plant by Q3 FY27 with an estimated investment of just ₹150-200 crore. Because the core compounding business generates strong Free Cash Flow, this entire capex is being funded through internal accruals. The company is not loading its pristine balance sheet with debt to fund this venture, effectively capping the financial ruin if the project fails.

4. High Revenue Velocity & Quick Payback

The revenue potential per GWh is staggering. As noted by management, 1 GWh roughly equates to ₹800-₹900 crore in top-line realization. With a targeted 5 GWh capacity, the revenue ceiling is massive. Management anticipates a quick payback period of 2-3 years, ensuring that if executed well, the return on capital employed (ROCE) will be highly accretive.


The Bear Case: Why it risks being a “Diworsification” (Cons)

1. Total Departure from Core Competency

This is the most glaring risk. Ddev’s 40-year moat is built on reactive extrusion, polymer formulation, and chemical engineering. BESS, on the other hand, is an electronics and integration play. It requires expertise in Battery Management Systems (BMS), thermal management, software integration, and power electronics. Moving from chemical compounding to electronics assembly represents a severe “competency gap.”

2. Severe Working Capital Drag

Ddev’s core business operates on a highly efficient ~60-day cash conversion cycle, selling to private wire and cable giants. The BESS segment’s primary customers will be utility companies, EPC players, and government-backed entities (like SEKI, NTPC). Government receivables in the power sector are notoriously sluggish. If BESS scales to thousands of crores in revenue, it will require massive non-fund-based limits and could severely strain the company’s working capital cycle, tying up cash that the core business generates.

3. Margin Dilution

Ddev has spent years premiumizing its polymer portfolio to achieve an 11% EBITDA margin. The BESS segment, being an assembly business where cells are likely imported or bought from third parties, commands much lower initial margins, guided at ~6-8%. As BESS revenue scales, it will mechanically drag down the consolidated EBITDA margins of the company, potentially leading to a lower valuation multiple from the market.

4. Fierce, Deep-Pocketed Competition

The BESS space is not a niche. Ddev will be competing against integrated giants (Reliance, Tata), specialized battery makers (Amara Raja, Exide), and established global EPC players. These giants have backward integration into cell manufacturing and massive balance sheets to absorb long working capital cycles, giving them a structural pricing advantage over a pure-play assembler like DDev.


An Asymmetric, Speculative Bet?

Currently, the BESS venture leans closer to speculative diversification rather than a natural synergistic extension. There is very little operational synergy between melting polymers for cables and assembling lithium-ion battery packs.

However, it avoids being a fatal “diworsification” because of the disciplined capital allocation. By restricting the initial bet to ₹150-200 crore from internal accruals, management has created an asymmetric risk-reward profile:

  • If it fails: The company writes off ₹200 crore. The core business (which generates ~₹130+ crore in operating cash flow annually) absorbs the shock, and the company survives.

  • If it succeeds: The company transforms from a ₹2,500 crore polymer supplier into a ₹7,000+ crore energy transition player.

For an investor, the core compounding business remains the anchor of the valuation. The BESS segment should be treated strictly as a “free option”—a high-risk wildcard that should not be factored into conservative core earnings projections until Ddev actually demonstrates a track record of winning bids, assembling the units, and, most importantly, collecting the cash from utility clients.

Disclosure:

I have no position as of now, still studying. No Buy/Sell Recommendation.

3 Likes

Hi everyone,

I have been tracking this company for quite some time now and one of my major cracks in their business may start to play out. Crude oil - which is the major raw material component for polymer compounds has seen a sharp increase in its price. This will be a rather large pain point for the company as it does not have a strong pricing power in the product categories as is reflected in its margin profile. Yes, they have the ability to pass through the costs ahead but for a cable manufacturer the bulk of the cost is derived from copper and aluminum prices. While Ddev Plastiks enjoy exclusivity in the domestic circuit, in case of price increases, companies can look to diversify their supplier base and can look elsewhere like exports for cheaper pricing as well.

With this in the forefront, I am concerned about the moat the company posses. While it does have regulatory barriers in the high voltage compounds for which trials are underway and that will add to its credibility and margins in the future, I am unsure how the company looks to curtail the margin volatility risks that it will always face.

Please let me know if I have made an error in my judgements and your views on this. Looking forward to your replies.

Disclosure: Not invested in the company.

1 Like

Your concern about crude oil impacting polymer prices is valid, but the picture may be slightly incomplete.

Companies like Ddev Plastiks Industries Ltd usually operate on a cost-plus model.

Selling price = Polymer price + Additives + Processing margin

So if polymer prices rise, the increase is generally passed on to customers with a lag. Because of this, crude oil volatility mostly affects working capital and short-term margins, not the long-term economics of the business.

Also, switching compound suppliers in the cable industry is not very easy. Cable manufacturers must run extensive testing and certifications before approving a new compound, which creates supplier stickiness.

So while raw material volatility is a genuine short-term risk, the business is not purely commodity-based. The moat comes from formulation know-how, approvals, and long-term relationships with cable manufacturers.

In that sense, the concern is partly valid but somewhat overstated.

2 Likes

Thanks for the reply.

While this fortifies the moat that Ddev Plastiks has built over the years don’t you think that in order to become a high quality business you need to be able to sustain or rather increase margins through various means (based on the mental model that I apply to businesses). To me it seems that the company will always be at the mercy of commodity price spikes. While they have a strong balance sheet to absorb such shocks, would it not result in the market valuing it on the lower end of the spectrum because of that risk. My concern with the business is that while the company is well positioned to profit from the growth in the wires and cables industry, it can falter behind because of how dependent it is on the raw material procurement.

1 Like

No industry is foolproof. That is the dynamics. And it also applies to all, DDev included. Having said that, I will refer to the points already mentioned in this thread on cost-plus business model. So they are not at mercy of commodity price spikes .As regards increase in margins, they have taken several steps in last few years, including recent BESS venture.

1 Like

You are right that Ddev Plastiks is exposed to raw material price fluctuations because polymers are commodity products. However, the company tries to protect margins through value-added products, long customer relationships, and cost control rather than only depending on price increases.

Also, their strong balance sheet and diversified product mix help them manage volatility better than smaller players. So while margins may fluctuate in the short term, the long-term quality depends on how well they improve product mix and efficiency, not just raw material prices.

2 Likes

Porter’s Five Forces Analysis on Ddev Plastiks

1 Like

Q4FY26:

Big jump in other expenses (63cr vs 43cr qoq vs 38cr yoy) causing decline in EBITDA. Gross profit actually increased to 150cr vs 124cr yoy with gross margins improving to 19% vs 17% yoy.

• Geographical presence increased to 55+ countries (vs 50+ yoy)

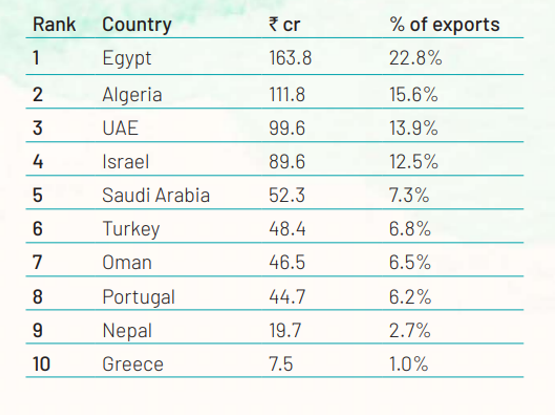
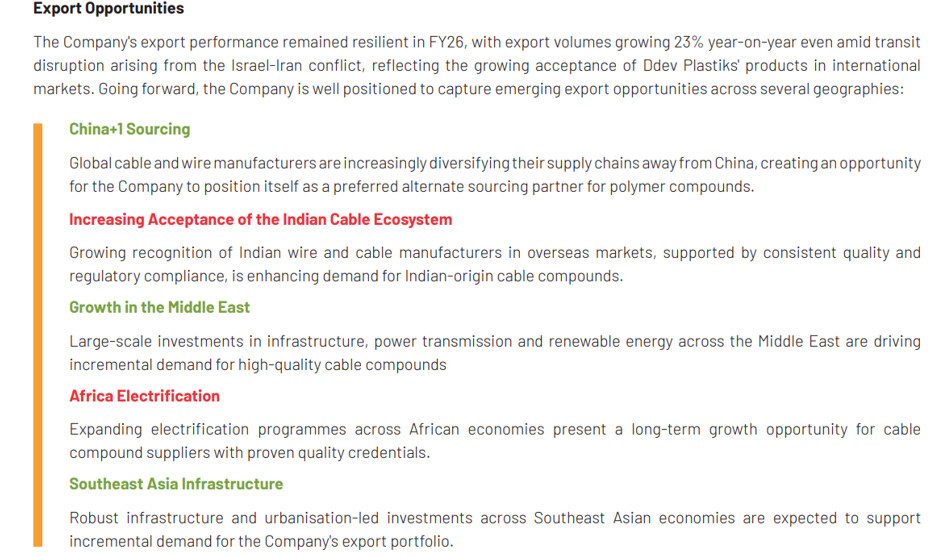
• Export growth – 30% (718cr vs 551cr in FY25)

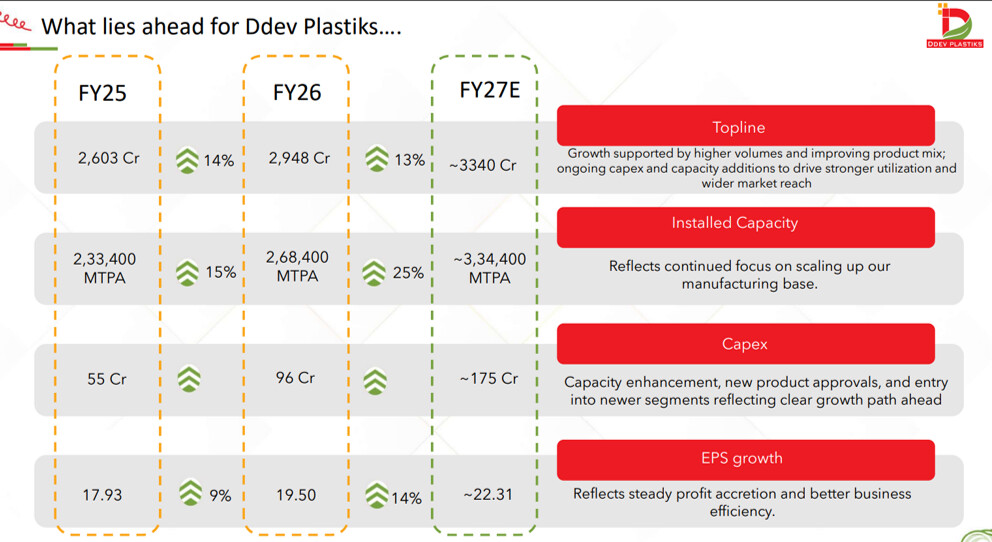
For FY27, we guide for ~13% revenue growth, 15% growth in volumes to Rs2,31,000MT, and sustainable EBITDA margins of 11%, with BESS upside being additive to these numbers.

• Capex of ₹175 crore for FY27


(BESS PROJECT)


(79-21% India-overseas in FY25. 83-3-12% for PE-others-PVC in FY25. 83-3-13% for W&C-Packaging-others in FY25.

Big jump in others category in both product and segments.)

• Volumes – 2,01,370 MT. EBITDA Per Ton – 15,768 For FY26


(Good jump in XLPE and HFFR, but still EBITDA margins not improved)


Volume has grown by 7% due to impact of War. Had there been no such situation we would have grown by almost 10% this year

• Israel - Iran conflict initiation on 28th Feb 2026 has led to disruption in the transit of Exports as well as prices/availability of RM.

CONCALL NOTES:

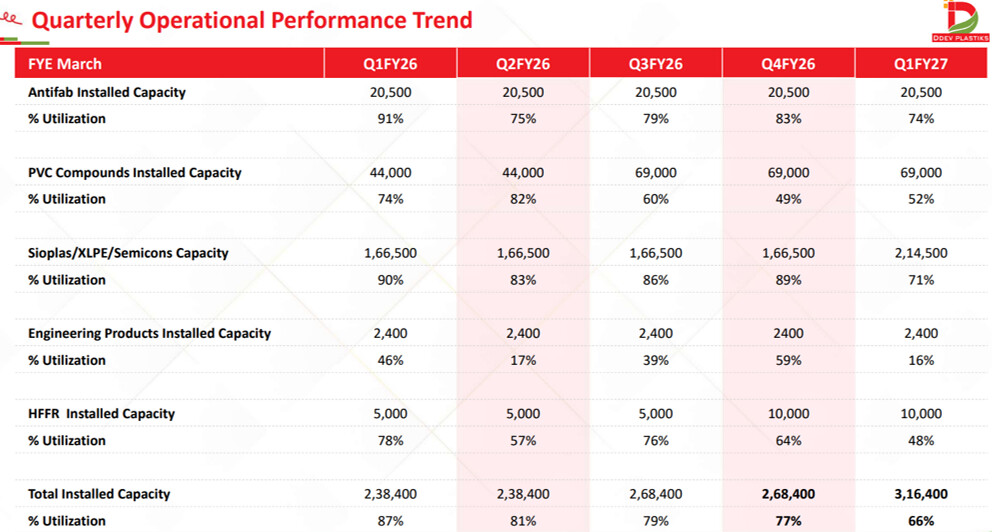
• FY27 GUIDANCE: Volumes = 231000 MT (15% Growth implied). Capacity utilization of 73% and a year-on-year revenue growth of 13%. EBITDA margins anticipated at approximately 11%.

BESS revenue has not been included in the above figures and will be additional to these numbers.

• BESS PROJECT:

o We aim to develop 5 gigawatts of installed capacity in a phased manner with each gigawatt projected to generate approximately INR800 crores to INR900 crores in revenue.

o This positions BESS as a meaningful and incremental contributor beyond our INR5,000 crores revenue aspiration from the polymer compounding business by FY 2030 with an additional top line of INR2,000 crores to INR2,500 crores alone from this vertical of BESS.

o FY27 guidance: This is the first year for us. So, there will be some ramp-up time, which will be required to stabilize the production. And that is why as far as revenue guidance is concerned, we consider it will be in the range of INR200-odd crores of revenue.

o INR200-250 plus crores of revenue will be a good breakeven point. So, there won’t be any loss as such in FY27 from BESS.

o We have started approaching customers. We have started discussing with them. We have started to understand their requirement. And in a lot of areas, we are discussing on the technical front as well.

o We have already discussed with all the Tier 1 developer in India, including Sterling, Wilson and Enrich and Orange. So, this customer, we already started to pitch and the demand is high. And we have started to have their quality parameters, validation, quality supply chains, all the documentations required. So, we have submitted all the documentation by the supplier quality audit point of view. So, next couple of months, they will see this our factory readiness. And after factory readiness, we’ll sit together and we’ll sign MOU for a long-term to supply in the gigawatt hour scale.

So, it takes around three to six months to board on any big developer. So, we already started three months ago. So, the data we have available, we already submitted. And those we are under process like a factory audit and the certification, we will process and will submit it in a couple of months.

o In longer terms, BESS also entails a good margin beyond 10%.

o FY28 targets: We are targeting 1 gigawatt hour of sales and close to INR800 crores to INR900 crores of revenue, expecting EBITDA margins of 10-plus.

o Initially, we are going to import it from China. And over a period of time, we will be working on backward integration of many components, which are easily available in the country. Still as of now, we don’t have sufficient capacity in the country, and it will be imported for the near future.

o So, basically, it’s an assembly line on the BESS side.

o The actual IP lies in energy management system or battery management system, right? Are we planning to even import that product? Or are we going to have our own IP on those things? What is the plan right now on those things?

In future, we are going to make our own BMS and own EMS, already started working on that. EMS in India will be restricted after one year. So, we already started to work for EMS.

India is allowing you can import BMS from China. But EMS, you must start developing made in India.

o Working capital requirements: For the first phase of 1 gigawatt hour, we have plans that the total working capital requirement will be in the range of INR200 crores to INR250-odd crores, and we have sufficient limits available with us for that funding the same as well as the margins for them are also similarly available with us as a free cash flow. As far as the full 5 gigawatt hour capacity is concerned, definitely, we’ll work out and think of increasing the cycles from banking channels as well as other channels as well.

IRAN WAR: The intensification of the Israel-Iran conflict between 28th February till date introduced material macro headwinds for our business, disrupting export logistics and creating significant volatility in the raw material availability and cost.

The sharp spike in input prices necessitated a pass-through to selling prices, which temporarily softened market demand. Encouragingly, the situation has begun to stabilize from April. However, we continue to monitor the geopolitical landscape closely and remain agile in our response to any further developments.

For the current first quarter, the average sales realizations will be much higher.

EXPORTS: In the month of April, we have done reasonably well. And the consignments stuck in the month of March due to logistics issue. A lot of those consignments have been transited in the month of April. So, the average volume in exports have gone up on a month-on-month basis in the month of April and to May as well.

First quarter visibility is already there. So, we say that first quarter will see the continuity of the growth, which we have seen in the last quarter.

Big jump in other income: It’s mainly the M2M gain with regards to the debtors. 10cr.

PASSTHROUGH OF RAW MATERIAL PRICE INCREASE: So, in the month of March we have played a balanced approach. Wherever we had inventories, we have committed to our orders. And wherever I think the new orders we have taken at an average better rate.

We have taken price hikes starting from the March itself. So, even for the contracts which we were holding in hand and whatever the shortfall was there for the inventory, there also, we have been able to affect some price impact, price hikes and customers have accepted looking at the situation.

In March, of course, the full price hike was not available. So, March, there was an impact on our profitability, from the pass-through point of view because the inventories, when we talk about the inventories, there are two kinds of inventories; one is there in your hand and another is the orders which are in transit. So, what happened that in the month of March**, the cargoes of low price, which were supposed to come in the month of March, they didn’t arrive. So, you have to buy at the spot price, which was higher and we passed it on to the customer to some extent. So, March, we took some hit on account of buying something on the spot.**

But the advantage of held up cargo coming in the month of April at a lower price and that being used against the higher price. So, April will, in fact, would show better picture than March.

DEPENDENCE ON GOVERNMENT SPENDING: See, of course, this industry is connected with the government spending. But over a period of time, we have seen that this industry has diversified means the cable producers today are not only dependent upon the government spending on infra projects because solar and all activities are equally done in the private sector. Solar installation is done with an equal intensity from the private sector players, be it Adani, be it Tata, be it JSW, be it Reliance. So, that is continuing to generate demand.

Second is, of course, one may assume that government spending will go down. But again, government has to prioritize where to spend. And looking at the energy sources disruption, the government is putting even more rigorous efforts on renewable side.

We have all seen that the peak demand for energy during the summer season is going to be a big challenge. And for that, a lot of efforts are being made to keep our grid and the distribution system in a healthy manner. So, all these things are going to support the demand for wire and cable industry.

And on top of that, the demand for the reconstruction and demand for keeping the safety stock of all critical capital goods item, the cable demand has gone up in the Middle East and North African region, the regions which have been affected very badly by this war. So, we do not see any impact on our demand or our financials or our cash flows because of this perceived cut in the government spending.

COMPETITION: In XLPE, we are the largest player. In XLPE, the competition is from overseas players like Dow and Borealis.

Now, the low-voltage segment, there are a couple of Indian producers like KLJ Polymers. And in HFFR, Shakun Polymer, which is now part of Orbia Group from Mexico, they are our competition.

ENTRY BARRIER: And as far as entry barrier is concerned, it is a very critical and reliability related product. So, proven performance is the biggest entry barrier. Those who are performing for a long period of time will gain business.

Somebody coming up with the capacity instant and trying to secure the business, it is not something which is possible. You have to go through the approval cycle. And even despite going through the approval cycle, once you are approved, then you have to establish your performance over the period of time to become a leading and reliable supplier.

Import pressure from China: China import pressure direct or indirect will always remain in every segment, but our scale and our capability is quite strong, and we are able to face it off without any challenge.

• We are able to pass-through the price increases, which means we are able to maintain our fixed margins per kg basis.

• In optical fiber, our product application is limited.

• For most price pass through, it is a lag of seven days to 15 days. But again, it depends upon the intensity of the price hike. For example, the price hike is less than 1%, okay, then seven to 15 days lag is there. But a price hike, as we have seen, which was very volatile and very aggressive price hike in the month of March, then the pass-through was instant.

CONTRACT STRUCTURE: We don’t have those kind of fixed price or annual contracts. Maximum cycle of the contract, what we have and that is for mostly export, is around maximum 90 days. And there also, we have back-to-back import bookings. So, that kind of open-ended contracts are not there.

RAW MATERIAL SOURCING: We source from both domestic and import sources. In domestic we have all the big petrochemical players as our suppliers. Similarly, on import side, we rely on a lot of big players in the Middle East as well as in European countries. We are importing close to 10% to 15% of our requirement as an import.

And there were issues till, I will say, mid of April, where the supply constraints were there. However, today, the supply is more or less normalized. In India, we are getting sufficient material and import slowly and gradually are coming into the country.

As far as the price is concerned, there has been substantial volatility and the prices have gone up beyond 50% inflation. And now the prices are comparatively stabilized.

We are getting sufficient order book, and there is no lag as far as demand is concerned.

220KV and 440KV PRODUCT DEVELOPMENT: Each and every high-voltage cable, stabilization takes time as well as the next voltage stage will be requiring a lot of certifications for which the life required is minimum three to four years’ time.

So, right now, once 132 kV stabilizes in the Indian market, we’ll start working on 220, which is expected to take around three to three and a half years minimum for getting the certification and then the testing period. So, we anticipate four to four and a half years. So, we have targeted 2030 for our 220 kV cable compounds, whereas 440 will take further time based on this.

THINGS TO TRACK:
**• VOLUME GROWTH & EBITDA PER TON **
**• EXPORTS & US MARKET **
• HFFR SEGMENT
• 132KV SEGMENT
• PVC SEGMENT & ENTRY OF NEWER PLAYERS
• BESS SEGMENT AND ITS PROGRESS
• IMPACT OF IRAN WAR

Execution of Monitorables in FY26 for ddev.

FY26 performance was very mediocre due to various issues (Iran war, extended monsoon), and company fell short of its long term volume growth guidance of 12-15%. Margins were muted as well.

But nothing seems to be broken fundamentally. Management appears very confident for FY27. BESS vertical will start scaling up. Capacities have been expanded. Export demand remains strong

So it remains to see how they perform and will they revert back to 12-15% growth rates.

DISCLOSURE: INVESTED

Ddev is targeting revenue of 4000 cr by FY’30 with ebita margin of 5% to 8% and working capital cycle of 60-75 days they will be needing 750Cr to 900Cr , these funds will be supported by mix of debt or internal funds, their cfo is 85 cr to 100cr in next 4 year generating these fund is not possible from internal means.

Q1FY27:
• Gross margins – 16% (vs 16% yoy, 20% qoq)

• Expanding our international footprint remains an important pillar of our long-term growth agenda. Building on this, our exports have doubled to ₹312 crore in the quarter, despite geopolitical challenges.


• BESS: PHASE 1: 5 GWh assembly plant expected by Q1 FY28 (1st quarter of FY 2027-28). Investment of ₹150–200 crore funded through internal accruals, capacity aligned with early market demand.

(Delay of 2 qtrs in BESS commissioning)

• Production Volumes: 52163 MT (0.08% yoy growth)

• EBITDA Per Ton: 19177 (vs 15304 yoy)

• Awaiting underwriters’ approval for direct exports to Americas.

• Increasing the HFFR capacity to 20,000 MTPA by FY27 • Expanding XLPE compound capacity in East by additional 6,000 MTPA by FY27.

CONCALL NOTES:

Increase in EBITDA per ton: Major reason is driven by the exports. If you see the export of close to INR300-plus-odd crores, mainly to the MENA region, had been the main contributor. In volume terms, there has been no major growth in terms of export. It can be hardly few percentage in single digit or so. However, in terms of value, because there have been multiple issues. One, uncertainty over the freight rate, uncertainty over the availability of raw material prices. So, we could get better prices as compared to other competition in the Middle East and other markets. And that is the reason in export, we have done better. And that is the reason the overall EBITDA per ton has moved almost by INR3 in this particular specific quarter.

Volatility or war-risk premium is the reason there has been some additional EBITDA per ton derived on an overall quantity, which we have sold.

• Do you think this EBITDA per ton is sustainable or as the things ease out on the logistics front in the export, this can again come back to the normalized level that we saw last year?

So, it is very difficult to predict on this line. But definitely, as a conservative approach, we can say that our targets of INR16 to INR17, is something which we always aim and we have focused approach to achieve that only. So maybe INR19.6 something which has been achieved in this quarter may not be sustainable for each and every quarter, but probably it can be sustainable for a few months from here also.

BESS:
o Business is getting shifted from West to East. So, it will get delayed by a couple of quarters from here.

o To start with, it will be supply and mix of EPC over a period of time. BOO and BOOT, both models are something which, as of now, we are not eyeing on an immediate start basis

o EBITDA MARGINS: Since it will be initially a supply model, we expect an EBITDA margin of 6% to 8%. With passage of time when we adopt EPC and when we adopt other models, then slowly and gradually it may improve. Generally, when you add EPC, there is an addition of from 2% to 5% something you can get. Then there is an opportunity of becoming a system integrator where it is practically more than EPC and less than a BOO model. So there, you can add a couple of more percentages also. So, in each stage, practically, if you ask me, there are 2% to 3% where you can keep on adding on the EBITDA levels.

o Why relocation from west to east: So, the biggest rationale is that there is an opportunity in East. As of now, there are no player in East.

Now Bengal is an opportunity. And with Bengal government now coming up with their own industrial policy in the next 5 to 6 days, it will give us more leverage to shift our project over there and get the benefit out of it.

They are already working on the incentive policy, and there has been a lot of buzz in the newspaper and news for the last 7, 10 days that it will be out by end of August. So we are awaiting that policy before taking a final decision as far as the location. However, it is clear it will be coming to Bengal. Where in Bengal is something which is getting finalized in the next 5 to 7 days.

Confident of maintaining the 15% volume growth guidance.

We are confident of achieving 15% volume growth this year despite the first quarter being low on the growth having just 1% growth because this first quarter was full of uncertainty because the local demand went down because of very high prices in the first quarter.

But going forward, we see that as the uncertainty on the price front subside, the volume pickup will be back.

So, we targeted 2,31,000 tons for this entire fiscal year. First quarter is lower because of the uncertainties involved, whether that is in the export market or in the domestic market. And we are confident that the differential roughly 1,80,000 tons, which gives a proportionate rate of 60,000-odd tons per quarter, is something which is achievable.

• As far as the overall conservative annual guidance is concerned, we continue to maintain that whatever guidance we have given, we will definitely surpass it given that first quarter has been, a proportionate basis, is much better than what we expected.

• Exports in terms of volume, last quarter, whatever volume we have done in this particular June quarter, the next quarter comparatively will be better.

Increase in finance costs: Prices, there was a sudden increase in raw material prices in the month of March. And because of that, if you see the March inventory was comparatively higher and the debtors are comparatively also higher. So, the immediate requirement of finance could not be driven by internal force. We have to look for alternative source of finance, which is the working capital sources. So that is the reason the finance cost has risen. And now from the month of, I will say, July, it has started slowly gradually coming down.

• We have always said that we are having lower market share in this medium voltage XLPE category. And that is where we see a possibility of increasing our market share, and that is why we went close to the customers in North by putting up a new capacity.

• So as of now, our segment with them is 3 categories. One is the low voltage, 1.1, 3.3 segments. The medium voltage, I will say, ranging from 11 to 66 and so. And to some extent, we are now working for the high voltage for 72 to 132, where comparatively, our volumes are very less today. It will grow over a period of time.

• European Union FTA will have a direct benefit to us because we are already exporting to a couple of customers, good quantities in Europe. And the moment the duties come down, it will increase our competitiveness.

THINGS TO TRACK:
**• VOLUME GROWTH & EBITDA PER TON **
**• EXPORTS & US MARKET **
• HFFR SEGMENT
• 132KV SEGMENT
• PVC SEGMENT & ENTRY OF NEWER PLAYERS
• BESS SEGMENT AND ITS PROGRESS
• IMPACT OF IRAN WAR

1 Like

ARFY26 NOTES:

  • Only player in India offering products across 66 kV–132 Kv XLPE compounds.

  • 5,000 Crores in revenue from our polymer compounding business, complemented by an additional 1,000–1,500 Crores from the BESS business by FY30.

  • The Indian wires and cables industry—our largest end-use market—is projected to grow at a CAGR of approximately 9% through 2031, outpacing global growth, while the plastic compounding market is expected to expand at a CAGR of around 9.5% through 2033.

  • The Company faces intense competition from the unorganised sector and imports in the plastic compounds segment.

  • The polymer compounds industry remains competitive, with both domestic and international players across key product segments, resulting in continued pricing and market-share pressures

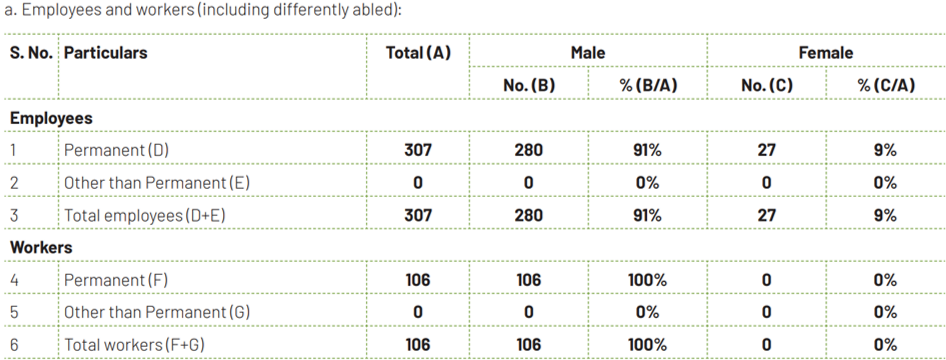
  • There were 306 permanent employees as on 31.03.2026. (391 PY)

  • The median remuneration of the employees in the financial year was increased by 3.27%. (-6.11% PY)

  • Average salary increase of non-managerial employees is 18.39%. (13.6% PY)

  • Average salary increase of managerial employees is 9.65%. (10.6% PY)

  • The global wire and cable compound market size was valued at USD 15.95 billion in 2025 and is projected to grow from USD 16.75 billion in 2026 to USD 24.83 billion by 2034, at a CAGR of 5.04% during the forecast period 2026–2034.

  • The global XLPE market is estimated at USD 10.12 billion in 2026 and is projected to reach USD 13.26 billion by 2031, at a CAGR of 5.56%.

  • The global XLPE cables market is projected to grow at a CAGR of 7.3% from 2026 to 2030, driven by increasing adoption of renewable energy sources and infrastructure development.

  • The global HFFR (Halogen Free Flame Retardant) market size was valued at USD 12.8 billion in 2025 and is estimated to reach USD 22.6 billion by 2034, exhibiting a CAGR of 6.5% from 2026 to 2034.

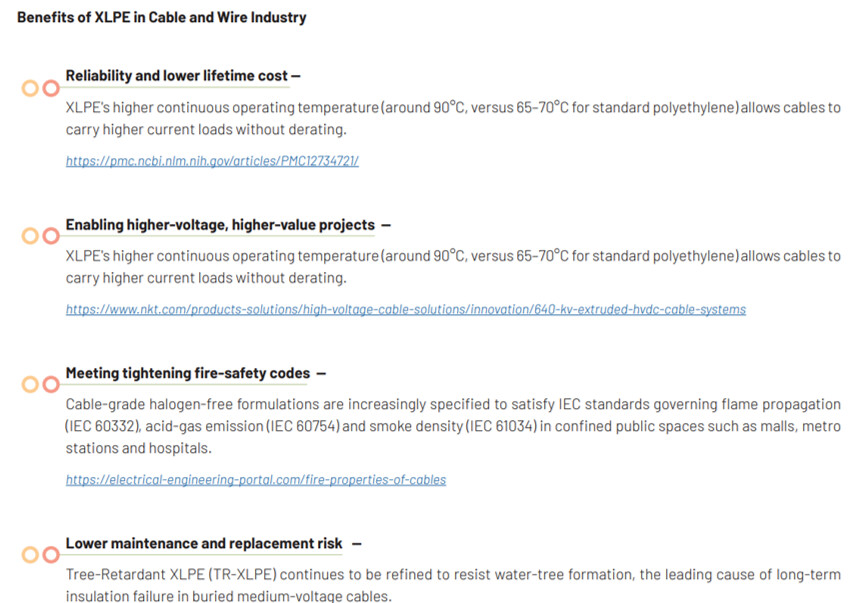
  • In India, thermoplastic compounds (PVC, PE) hold 65–70% of volume, while engineering-grade materials (HFFR, LSZH, TPE) grow faster at 10–12% annually on tightening fire-safety norms

  • India remains a net importer, with imports at 25–30% of market value in 2026, concentrated in specialty flame-retardant additives.

  • Rising XLPE adoption for MV/HV cables and growing multinational compounding capacity in India are shifting the market up the value curve.

  • Product Qualification Cycles Create Entry Barriers: Extensive and time-intensive product qualification processes required by customers act as a natural barrier to entry, protecting the Company’s market position against new entrants

  • Customer-specific Technical Formulations: Customised, technically differentiated formulations developed for specific customer applications strengthen relationships and reduce switching risk.

(391 employees and 0 workers in FY26)

  • Royalty expense to Kkalpana Industries (India Ltd) – 0 (vs 4.6cr in FY25 and 16.6cr in FY24). (RED FLAG has turned into a GREEN FLAG.)

  • Remuneration and rent paid to directors and promoters – 2.9cr (PAT – 202cr). 1.3% of PAT.

1 Like