This company is stuck in a place where number of companies will quickly reduce and consolidate. Though operating in a large space, is sandwiched between GCCs, large ESPs, IT companies and some boutique firms. With DNA of onsite placement and subsequent acquisitions only becoming burden to the management bandwidth, this company will require a real game changer to be in consideration. Its primary investor is great, but the positioning is such that it requires a restart to be a significant player and it is anybody’s guess if restart is possible after making as many acquisitions as it has done. Mistral is one of the more value adding, but it needs to be seen how it gets integrated with completely different views/cultures of Axes Cades. I would consider only when I see an evidence of value creation on ground.
All the best.
Interesting interview of Astra micro where the mgmt says they will be surprised if PAT is not 3-4x in next 3 years. Shows the tailwinds experiencing in RF/EWF industry as a whole…
Co’s Net Profit Could Move Towards ₹400-500 Cr In The Next 3 Years: Astra Microwave
Mr SRN is restructuring the management team and bringing his guys in to the company now.
I found that Mr SRN was previously the CEO of Axiscades till 2014 as well.
Does anyone know why Mr SRN had left the company in 2014?
Observations:
The stock price had gone nowhere for 5 years while he was ceo
The stock went up from 60 to 300 in a matter of two years from 2014 to 2016 after he resigned.
The foundations for the 60 to 300 that you saw in 2014-2016 was built in 2009-2014 …
Hi all,
Sharing my initiating coverage report on AXISCADES Technologies — includes insights from management meetings and plant visit.
Open to discussions and would love your feedback!
In the past, Chandrasekhar has been criticised for being a member of the standing committee on defence while also owning companies in the defence sector – like Axiscades.
At least three entites controlled by Chandrasekhar have sold a part of their equity to global firms active in the defence sector. Is this company politically involved?
Excellent results, with the business progressing towards its goals.


Nice article on Axiscades covering MRO, semiconductor (ESAI), Aerospace and Defence verticals.
AI short summary:
AXISCADES Technologies is emerging as a key player in India’s ₹1.85 lakh crore defense acquisition, targeting $1 billion in revenue by FY30 through a shift toward product-driven, high-margin defense and aerospace solutions. The company is expanding its missile component capabilities and accelerating growth with a ₹14,000 crore order pipeline and significant investments in new manufacturing infrastructure.
AXISCADES TECH: CO TO SELL HEAVY ENGINEERING, AUTOMOTIVE & ENERGY ENGINEERING BUSINESS TO AKKODIS IN USD 30.63 MILLION DEAL

Howler ? Pretty bad results.
For Q4 FY26, revenue from operations stood at Rs. 273 crore, up 2.0% year-on-year. Q4 profitability
was impacted by programme-linked revenue recognition moving into FY27 due to supply-chain and
operational timing factors, and by exceptional-item impact recognised during the year. The underlying
contract values remain intact, and customer relationships remain unaffected.
Result
Press release
Deferenent of revenue is accepted.. So We are seeing lower sale..
But what about fall in operating margins… they should have given better clarity in this regard
Revenue got deferred. But material purchases and fixed costs can’t be deferred. So margin was bound to go down. Look at their balance sheet. Other current assets have increased from 62 cr to 198 cr. I think these are the unbilled revenues which will be realised in Q1 and at max, Q2. The main thing we should ask from the management is how much will the margins improve after the sale of engineering services business and what topline to expect in FY27 from the residual business.
How do you guys read into the fact that fy27 rev guidance is ~ 1400 crs which is 20% over fy26. however of this 1400 crs, 142 crs is the reve deferred from fy26. without this 142 crs the actual rev in fy27 will be around 1258 crs which is just about 8% growth over fy26. for an organization that is targetting 8x rev growth (9000 crs by fy 30 from 1156 crs in fy26) this seems pretty low right? am i missing something. your views would be welcome
While mgmt has stuck to its fy30 guidance. What I still can’t understand how are they planning to fund the capex of roughly 2000crs for next 3 yrs without equity dilution or significant debt raise? What are their actual plans here now that they have already sold their engineering services business for $30m.
There is a fair chance the management will do a QIP with a tier 1 global defence co- my bet would be Brazil based Embraer.
Current equity base is just 24 crores, which is improbable for a co of their size and ambition. Aside- cos like Axiscades should be judged on YoY basis rather than QoQ as defence revenues are known to be lumpy.
The guidance should be taken as growth over the resdual business (903 crores for FY26) after engineering services sale. And since the low margin/loss making business has been hived off, EBITDA margins are expected to be over 20% (15% for FY26). So good growth in bottomline should be expected in FY27.
It’s not just the $30m (₹290 crore), they also sold their Aerospace Engineering Services to Akkodis for $206m (₹1960 crore), combined ₹2250 crore. However, a meaningful portion is deferred or performance-linked and has not been received yet. That’s 16 years of growth and core expertise sold — scary for any business, but in this case, management is walking the talk and here’s their plan for spending the money:
- DAC (Devanahalli Aerospace Campus) — ₹1200 crore
- MAC (Missile Atmanirbhar Complex) — ₹300 crore
- DAL (Digital Avionics Lab) — ₹120 crore
- Four acquisitions — ₹600 crore
Cloudwave is into aerospace, defence & semiconductors. Company has a decent share of revenue form exports and is also a supplier to domestic tier I companies like BEL.
Axiscades Aerospace business pivoting from service to manufacturing. This was the acquisition, company was referring to, in the recent call. Good to see the management walking the talk.
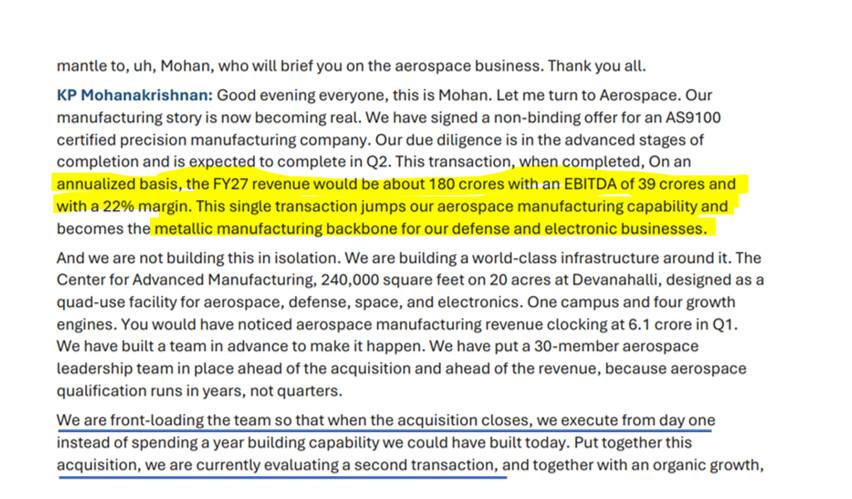
They are also evaluating a second acquisition. With organic + inorganic growth combined, targeting an annualized revenue run rate of 375 crores and 84 crores in EBITDA by Q4 FY27.