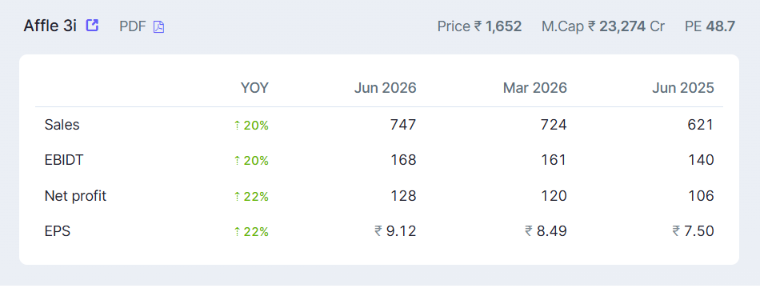
Tax rate was only slightly lower YoY (17% vs 19% now).
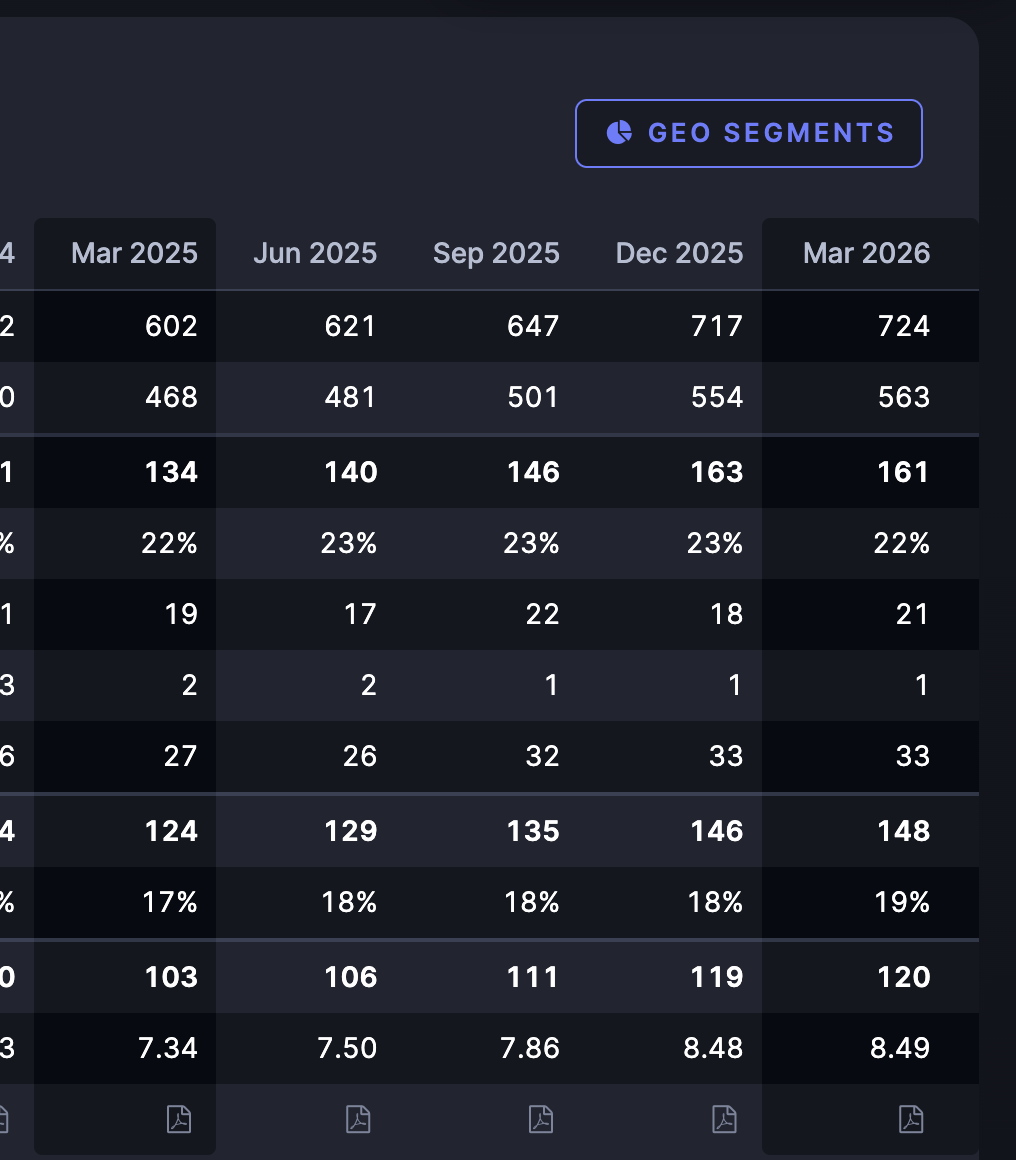
Also, the point made was topline growth potentially stagnating. Bottomline being flattish is less of a concern with topline growing as a lot of things can still result in flattish PAT.
Tax rate was only slightly lower YoY (17% vs 19% now).
Also, the point made was topline growth potentially stagnating. Bottomline being flattish is less of a concern with topline growing as a lot of things can still result in flattish PAT.
Top line always looks flat from Dec quarter to Mar quarter because of how contracts are structured and how spending happens in the core markets for them.
A few things here why i think P/E is still high.
The first is expansion in North America, a major push into developed markets, which offer higher Revenue Per User (RPU) compared to emerging markets.
The second is raising up to $120 million to fund acquisitions, which could provide the inorganic boost needed to return to 30% growth.
Third is Cash Flow & Debt they have maintained OCF of around 25% CAGR over last 5 Years
If you see from GARP and Value Lens this is reasonably expensive for sure. Rather than 25% go with 10%
Q4 & 12M FY2026 Earnings Conference Call May 11, 2026
Page 2: We are firmly on course to deliver on our medium-term guidance of 20% CAGR as we progress towards our 10x decadal growth vision.
Page 5: on inorganic efforts, we continue to actively pursue growth opportunities that are strategically aligned with our 3i vision. To further bolster our readiness in closing the deals, our Board has approved a preferential issue of equity shares to strengthen our balance sheet. Post our shareholders’ approval, our corporate promoter, Affle Holdings, will invest to acquire ~7.4 million warrants at INR 1,487, totaling approximately INR 11 billion, with 25% upfront payment. This will ensure that we are well capitalized and ready to move swiftly this year on the right acquisition opportunities. This is a proactive step towards executing our inorganic growth strategy with the calibrated discipline and conviction that has defined our organic growth journey.
Page 12-13 : we have evaluated several companies - more than 10 and then we’ve shortlisted about 4 - where we are doing deeper due diligence, we are doing deeper assessments as well as negotiations. I wouldn’t want to give any color to the size of the transaction because there are a few small transactions as well.
We may do more than one in terms of how we execute through the rest of this financial year. I would say - stay tuned. As and when we are closer to and have a definite announcement on it, we will be very proactive in explaining our approach and strategy.
We are here and we have the necessary financial resources to execute in the very short term if needed. But we will take our own time. There’s no pressure to act like today or tomorrow, but we are making sure that we execute at the right terms at the right price with the right target company. We will be patient, calibrated and we will bring the right transaction to unlock value for our shareholders.
My understanding of the inorganic growth of the company: Not confirmation, but likely ecosystem: 1. independent DSPs 2. mobile ad-tech firms 3.CTV monetization platforms 4. identity graph companies 5. retail media tech 6. AI creative optimization firms & 7. performance marketing infra
Most probably EUROPE, Germany, UK, Sweden, etc
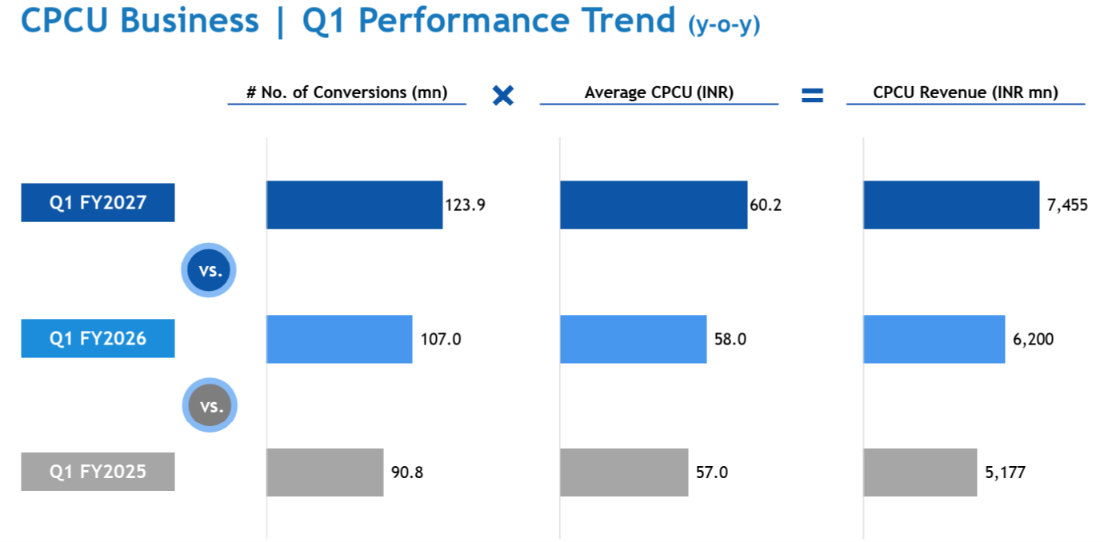
The most important risks to monitor are : inventory/data cost ratio, OCF/PAT, receivables + contract assets, conversion growth, acquisition quality and intangible asset productivity.
Affle remains financially strong, but future stock re-rating will depend on whether higher data costs, acquisitions and intangibles actually convert into stronger CPCU pricing, developed-market growth, cash conversion and PAT growth.
It may be noted that PAT growth is always lagging revenue growth due to high effective tax rate and high D&A cost.
Any news on why the stock is under pressure?
seems more like hitting SLs than anything. shareholder count is near its lowest since 2022